America
Trump’s tariffs trigger $2.5 trillion wipeout on Wall Street

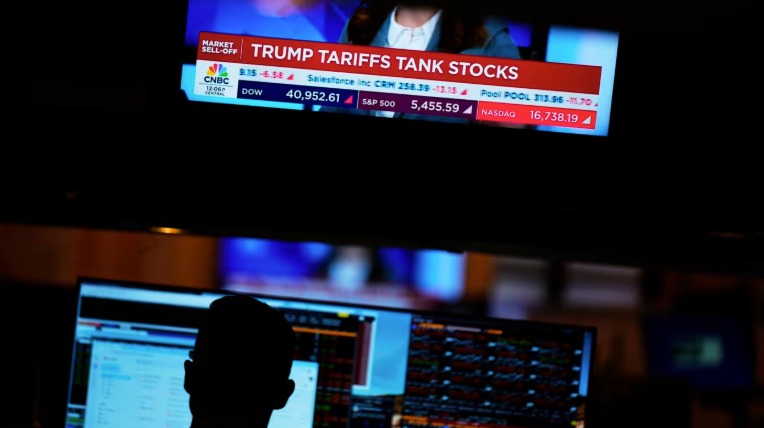
Following tariff impositions, Wall Street experienced a significant collapse, with $2.5 trillion evaporating from the market.
US President Donald Trump’s recent tariff policies, aimed at reshaping the global economic order, have wiped out approximately $2.5 trillion in market value from Wall Street stocks.
The President stated on Thursday evening that he “expected” his plans to raise tariffs to the highest level in over a century would cause turmoil in financial markets, adding, “The economy had too many problems… it was a dying patient.”
Although his announcement the previous day of a 10% general tax and higher tariffs on numerous countries shook investor confidence, he suggested the tariffs would herald “a thriving economy.”
According to calculations by the Financial Times (FT), based on FactSet data, the S&P 500 fell by 4.8% on Thursday, reducing the index’s market capitalization by $2.48 trillion.
The technology-heavy Nasdaq Composite dropped by 6%, marking its worst day since the 2020 coronavirus crisis. On Friday, European stocks extended their losses, with the Stoxx Europe 600 falling by 1% in early trading.
Japan’s Topix index closed down by 3.4%, South Korea’s Kospi index by 0.9%, and Vietnam’s Ho Chi Minh index by 3.7%.
Markets in China, Hong Kong, and Taiwan were closed due to a national holiday.
The dollar, which had already fallen by 1.7% against a basket of major currencies on Thursday, dropped a further 0.2% on Friday.
The declines erased gains made since Trump’s election victory in November.
Francesco Pesole, a foreign exchange strategist at ING, noted, “The collapse is a loss of confidence in dollar-denominated assets in general. This is a vote of no confidence against Trump’s [first] 100 days.”
IMF Managing Director Kristalina Georgieva warned that the Trump administration’s new tariffs posed “a significant risk” to the global economic outlook “at a time of slowing growth.”
Economists predict that the new tariffs will fuel inflation and hit growth, with US bank stocks falling due to recession fears; the sector’s KBW index fell by 9.9%.
Shares of Apple, the world’s most valuable company, fell by 9.3%, wiping over $300 billion from its market value, marking Apple’s largest-ever drop in market capitalization.
Nvidia and Tesla also experienced significant declines.
Global oil benchmark Brent crude fell by 6.7% to $69.94 a barrel.
Investors flocked to US Treasury bonds, seen as a safe haven during market turbulence. Short-dated bonds were the biggest beneficiaries, with two- and three-year yields seeing their largest movements since August 2024.
Short-dated bonds move on interest rate expectations, and Thursday’s yield increase suggests investors expect more interest rate cuts from the Fed. Yields move inversely to prices.
Trump argues that the tariffs will revive American manufacturing, encourage investment, prevent other countries from “robbing the US,” and generate trillions of dollars in revenue to fund tax cuts.
However, there are signs of tension within the US. Automaker Stellantis said it would lay off 900 workers at five US factories as a result of temporarily halting production in Canada and Mexico in response to Trump’s separate 25% tariffs on foreign automobile imports.
Consumer-focused groups, including sportswear group Nike and electronics retailer Best Buy, were among the worst affected due to concerns about how the latest tariffs would affect already pessimistic sentiment among American households and potential damage to supply chains.
Nike lost 14% in value, while Lululemon Athletica, Abercrombie & Fitch, and Gap also declined.




Richard Blumenthal, the ranking Democrat on the US Senate Permanent Subcommittee on Investigations (PSI), has requested documents from cryptocurrency exchange Binance, Tether, and crypto projects linked to President Donald Trump as part of inquiries into potential financial irregularities and conflicts of interest.
The documents were requested to be submitted by 4 January 2027.
Senators warned that they would resort to compulsory measures if the request was refused.
Entities sent document requests include World Liberty Financial and Fight Fight Fight LLC, both linked to President Trump’s family.
Blumenthal began examining the activities of these entities in May 2025 following reports that they may have engaged in transactions with foreigners under federal criminal investigation, attracted investments from foreign governments, and violated public ethics rules.
Notably, in 2026, it emerged that individuals close to the Abu Dhabi royal family had signed an agreement with the Trump family to purchase 49% of the shares in World Liberty Financial for $500 million.
The company, founded in September 2024 by the US President and his sons, launched a token called WLFI.
According to official disclosures, Trump made $800 million from this token alone.
Conversely, crypto analytics firm Nansen calculated, by tracking 1.48 million crypto wallets, that approximately two-thirds of those who invested in the token after its launch in January 2025 incurred losses.
While many retail investors spent several thousand dollars on purchases, the largest investors poured in millions of dollars.
Trump also launched his own memecoin, TRUMP, on 17 January 2025, prior to his inauguration.
Rising 10.6-fold in value within three days, the cryptocurrency’s market capitalisation reached $15 billion at its peak.
However, after those three days, the price entered a downturn, plunging by 97%.
Trump reported in his financial disclosure that he earned $635 million in income from sales of these memecoins.
In July 2026, Blumenthal held public hearings on the family crypto projects from which the President made $1.4 billion.
The losses suffered by TRUMP memecoin investors were also addressed during these hearings.
Cryptocurrency exchange Binance and Tether, which issues the largest stablecoin, USDT, are under scrutiny over their dealings with the Trump administration.
Lawmakers suspected conflicts of interest stemming from the exchange’s collaboration with World Liberty Financial.
Previously, a group of senators had demanded an inquiry into the terms of the presidential pardon granted to Binance founder Changpeng Zhao.
Separately, The New York Times reported that the United Arab Emirates (UAE) gaining access to American artificial intelligence chips coincided with a $2 billion investment by a UAE entity into Binance using USD1, a stablecoin issued by World Liberty Financial.
While this deal rapidly expanded the volume of tokens in circulation, it enabled Trump’s company to generate revenue from interest on government bonds where USD1 reserves were held.
Trump, for his part, described the report as slander.
Americans’ credit card debt reached a record $1.29 trillion in the third quarter, according to a new report published by the New York Fed.
Falling behind on credit card payments can trap struggling households in a cycle of fees, credit score downgrades, and increasingly expensive borrowing.
Although delinquency rates across the country have shown improvement, the latest figures indicate that financial distress is concentrated in lower-income communities.
Consumer credit card balances rose by $22 billion in the third quarter, representing an increase of 1.7%. This figure is $52 billion higher than it was a year earlier.
The figures are not adjusted for inflation, which may mean that part of the increase reflects rising prices rather than more borrowing in real terms.
Total household debt, which includes mortgages, student loans, and auto loans, rose by $334 billion in the third quarter to reach a record $19.1 trillion.
This total represents an increase of $5 trillion compared to 2019, just before the pandemic.
The volume of credit card balances falling into serious delinquency is declining, indicating some improvement in Americans’ ability to make their payments on time.
The rate of credit card debt transitioning into serious delinquency fell to 6.9% in the third quarter. However, this rate remains distinctly higher than the 5.2% recorded prior to the pandemic.
Americans living in lower-income neighbourhoods are facing greater difficulty in keeping up with their credit card payments compared to more affluent groups, according to a separate report published by the New York Fed on Tuesday.
Delinquency rates across all neighbourhood income tiers remain above pre-pandemic levels, while the gap between the wealthiest and poorest areas has widened since 2022.
In the lowest-income neighbourhoods, 10.3% of credit card balances transitioned into serious delinquency over the past year.
This is more than double the 4.4% rate observed in the wealthiest neighbourhoods.
The average credit card balance per borrower now stands at $6,678, according to TransUnion’s third-quarter analysis report.
Among borrowers under the age of 30, the rate of credit card debt falling at least 90 days delinquent reached the highest level, according to the Fed’s report.
Democrats won the midterm elections promising to bring down prices, but delivering relief that voters can genuinely feel in their household budgets will be a difficult target to achieve.
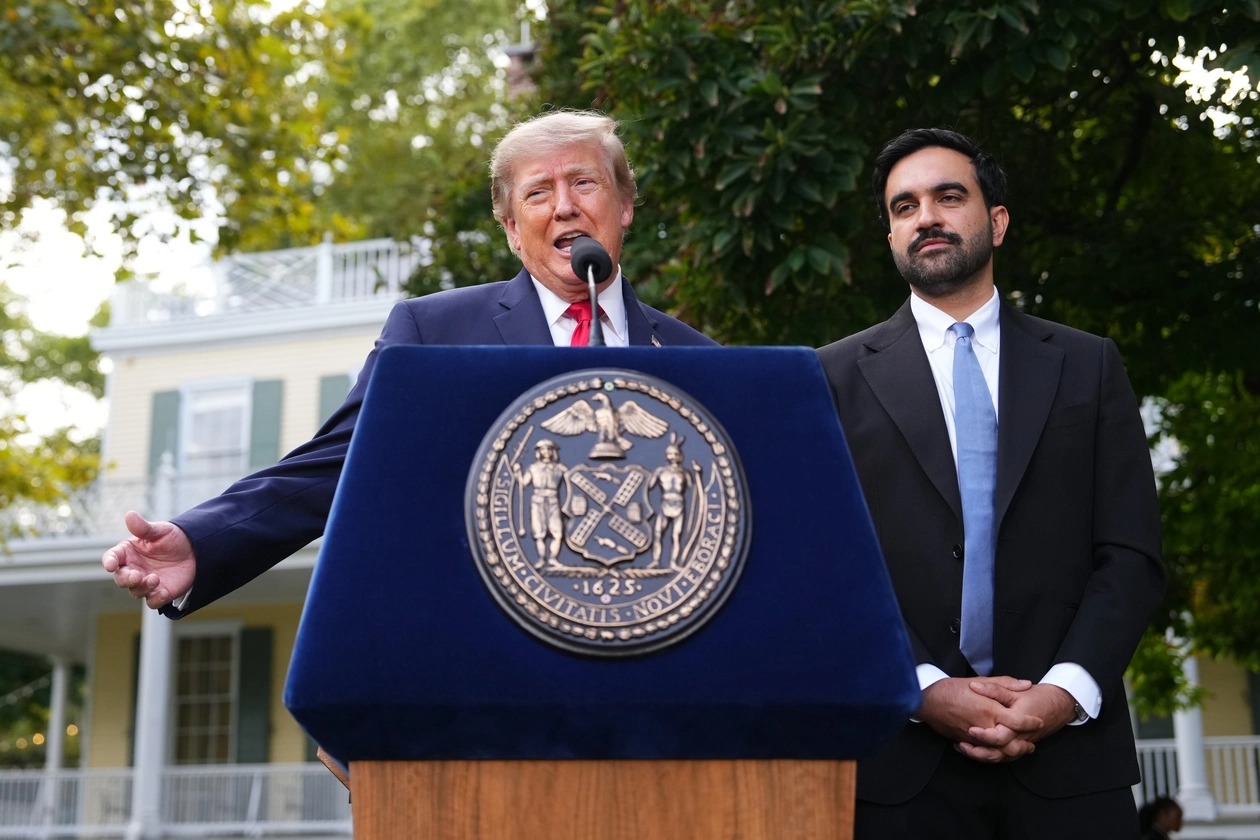
New York City Mayor Zohran Mamdani is using his rapport with US President Donald Trump to secure the release of selected detained immigrants.
According to reporting by Politico, Mamdani persuaded Trump during their second White House meeting in February to free a university student who had been detained that day by ICE.
The outcome served as validation for Mamdani, who pointed to the release of the Columbia University senior as proof that his surprisingly cordial relationship with Trump could produce tangible results for New Yorkers.
Mamdani subsequently continued to seek similar immigration-related interventions from the Republican president.
Since that February meeting, Mamdani and his aides have quietly forwarded the names of approximately two dozen immigrant New Yorkers held in ICE custody to Trump’s team, asking the president to order their release.
Two sources familiar with the matter said Mamdani most recently shared names of detained immigrants during a September meeting with Trump at Gracie Mansion.
The sources said the individuals in question had no serious criminal records, though they declined to disclose their identities, citing safety concerns.
According to Politico, these ongoing efforts regarding detained immigrants indicate Mamdani’s belief that he can leverage his rapport with Trump to advance causes the mercurial president might not ordinarily support.
Mamdani’s decision not to disclose these continued appeals publicly suggests an inclination to keep his interventions private to improve their chances of success.
Yet it remains unclear whether any immigrant besides Columbia University student Elmina Aghayeva has actually been released as a result of these efforts, and concern is mounting within City Hall that the window for securing such releases may be closing.
Mamdani’s aides working on the releases, including his Chief of Staff Elle Bisgaard-Church, communicated primarily with Trump’s White House Chief of Staff Susie Wiles, according to people familiar with the matter.
Last week, Trump replaced Wiles with Stephen Miller, the architect of the administration’s most hardline immigration proposals and one of the loudest internal voices urging the president to pursue a mass deportation agenda in his second term.
A person familiar with the Mamdani administration’s thinking said the mayor’s team views it as unlikely that Miller will continue cooperating in the manner Wiles did, given his stance on immigration.
Mamdani spokesperson Dora Pekec declined to comment on internal concerns regarding Miller and did not provide details about the immigrants whose release the mayor had requested.
Pekec noted, however, that Mamdani has “consistently advocated directly on behalf of New Yorkers in his calls and meetings with the president.”
Murad Awawdeh, a close Mamdani ally and president and CEO of the New York Immigration Coalition, said the mayor’s team should not halt engagement with the Trump administration on immigration matters because of Miller’s promotion:
“Stephen Miller is a cruel individual who has spent his career attacking immigrants, but he is not the president; Donald Trump is, and this is his deportation agenda. New York expects the president to work with the mayor to serve this city and end the terror in our communities. Miller’s promotion changes none of that.”
Mamdani’s warm dynamic with Trump has confounded both allies and critics.
During last year’s New York mayoral election, Trump referred to Mamdani as a “communist lunatic” and threatened to have him arrested.
In turn, the 35-year-old democratic socialist branded the president a “fascist” and pledged to fight him relentlessly if elected mayor.
Yet that animosity fell away late last year during their first White House meeting, where an amicable tone prevailed.
The thaw culminated in September at Gracie Mansion, where Trump said Mamdani had “great potential” to be a “terrific mayor.”
Mamdani returned the compliment by noting that the president had “built quite a bit of housing in our city.”
Despite the polite exchange, questions remain over how much substantive progress Mamdani can genuinely secure through Trump, including on immigration.
To date, Aghayeva’s release stands as one of the few concrete concessions Mamdani has obtained from Trump.
Aides on both sides are also discussing a multi-billion-dollar federally backed housing initiative in Queens, and last month Mamdani used his channel to Trump to help secure a temporary visa for a Ghanaian woman whose son was shot and killed in the Bronx.
Beyond those instances, few tangible results have emerged, though Trump’s decision not to enact punitive measures against New York is viewed by Mamdani’s allies as a win for the city.
Trump’s political standing is widely seen as weakened following the Republican Party’s loss of both houses of Congress in elections last Tuesday.
How this political shift will affect Trump’s willingness to engage with ideological adversaries such as Mamdani remains uncertain.
Miller’s appointment as chief of staff appears to signal little presidential interest in moderation, particularly on immigration policy.
Even so, the mayor said last week that he does not intend to stop seeking Trump’s assistance, despite “fierce” policy disagreements.
“We have found an area of common interest in the well-being of New York City, and as long as that can deliver for our city, I’m going to keep that door open,” Mamdani told Politico on Friday in Puerto Rico.
Mamdani and other elected officials from New York had gathered in Puerto Rico for the annual Somos political conference.
Two days later, in an interview on Fox News, a network Trump is known to watch regularly, Mamdani described a “productive relationship” with the president, saying the two text and speak by phone frequently:
“Through those conversations, we were able to get a New Yorker out of ICE detention. We were able to secure a visa for a grieving mother who would have otherwise had to watch her son’s funeral from thousands of miles away. What that tells me is: My job is to deliver for New Yorkers, and I have to work with whoever has the power to do that, wherever they may be.”

IRAM expert Oral Toğa assesses Middle East shifts after US vote

Netanyahu Arab party attack triggers crisis over coalition

Fico accuses Merz of blackmail over threat to veto EU budget

US Senate panel seeks records in Trump-linked crypto investigation

Europe ready for arms and missile control talks with Russia, FT says
-
 Diplomacy1 week ago
Secular dress code dispute exposes deeper Türkiye-Azerbaijan strains
-
 Russia2 weeks ago
US and Russia weigh energy deals and corporate return in peace talks
-
 Europe2 weeks ago
Merz visits Asia to seek new markets for German defence firms
-
 Middle East2 weeks ago
US warns Gulf allies of possible Iran strikes after midterms
-
 Opinion2 weeks ago
Gaza exposes the myth of the “most moral army in the world”
-
 Europe5 days ago
EU urges citizens to prepare 72-hour survival kits for crises
-
 America2 weeks ago
Democrats target Trump-Putin Russian diesel deal with legal push
-
 America2 weeks ago
Bolsonaro reportedly leaves Brazil on jet linked to scandal-hit firm
