America
Kevin Warsh signals support for new Fed-Treasury accord to redefine central bank role

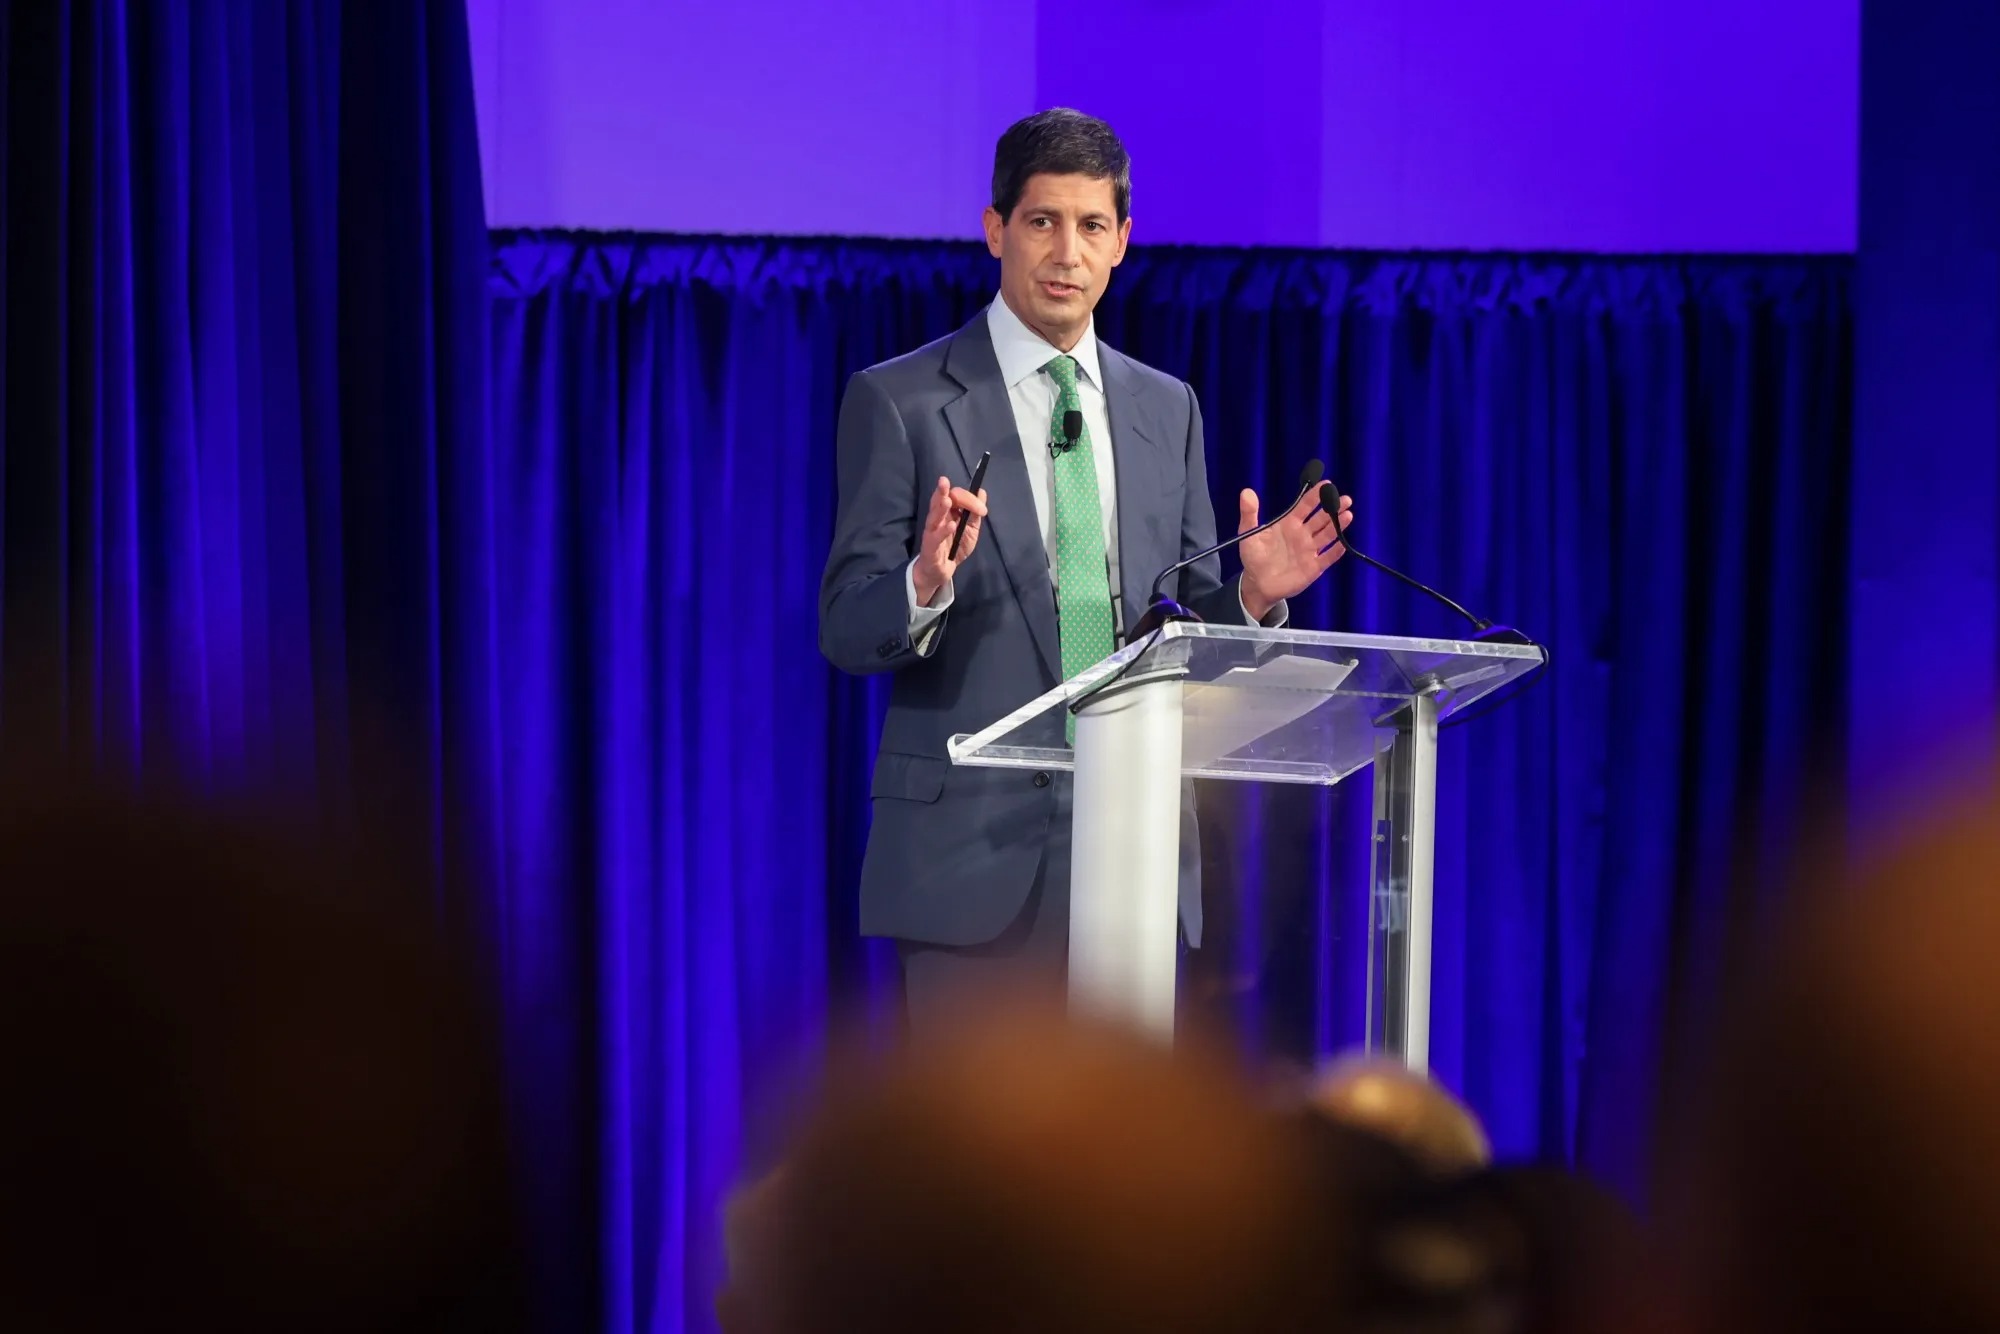
Kevin Warsh, Donald Trump’s nominee to lead the Federal Reserve, has signaled his support for a modernized version of the 1951 Fed-Treasury Accord, a move that would fundamentally recalibrate the relationship between the US central bank and the Department of the Treasury.
While the original 1951 agreement significantly limited the Fed’s influence on the bond market, the landscape has shifted dramatically following the purchase of trillions of dollars in securities during the global financial crisis and the Covid-19 pandemic. Today, the constraints of that historic deal are largely defunct.
Neither Warsh nor Treasury Secretary Scott Bessent have yet provided a granular roadmap for their actions once the new Fed leadership takes office. However, in a CNBC interview last year, Warsh suggested that a renewed accord could “clearly and carefully” define the scope of the Fed’s balance sheet while outlining the Treasury’s debt issuance strategies.
A renewal might manifest as a primarily bureaucratic adjustment with minimal short-term impact on the $30 trillion Treasury market. However, a more ambitious effort to overhaul the Fed’s current portfolio—which exceeds $6 trillion—could trigger heightened volatility and deepen existing anxieties regarding the independence of the US central bank.
The looming figure over these Fed-Treasury discussions is Trump, who argued last year that one of the central bank’s responsibilities in setting interest rates should be the oversight of government borrowing costs. These costs currently hover around $1 trillion annually, accounting for roughly half of the federal budget deficit.
The 1951 Accord was designed specifically to end such practices. During and after World War II, the Fed capped yields on both short- and long-term Treasury bonds to keep federal borrowing costs low. This policy, however, became a catalyst for soaring post-war inflation. In a landmark shift, the Truman administration eventually agreed to grant policymakers the autonomy to set interest rates independently, cementing the Fed’s operational sovereignty.
In April, Warsh contended that the Fed had effectively violated the principles of 1951 through the large-scale bond purchases executed in the wake of the financial crisis and the pandemic. In various interviews and speeches, he has argued that these interventions “incentivized reckless government borrowing.”
Bessent has echoed these criticisms, accusing the central bank of maintaining quantitative easing (QE) for too long, which he claims damaged the market’s ability to provide critical financial signals. The Treasury Secretary, who oversaw the vetting process for Jerome Powell’s successor, has advocated for the Fed to utilize QE only in “genuine emergencies and in coordination with the rest of the government.”
Consequently, a new agreement could explicitly stipulate that—outside of daily liquidity management—the Fed would only engage in large-scale Treasury purchases with the department’s approval, with the ultimate goal of halting monetary expansion when market conditions allow.
However, involving the Treasury in Fed decision-making in this manner is subject to varied interpretations. Krishna Guha of Evercore ISI noted that investors might interpret such a move as granting Bessent a “soft veto” over any quantitative tightening (QT) plans.
A more concrete version of the agreement would likely codify what many market participants already anticipate: a shift in the Fed’s holdings from medium- and long-term securities toward Treasury bills with maturities of 12 months or less. In this scenario, the Treasury could reduce bond sales or at least limit their increase.
In its quarterly refunding announcement on Wednesday, the Treasury Department drew a direct link between its issuance plans and the Fed’s actions, noting that it is closely monitoring the central bank’s recent increase in bond purchases.
“We are moving toward closer cooperation between the Fed and the Treasury Department,” said Jack McIntyre of Brandywine Global. “The real question is how far that cooperation will expand.”
Conversely, some investors worry that such moves could signal a pivot away from the Fed’s primary mandate of fighting inflation, potentially increasing volatility and raising inflation expectations. In a worst-case scenario, the appeal of the US dollar and the “safe haven” status of Treasury bonds could be compromised.
Ed Al-Hussainy, a portfolio manager at Columbia Threadneedle Investments, warned: “If there is an agreement implying the Treasury can rely on the Fed to purchase a portion of the debt or a segment of the yield curve for the foreseeable future, that is very, very problematic.”
On the other hand, Mark Dowding, chief investment officer at RBC BlueBay Asset Management, argues that Warsh remains committed to keeping the Fed distinct. “This does not rule out further cooperation, but it reduces the likelihood of a formal, binding agreement,” he noted.
Others have proposed broader scenarios where the Fed becomes part of a multi-stage effort to revitalize federal influence over the bond market. Guha of Evercore ISI floated the idea of the Fed swapping its $2 trillion mortgage-backed security (MBS) portfolio for Treasuries.
While such a move faces significant hurdles and remains unlikely, one objective could be to lower mortgage rates—a key focus for the Trump administration. Last month, the President instructed Fannie Mae and Freddie Mac to purchase $200 billion in mortgage-backed securities to limit borrowing costs for prospective homebuyers.
Richard Clarida, global economic advisor at PIMCO and former Fed Vice Chair, wrote that a new accord could “provide a framework over time for the Fed to reduce its balance sheet size in coordination with the Treasury and perhaps housing agencies like Fannie Mae and Freddie Mac.”
Warsh almost certainly cannot forge a unilateral agreement with Bessent. However, several current Fed policymakers have supported shifting the portfolio toward shorter-term debt, arguing that its heavy exposure to long-term assets no longer reflects current market structures.
Strategists at Deutsche Bank have predicted that a Warsh-led Fed would be an active buyer of T-bills over the next five to seven years. In one scenario, they foresee T-bills rising from their current level of under 5% to as much as 55% of the portfolio.
Nevertheless, a Treasury shift toward selling bills rather than interest-bearing bonds would be costly. Constantly rolling over massive amounts of debt would increase the volatility of the Treasury’s borrowing costs.
Whether a formal accord is reached or not, market participants now expect a significantly tighter relationship between the Fed and the Treasury regarding bond market policy.





The economic toll of the conflict on the US has reached $265 billion in the roughly eight months since the start of joint US and Israeli strikes against Iran.
According to calculations by Moody’s Analytics Chief Economist Mark Zandi, this amount imposes an additional burden of approximately $2,000 on the budget of an average American family.
Sharing data on his X account on Tuesday, Zandi noted that the cost per household since the war began stands at about $2,000, with nationwide economic losses reaching $265 billion.
This estimate is seven times higher than the direct military spending figure reported to Congress by Secretary of War Pete Hegseth, which covers the period between the start of the strikes on 28 February and the end of July.
While Hegseth’s official figures cover only direct military operations, the conflict’s impact on global markets and oil prices is driving up inflation and day-to-day living costs, deepening the real burden on household budgets.
Fuel and heating costs strain budgets
Energy items account for the largest share of the additional expenses facing American households. The surge in fuel, home heating, and transport costs has generated an extra bill of about $1,100 per family.
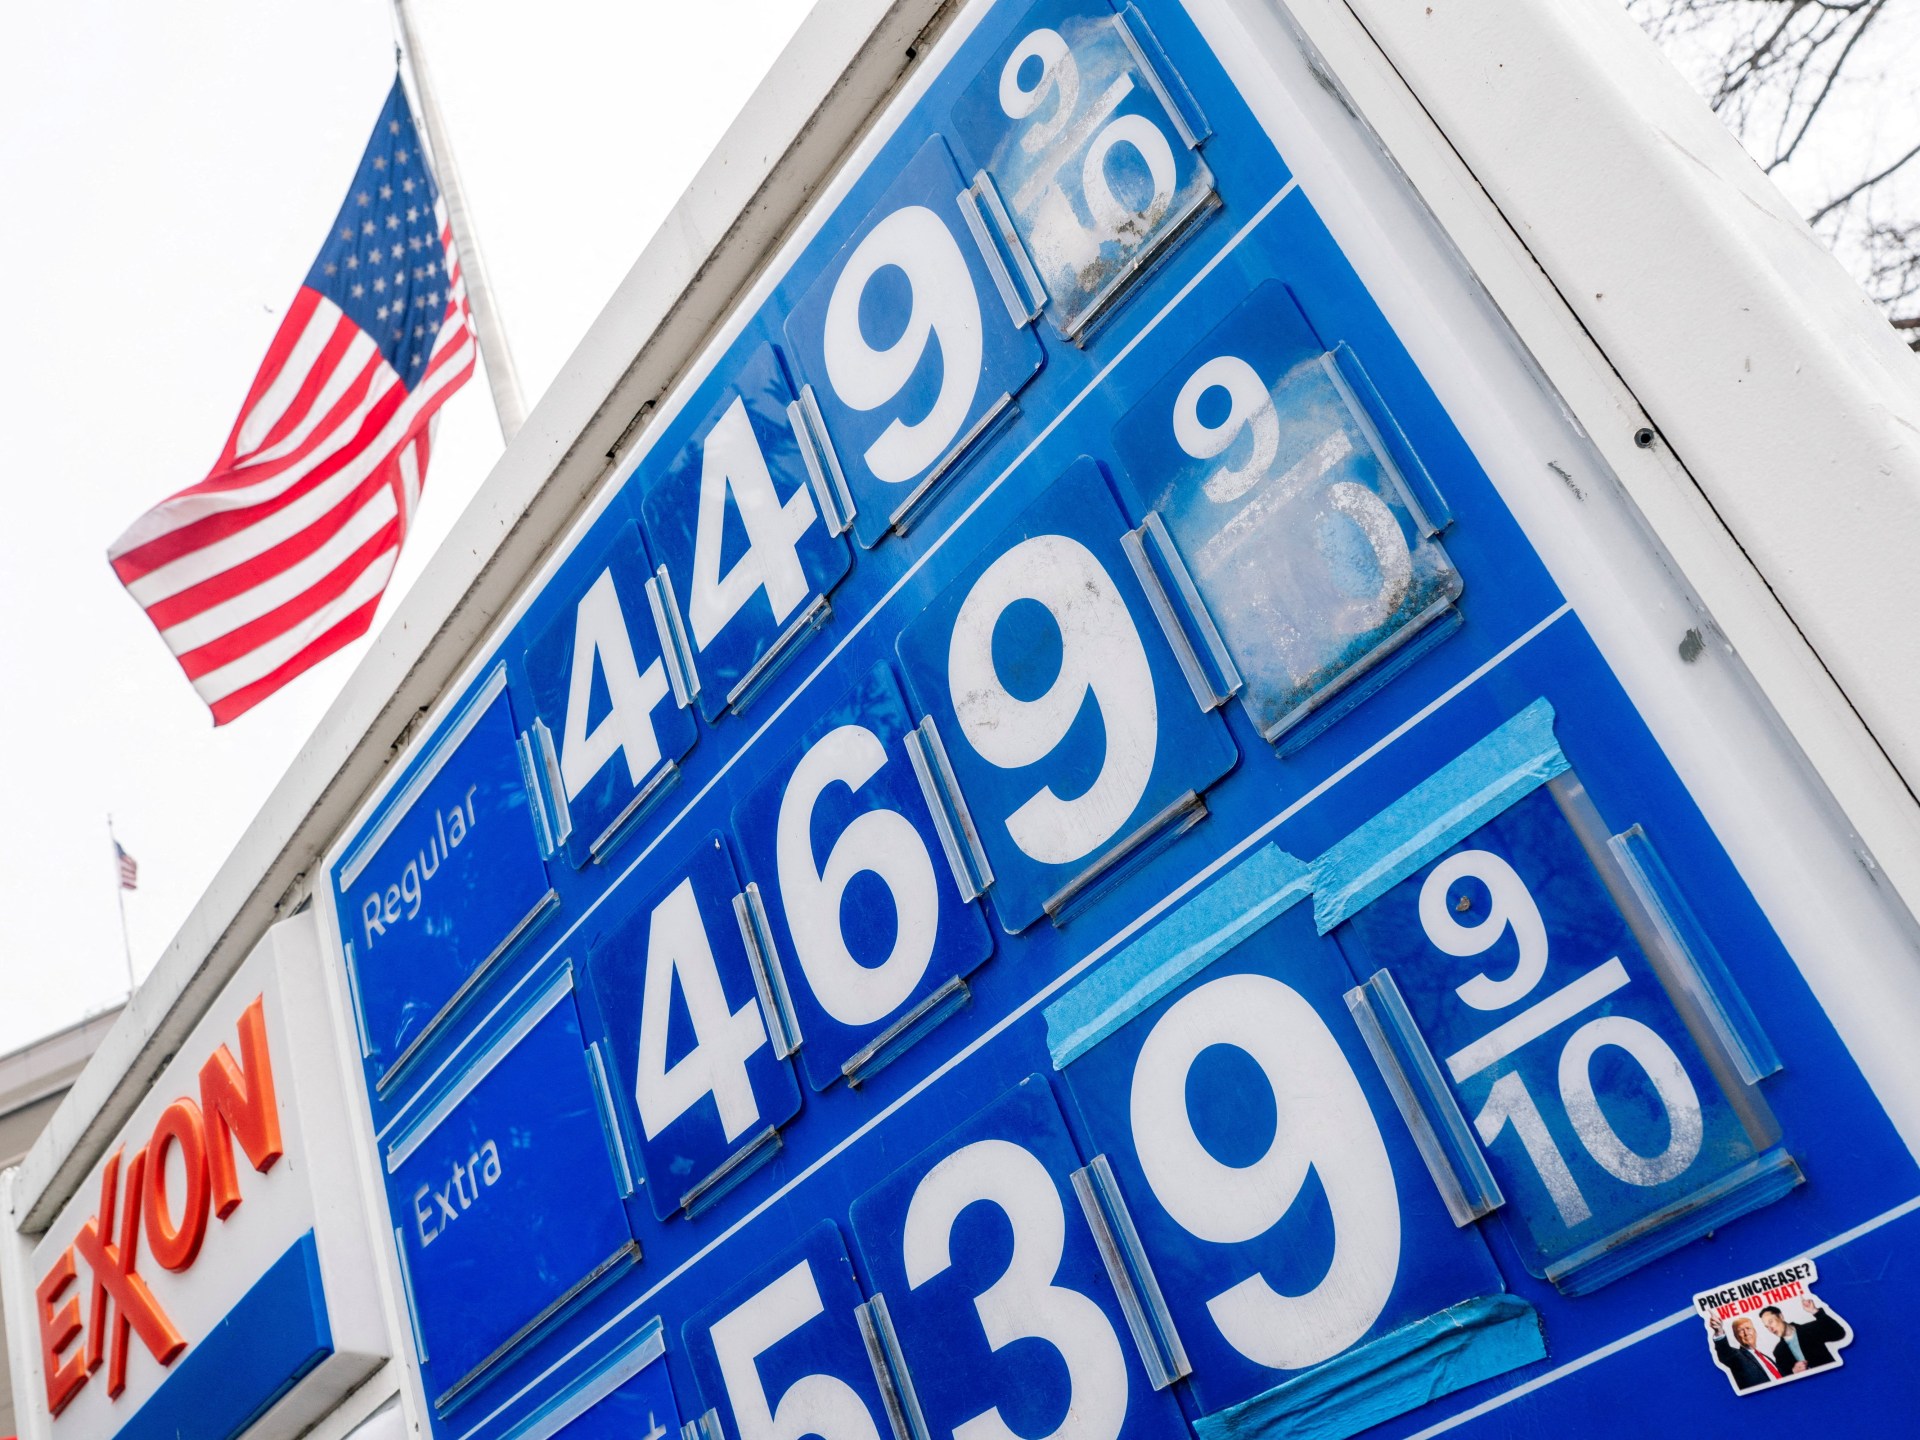
Zandi noted that the price of regular petrol, which hovered just below $3 per gallon before the war, has risen to $4.37, while diesel has exceeded $6 and jet fuel has nearly doubled.
Pointing out that a marked rise in residential heating fuel costs is driving up spending as winter approaches, Zandi said current price levels continue to add roughly $50 a week to family budgets.
Researchers at Brown University’s Watson Institute for International and Public Affairs are also tracking the impact of rising fuel prices on consumers.
According to data from the institute, US consumers have paid an extra $133.3 billion for fuel products since 28 February.
During this period, petrol prices rose by more than 46% and diesel climbed by over 70%. Of this additional burden borne by consumers, $73.5 billion stemmed from petrol and $59.8 billion from diesel. This calculation translates into an extra cost of $1,017.76 per household nationwide.
Loan interest rates and operational outlays inflate the bill
Another decisive factor in the economic picture has been the rise in interest rates.
Zandi reported that climbing interest rates have created a cost of approximately $540 per household.
Fixed-rate home mortgage rates, which stood below 6% before the war, have climbed to roughly 7.5%, Zandi said, adding that long-term rates have also increased substantially.
Direct military operations, meanwhile, represent a cost of $360 per household based on Pentagon data.
However, experts point out that repair, maintenance, and equipment replenishment expenses are excluded from the published figures, meaning actual military spending on the ground could exceed Pentagon estimates.
Linda Bilmes, a war budget specialist who teaches public policy at Harvard Kennedy School, said she is certain the conflict’s bill will reach $1 trillion, adding, “Maybe we’re already there.”
Trump defends spending as public support drops
The mounting economic strain is fuelling backlash against the military campaign and US President Donald Trump’s handling of the process.
A Pew Research Centre survey conducted on 28 September-4 October among 5,062 adults revealed that 65% of Americans disapprove of the way Trump is handling the Iran strikes.
The proportion of those who consider the use of military force justified dropped four percentage points compared with March, falling to 34%.
Emphasizing that the total cost has wiped out roughly half of the average American household’s income gains over the past eight months, Zandi said it is natural for public support for the war to remain so low.
According to figures shared by pollster Nate Silver, Trump’s net approval rating has tumbled to an all-time low of minus 23.5 points.
Defending the military intervention against Iran, Trump described the costs as “a small price to pay to keep our country and the world safe.”
With the surging cost of living piling pressure on Republicans ahead of the November midterm elections, Trump announced last month that he would provide a $5,000 cash payment to every adult in the country if his party maintains its majorities in both chambers of Congress.
The US Department of the Treasury has imposed a total of $1.21 billion in financial penalties on Bank of America, one of the country’s largest financial institutions, for violating anti-money laundering legislation and sanctions regimes.
According to a statement published by the department, the bank was accused of failing to report suspicious transactions in a timely manner, failing to monitor financial movements that posed national security risks, and providing services to clients on sanctions lists.
Decisions by units operating under the Treasury Department accounted for the largest components of the penalty package.
The Financial Crimes Enforcement Network (FinCEN) penalised the bank for failing to report more than $5 billion in suspicious transactions in a timely manner.
More than $1 billion of that amount was noted to be directly linked to national security risks, including the operations of China-based money laundering networks.
Under the settlement reached with FinCEN, Bank of America admitted to willfully violating the Bank Secrecy Act. The bank was required to conduct an additional review covering suspicious transactions and to assess the effectiveness of its financial monitoring system.
The Office of the Comptroller of the Currency (OCC) separately fined the bank $750 million over structural deficiencies in its financial monitoring system.
The OCC stated that the bank failed to maintain adequate oversight over trillions of dollars in fund transfers and did not remedy the violations despite a formal notice served in December 2024.
The Office of Foreign Assets Control (OFAC) also stepped in over millions of dollars in transactions carried out in breach of sanctions regulations. OFAC reached an $11.6 million settlement agreement with Bank of America concerning 475 distinct potential sanctions violations.
Assessing the matter, US Treasury Secretary Scott Bessent said, “The actions taken today send a clear message that even the largest financial institutions are not above the law.”
UK fines banks over breaches of Russia sanctions
Alongside the penalty decision in the US, similar sanctions scrutiny is being carried out across European financial centres.
In September, the Office of Financial Sanctions Implementation (OFSI), an agency of the UK Treasury, fined Citibank’s London branch (CBNA London) £4.7 million for violating sanctions targeting Russia.
According to findings by the British regulator, between February and November 2022 following the outbreak of armed conflict between Russia and Ukraine, the bank processed 970 payments worth a combined £19.7 million, circumventing asset freezes and other restrictions. The government stated that the majority of the violations were linked to corporate accounts owned or controlled by sanctioned individuals. Russia, meanwhile, describes sanctions imposed by Western nations as illegal.
During the spring, OFSI also fined the London branch of Germany’s Deutsche Bank £165,000 ($221,000) for transferring funds to the Russian online streaming platform Okko.
Over the same period, the watchdog imposed a £390,000 fine on Apple’s European entity, Apple Distribution International (ADI), for a similar violation.
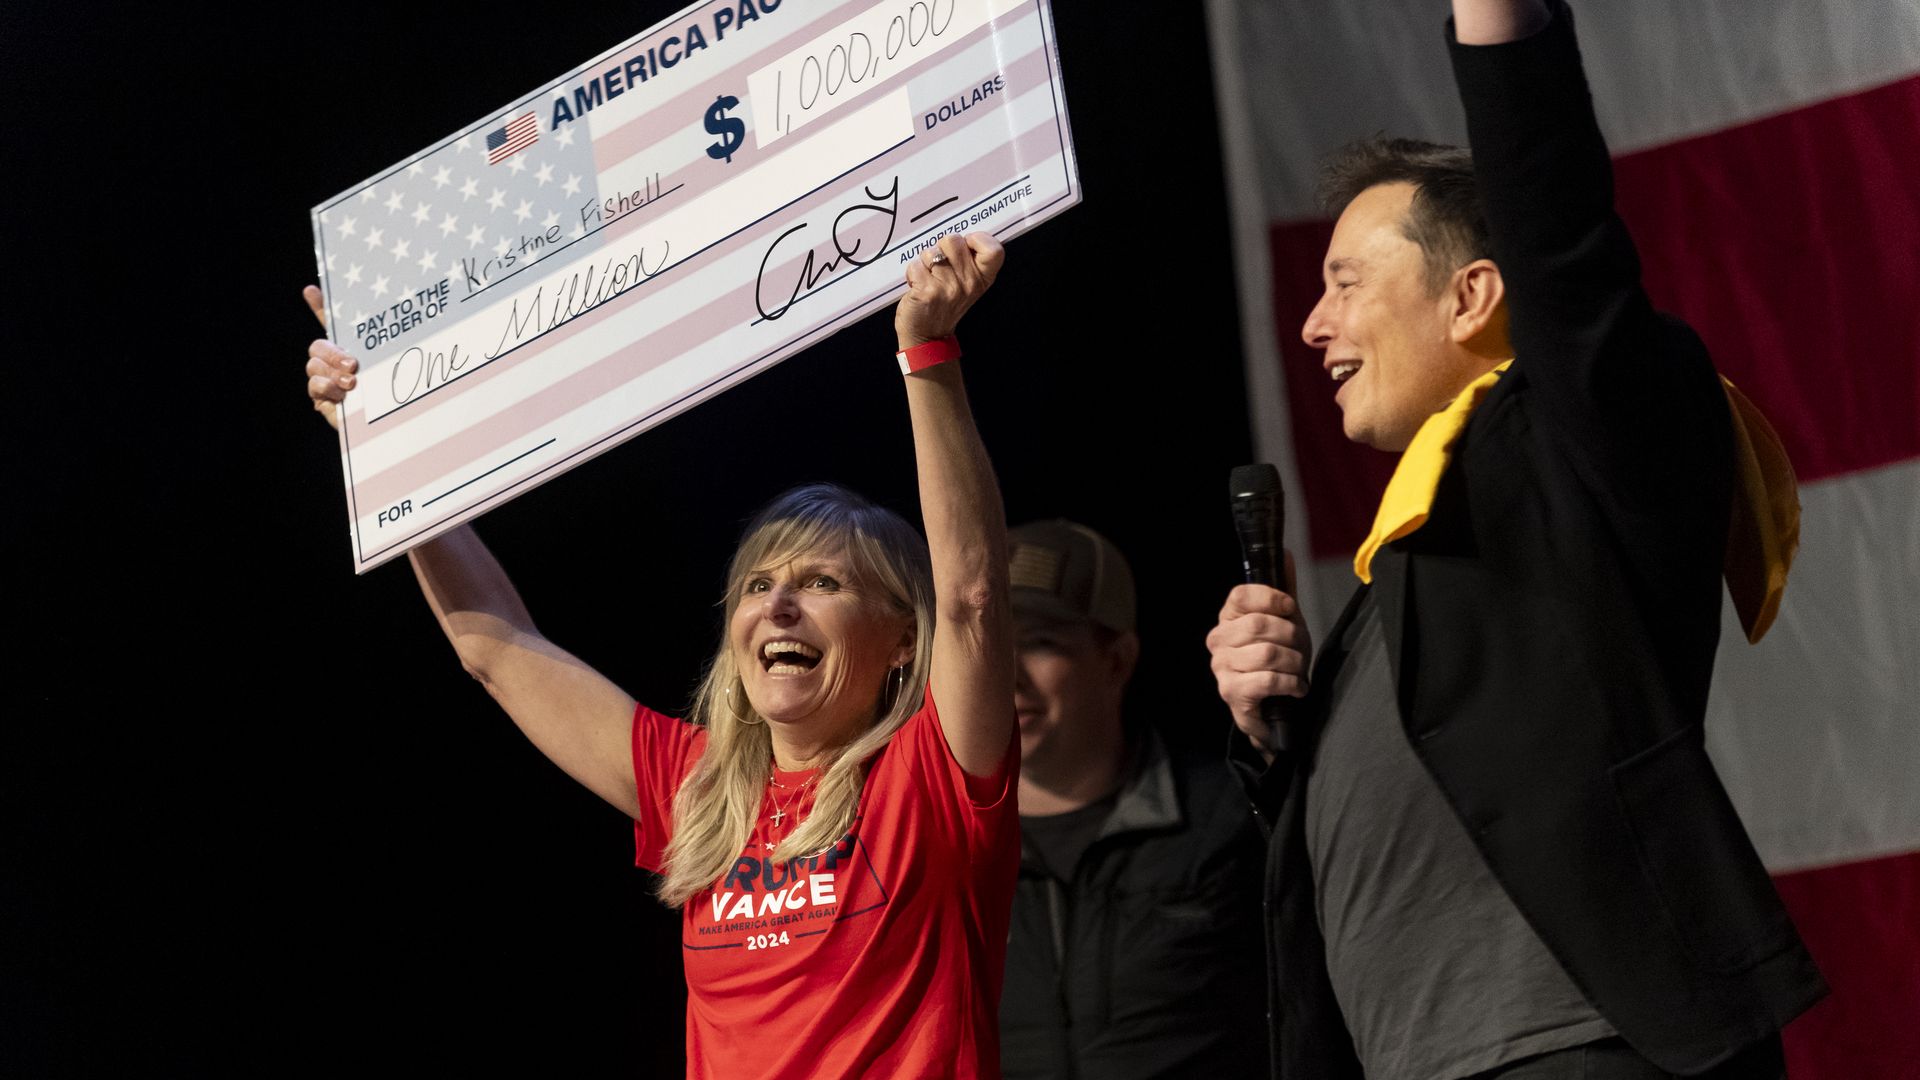
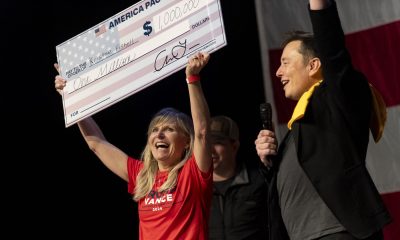
The world’s richest person, Elon Musk, has donated $276 million over the past three months to political action committees and conservative organizations supporting Republicans ahead of the upcoming US midterm elections.
The latest transfer brings the total midterm donations from Musk, the chief executive of Tesla and SpaceX, to $366 million.
First reported by The New York Times, the figures were confirmed to The Hill by a spokesperson for America PAC, which Musk founded. These latest expenditures establish Musk as the largest known donor of the 2026 midterms.
The bulk of Musk’s financial backing between July and September was directed towards congressional races.
The US billionaire transferred $158 million to the Senate Leadership Fund, a super PAC supporting Republican Senate candidates, and $20 million to the Congressional Leadership Fund, which finances House Republicans.
Millions divided among various committees
Musk, who provided more than $76 million during the period to America PAC, an entity he founded during the 2024 election cycle, also funded state-level contests.
The businessman transferred $10 million to the Lone Star Liberty PAC, which supports Texas Republican Senate candidate Ken Paxton, while donating $10 million to the Republican Governors Association and $2 million to the Republican Attorneys General Association.
In statements given to The New York Times and confirmed by The Hill, America PAC spokesperson Andrew Romeo argued that if Democrats take control in Washington and win critical state races, the country faces the risk of becoming one with indefensible borders.
Romeo said the investments enable the Republican apparatus to deliver its messages to voters.
Field spending continues despite talk of retreat
Musk, who kept his distance from politics for many years, entered the arena by spending hundreds of millions of dollars for Donald Trump during the 2024 election.
Accompanying Trump on campaign trails, Musk subsequently took charge of the Department of Government Efficiency (DOGE), which sparked controversy through federal employment and budget cuts.
Musk stepped down from his White House role in late May 2025 and remained politically quiet for months following a public rift with Trump.
After announcing last May that he would sharply scale back his political spending, Musk told The Economist in a July interview that he had become overly involved in politics and had gone too far.
Despite those remarks, Musk pressed ahead with political activity in July by authorizing America PAC to spend between $100 million and $120 million on a fresh field operation aimed at driving conservative voter turnout in the 2026 midterms.
Having repaired ties with Trump following their public spat, Musk joined the US president on an official visit to China in May and was also present during Chinese President Xi Jinping’s visit to Washington last month.

Ex-BND head Hanning tied to former Mossad chief amid spy inquiry

Iran war costs US economy $265 billion as household burden mounts

Trump dismisses US envoy to Greece Kimberly Guilfoyle

Most EU citizens reject fast-track Ukraine accession, poll finds

Ex-US official says air defences fail against Yemeni airport strike
-
 Europe2 weeks ago
German interior ministers drop unanimity rule to counter AfD veto
-
 Europe2 weeks ago
Key European allies excluded from US-led NATO meeting in Poland
-
 Diplomacy2 weeks ago
While the West breeds crises, Eurasia weaves peace and development, says Prof. Zhang Weiwei
-
 Middle East2 weeks ago
Netanyahu holds secret UAE talks with Saudi Arabia and Arab officials
-
 Diplomacy2 weeks ago
The European Union’s peace project has collapsed, MEP von der Schulenburg says
-
 Opinion2 weeks ago
A new world in the East, old dogmas in the West
-
 America2 weeks ago
Musk appointed co-director of Pentagon future warfare initiative
-
 Asia2 weeks ago
South Korea plans $120B spend on eight US nuclear power plants
