Opinion
Obligation for a structural change in Russia: How to exit from the oil-gas economy?


By analyzing the past, present, and future of Russia’s two major export commodities, I will discuss the impacts of the current developments on the budget and the inevitable need for changes in its economic strategy in this article.
First of all, one of the key notions below, “distant nations,” needs some background. Whether or not they are members of the Commonwealth of Independent States (CIS), all former Soviet countries are still regarded as close foreign countries. The rest of the world is likewise distant foreign countries. Here, we only do calculations and charts for distant foreign countries. After leaving China out, European countries constituted its overwhelming majority. Therefore, the conclusion will reflect the impacts of Western sanctions on Russia’s two primary exports and sources of budgetary income (oil and natural gas).
Let me state something upfront for the sake of the reader who is not a fan of lengthy writings. Using 2021 as a baseline, Russia will lose 35% – 40% of its oil and petroleum product exports and 50% of its natural gas exports this year. However, this is only part of Russia’s financial setback. Before the onset of the deep crisis in the first half of 2022, rising energy prices had significantly boosted the country’s income. However, the situation has now reversed, with oil and petroleum products discounted by nearly half their market price.
Natural gas
We’ll begin by explaining how the graph below was drawn, which data was utilized how and why, and how estimations were made.

In order to avoid “misjudgments, speculations, and inconsistencies,” the Federal Customs Administration (FCA) has not released information since April. Hence there is currently no official data for 2022. Gas exports to Europe (in transit via Ukraine) are projected to reach 30 bcm in 2023. At 80% capacity, gas is plummeted through Blue Stream, which equals a maximum of 16 bcm through this line. The largest volume that can be plummeted to China is between 23 and 24 bcm.
It was not disclosed how much natural gas Turkey purchased from Russia last year. However, on July 18, Yuri Ushakov, an advisor to Putin, reported that 12.8 bcm of gas (7.1 Blue Stream, 5.7 Turk Stream) had plummeted in the year’s first half. In addition, the export amounts to China and Europe (excluding “close countries” like the Baltic) are known. Based on these statistics, I estimated the gas export to Turkey at 21.70 bcm. This figure matches what Kommersant reported to the Turkish Customs Administration: 21.50 bcm.
Data from Gazprom and the FTS do not quite match. Gazprom’s export figures are always greater than FTA’s. This also held true in the year 2021. Novak reported on December 28 that Gazprom had exported 185.1 bcm to distant countries. However, according to FTS, total exports to distant countries were 170 bcm. I derived figures on the graph from Gazprom statistics. Additionally, I referred to the Central Bank’s yearly average natural gas prices. Like the FTA, the Central Bank did not integrate the averages of 2022 and afterward into its statistics. Therefore, I utilized the calculations provided by the RIA based on the ICE data as the average natural gas price in 2022: $1260.8 per mcm.
I picked two sets of prices for 2023. First, the price on December 31, 2022, is $844.3, assuming it remains relatively stable throughout the year. If scenario two plays out, temperatures in Europe will remain above seasonal norms this winter and spring, the wind will continue its record-setting speed, Brussels will strike a long-term oil deal with Qatar, relations with Algeria will improve, and the United States will replace the monopoly profit with reasonable prices. Although not all of them are realistic, I would predict that costs can be cut in half if all take place.
For 2023, I have assumed a decline in exports of 30% and a total decrease to 70-75 bcm. If this occurs, European countries will import more than twice as much natural gas from the United States as they did from Russia this year.
Novak said on December 28 that gas exports totaled 100.9 bcm last year. It is a record low. In 1990, it was 110 bcm. On January 16, Miller reported that 15.5 bcm of gas was sold to China. However, Neftegaz announced on January 2 that this figure might be appraised as 18.2 bcm due to an increase in contractual obligations. The graph relies on this second figure.
Miller also said annual gas shipments to China will reach 48 bcm by 2025. But the graph shows that even in this case, the demand from the East cannot make up for the European market loss (at least for now).
I have omitted liquefied natural gas (LNG) from the charts. This export may increase partially. Nearly 16 million tons of LNG were sent to Asia in 2022, and Europe received 15.7 million tons in total. This amount is approximately equal to 44 bcm of gas. Although this figure is not inconsequential, it is not anticipated to increase beyond this level in 2023 owing to the challenges of insurance-reinsurance in transport and tankers other than dependency on Western technology. Furthermore, it is unlikely that the rise in LNG exports would come close to replacing the 180-200 bcm of the potential capacity of the Russia-Europe pipelines before NATO destroyed Nord Stream 1 and 2.
Even by an optimistic prediction, the total demand of China, Belarus, and Turkey in 2023 would only amount to 60 bcm, less than a quarter of Gazprom’s entire supply capacity. So, this is the picture based on the most optimistic estimates: In 2021, Russia globally sold almost 240 bcm of natural gas. By 2023, however, it will only be able to ship a maximum of 45 bcm LNG and export 30 bcm via pipeline to “unfriendly” countries and 60 bcm to neutral countries.
Oil
Let’s look at oil.
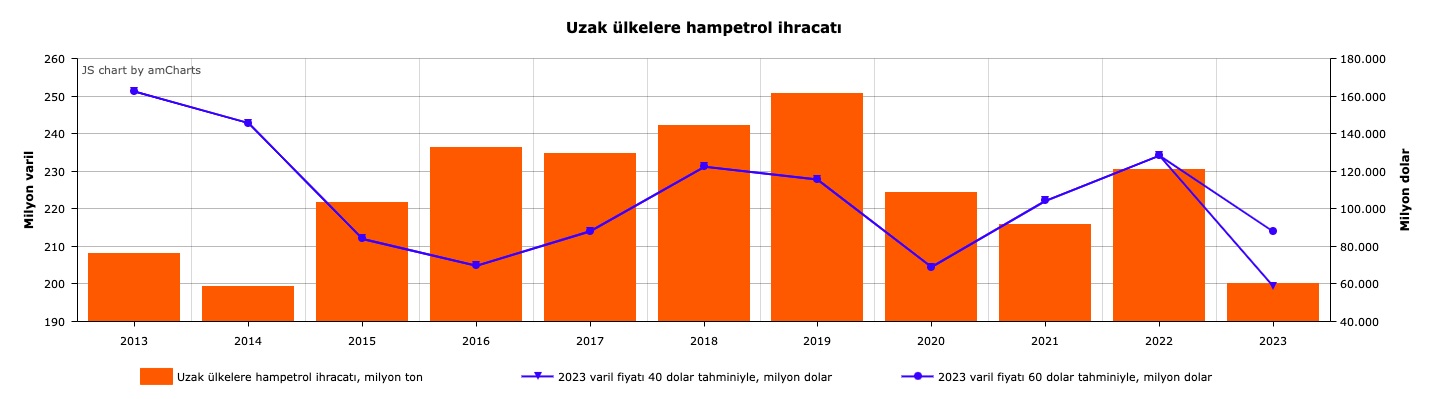
I will prepare the chart for the same time frame (2013-2023); however, I will be excluding the data from China, Turkey, and India. For these three reasons:
1) There are gaps in the dataset. On the bright side, it is at least evident that China had been a reliable purchaser (between 70-72 million tons) until 2022.
2) At least as of 2020, Turkish and Russian sources contradict in terms of figures for Turkey’s purchases.
3) Prior to 2022, India was not a huge market for Russian exports, but after that year, it became one of the most important hubs for Russian oil. The share of Russian oil export to India rocketed from 1% on February 24 to 18% in May. India, Turkey, Singapore, and even the United Arab Emirates (UAE) dilute Russian oil before being sold to obfuscate its origin. It is unclear, however, how they would act after Russia’s counter-sanctions go into effect on February 1. Thus, qualifying the data of these three countries will not provide useful insights.
Nevertheless, we may get insights from the figures of crude oil exports and the total income of the annual average oil price.
Like natural gas, I have completed the chart relying on the data of “distant countries” and my own estimates. Similar to natural gas, I predicted a range of $40 to $60 for the barrel price of Ural oil in 2023. These predictions align with the scenarios the Central Bank announced in May. Considering the $60 maximum price, the likely range for the price of Ural oil is between these two extremes. To “distant countries,” I projected 200 million tons of oil exports in 2023. As a result, Russia will lose 90% of its crude oil exports to Europe due to the sanctions, which may cost the country $40 to $70 billion.
I will not go into technical details of the implementation of the sanctions and embargo. Still, it’s important to know that in its broadest sense (including both land and sea traffic), it will be implemented over the course of 6-8 months. This is why the European market has not been totally lost: Bruegel, a European think tank, has shown that 75% of Russia’s oil and petroleum product exports to Europe are sent offshore, while just 25% are transported via pipeline. Germany and Poland, two main consumers, have reduced their purchases, while the Hungarian government has blocked a full ban. Orbán has ensured that the oil pipelines of Slovakia and the Czech Republic from Russia, in addition to those of Hungary, will remain open.
However, the insurance and reinsurance restrictions directly impact exports to India and China. Unless a stable solution to this issue is found (a partial solution is already available; the Russian National Reinsurance Company carries out the reinsurance), overall exports may fall further. Similar to natural gas, compensating the European market with Asia cannot happen in one day.
My estimations for potential losses are in line with these predictions as well. AlfaBank reported an expected loss of $50 billion; for Reuters, it is $40 billion to $54 billion, and for Energy Aspects, $60 billion. Increasing the amount of oil exported may improve the situation, which is feasible if the methods to circumvent the sanctions are broadened. A significant increase in the $40-$60 range for the sale of Ural oil appears unlikely.
These two charts depict a very critical scenario for 2023: Excluding petroleum products and LNG, we may expect Russia’s oil and natural gas income to be between $89.3 and $149.4 billion. This means a revenue drop of between $106 and $166 billion compared to the previous year.
Budget
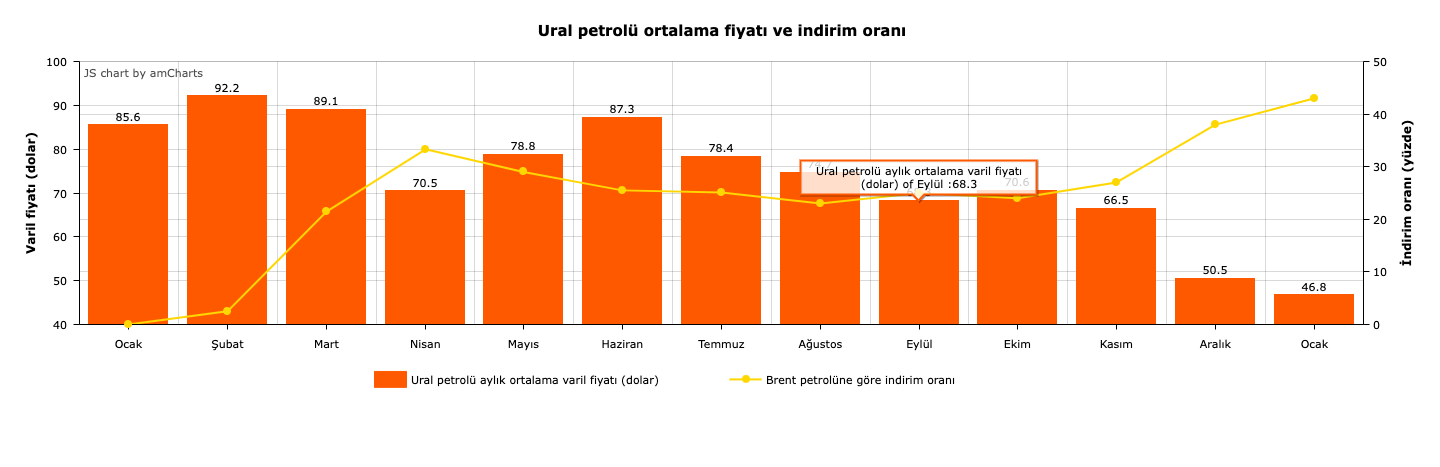
Budget revenues determined by the 2022 budget law were 25 trillion rubles, but roughly extra 2.5 trillion rubles actually went into the treasury last year. Yet budget expenditures were above this increase; during the year-end press conference, Finance Minister Siluanov said that “around 30 trillion rubles” had been spent. Despite a significant discount in Ural oil (shown in the third chart), oil prices were much higher than in the previous year, and natural gas revenues were at a record level until December 5. And these are the reasons for the increase in income. The greater rise in expense was owing to, in addition to the direct (military expenditures) effect of the Ukrainian operation, the increase in government subsidies to belligerent individuals and their families, and most usually low-income people. The budget, traditionally having a surplus, ran a deficit for the first time in April and was covered for the rest of the year by Gazprom and Rosneft.

The Ministry of Finance had predicted that the price of Ural oil per barrel would be $70.1 in 2023, $67.5 in 2024, and $65.25 in 2025. However, at least for this year, it is quite unlikely that the forecast will come true. In any case, Ural oil was nearly always sold at a discount, but the price difference was generally little more than a few dollars. However, huge price differences appeared after February 24, and the average discount is roughly 30 percent from that date to the end of the year. The discount rate was relatively stable between July and October at about 20-25 percent, but it spiked sharply once the maximum price was published on December 5. Since December 30, it has fluctuated daily between 45-55% as of January 20. In addition, it is still cheaper than $60, the price cap. In contrast, the last year’s price average of Ural oil was $76.09.
The situation with natural gas is similar. According to the explanatory note in the draft budget for 2023–2025 and the official forecast for the 2024–2025 planning period, natural gas exports (total of distant and close countries) fell by 31% in 2023 compared to the previous year, landing at 142 bcm, and will average 125 bcm annually for the next two years. However, these figures should be considered too optimistic because total exports via pipelines may decrease to 90–93 bcm this year if natural gas exports to distant countries reach 70–75 bcm as expected.
According to the most reasonable estimates of the Ministry of Finance, in 2023, if the price of Ural oil per barrel stays at $50 and daily output does not surpass 10 million barrels, the government would get at least $2.1 trillion less in oil and gas revenue in 2023, and the deficit will rise to $5 trillion, instead of the anticipated $2.9 trillion (2 percent of GDP). (In addition to crude oil, other petroleum products, natural gas, coal, etc., will impact this deficit.)
Suppose Ural oil prices remain at about $62-$63 per barrel. In that case, the Ministry of Finance intends to sell yuan from the National Wealth Fund and issue bonds to cover the deficit without raising the tax burden on the bourgeoisie. Alternatively, the government decides to seize “excessive profit” on carbon and fertilizer (this is the Kremlin’s optimal solution; I looked into it further when analyzing Putin’s September 7 speech at the Eastern Economic Forum), to increase the share of the budget in the dividends of state companies (this is the “financial bloc’s” optimal solution), and to issue a new tax regulation, if it fails, or the discounted oil price drops further. The Kremlin sees raising the tax burden on the great bourgeoisie as the best way to ensure that the welfare of the people remains stable or, if feasible, is elevated by state aid. In contrast, the “fiscal bloc” would rather burden the public by increasing indirect taxes. In other words, the bourgeoisie or the people must contribute to cover the budget deficit. As a result, the “conflicting alliance” between “the potent and the impotent” continues.
Conclusion
These are, of course, just estimates anyway. But one thing is clear enough: The traditional economic paradigm (oil and gas economies) is rapidly becoming obsolete. A structural shift in the economy is inevitable. This can be done in two ways: Medium and large private capital shifts from unproductive trade or the production of raw materials for export to industrial output for the domestic market, or the state expands its role as an economic regulator.
While the first way may help in the consolidation of capitalism but given the comprador nature of private capital in Russia, it is unrealistic to assume that it will serve as the primary means. It will continue to be an alternative for the bourgeoisie is eager to fill in the lacuna created by the foreign money leaving Russia. The local bourgeoisie is flexing its muscles to seize closed and closing foreign financial and industrial institutions, so one of the reasons why the ruble has depreciated in the past month is the demand for foreign currencies for purchases. Yet, the comprador nature of capital still prevails. In the first three quarters of last year, the financial-bloc-backed bourgeoisie managed to invest abroad 2.5 trillion rubles, or 10 percent of the budget’s income. On the other hand, taking the first way for structural shift results in the bourgeoisie’s political power being consolidated and empowered, posing a challenge to Bonapartism. Finally, the greatest exporter of raw materials, the state sees no gain in income through the first way, exacerbating the structural problem. Thus, the state must serve as the driving force of structural change.







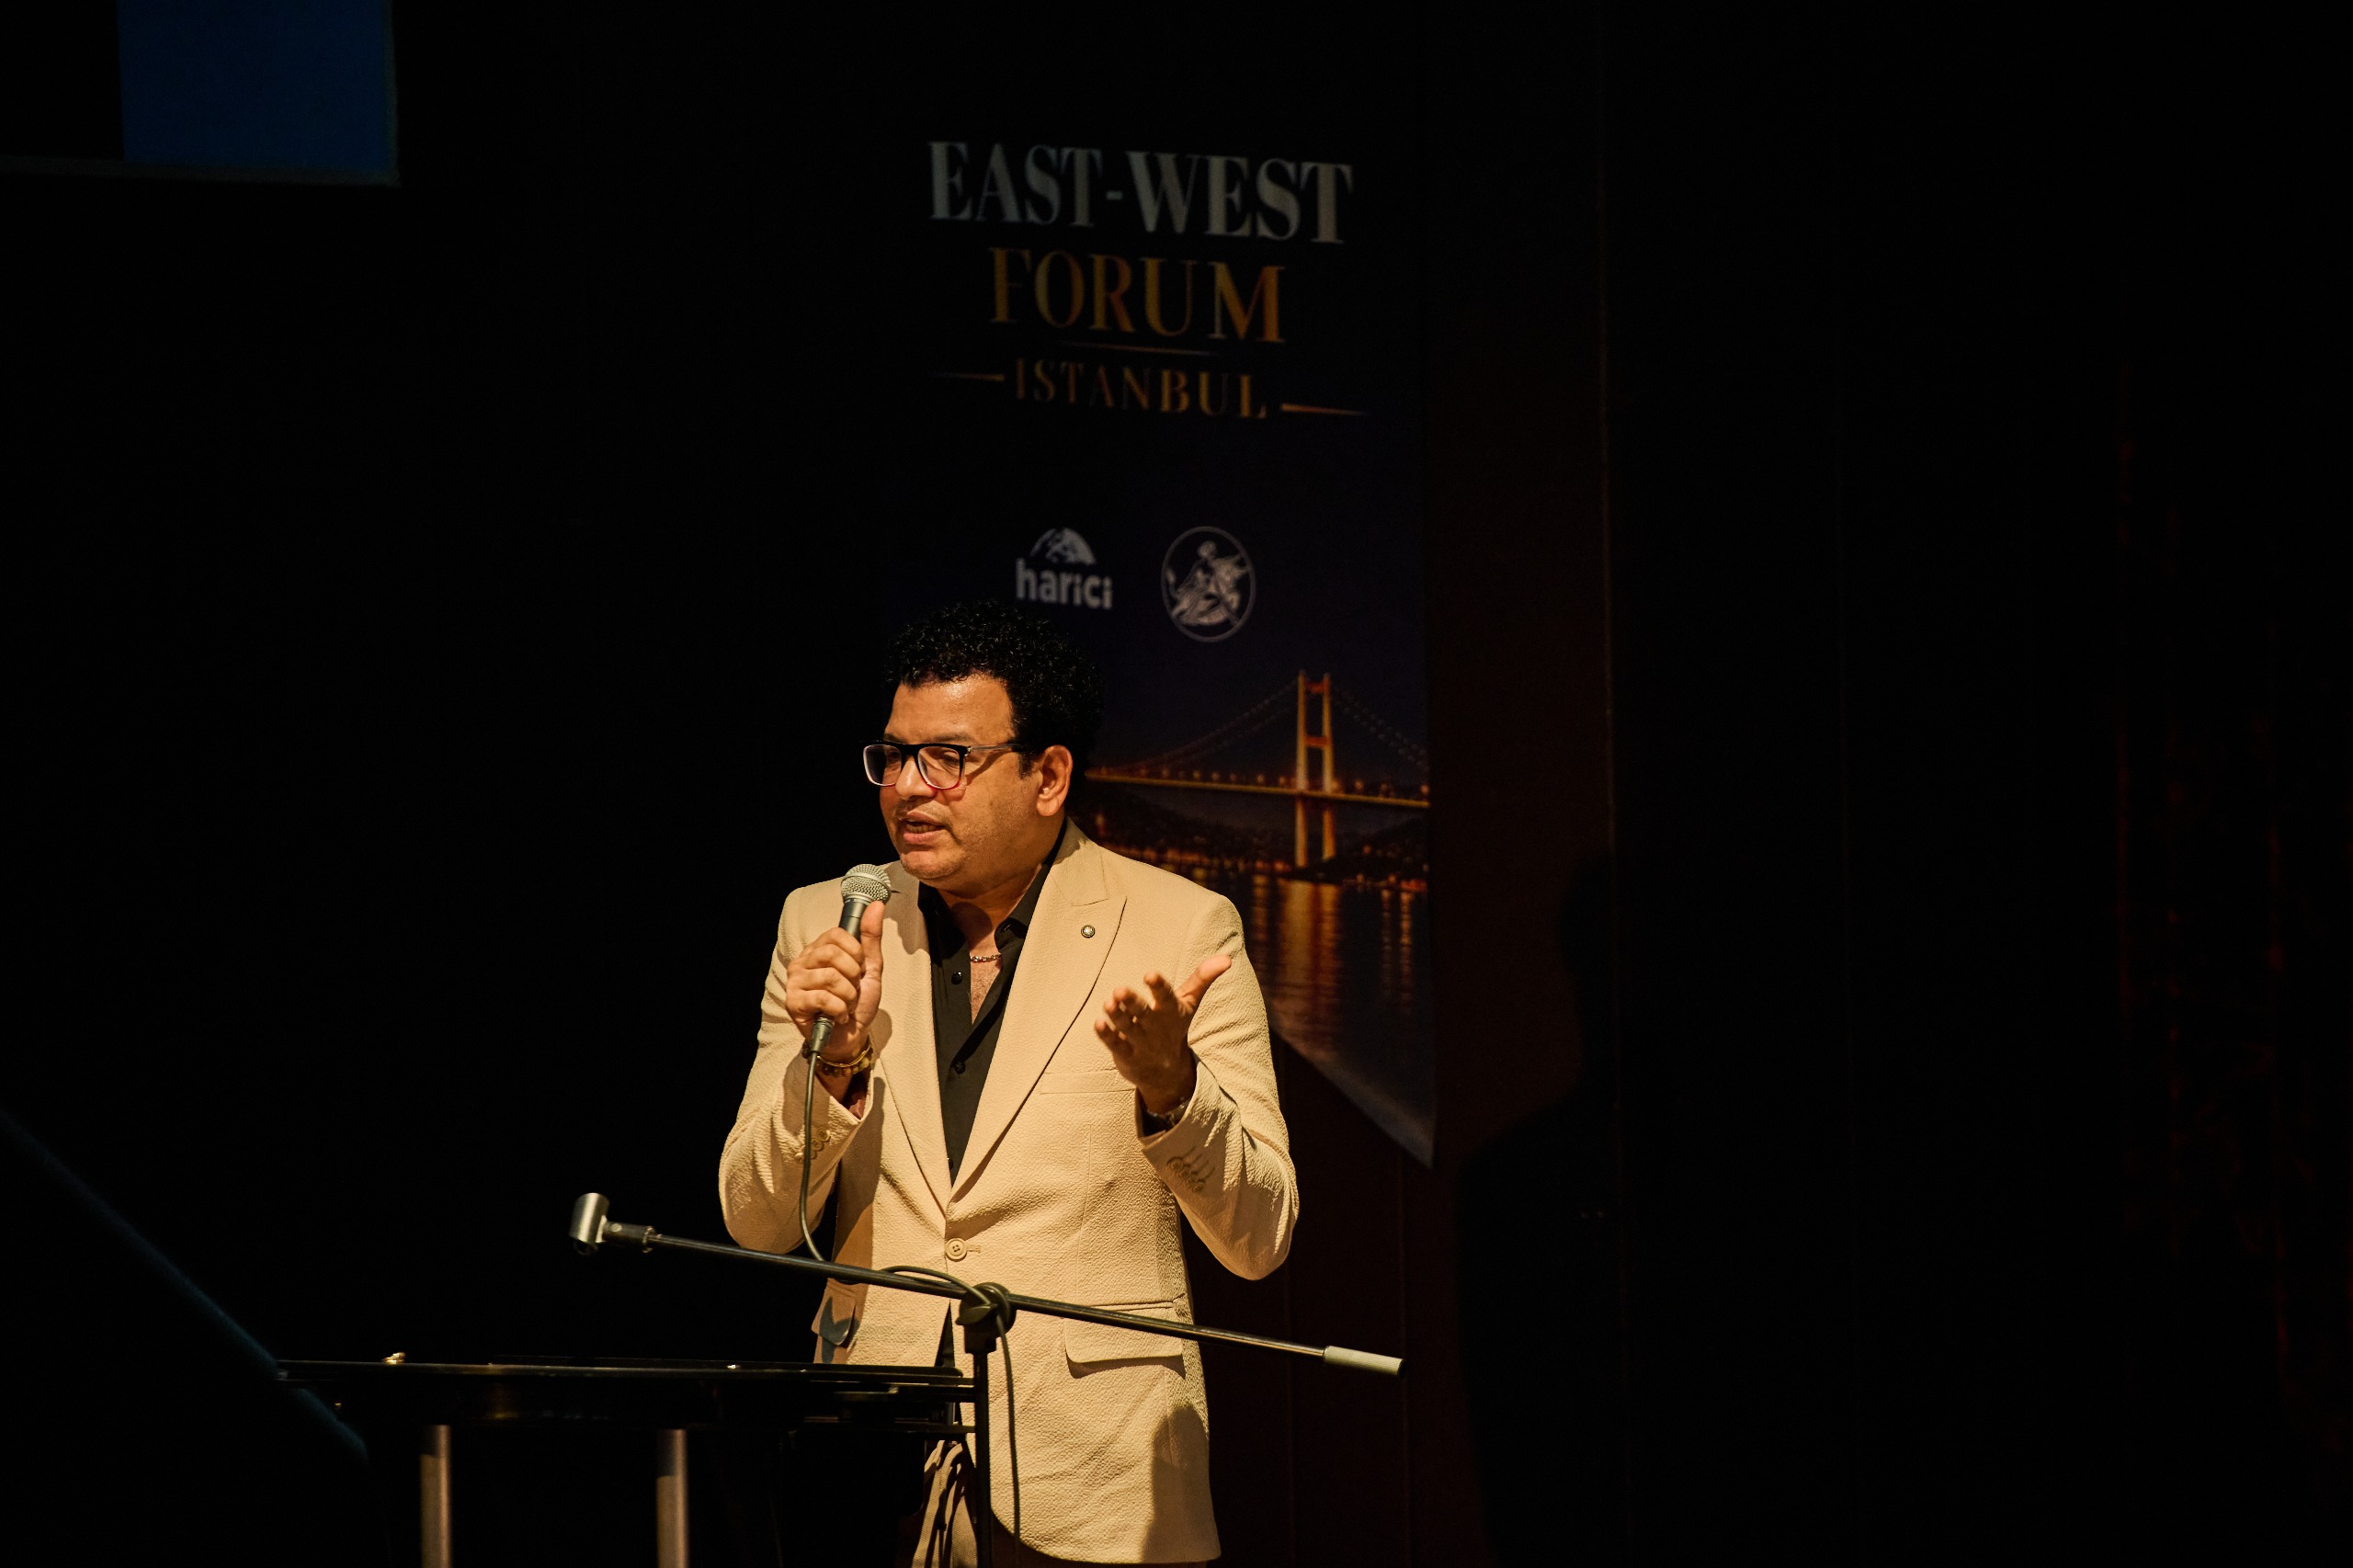
Dr. Ahmed Moustafa, Director & Founder, Asia Center for Studies & Translation, Egypt
In a city that has spent centuries translating the language of one civilization to another, the first East-West Forum arrived at a moment when the world itself seemed to have lost the vocabulary for talking across its divisions.
Held in Istanbul on Sept. 26–27 and preceded by meetings around the event, the forum brought together diplomats, academics, journalists, strategists and political thinkers from a wide range of countries. Hosted by Harici Media in partnership with the Berlin-based European Transcontinental Initiative, the gathering was conceived as an attempt to examine a world increasingly defined by competing power centers, regional wars, economic fragmentation, artificial intelligence and the erosion of confidence in institutions created after the Second World War. Harici reported that participants came from roughly 30 countries.
For us, the significance of Istanbul was not simply a matter of the speakers on the panel or the structure of the programme. Its deeper importance lay in the willingness to put difficult — and sometimes uncomfortable — questions on the table.
We would like to extend our sincere thanks and appreciation to my friend and brother, Mr. Tunç Akkoç, Founder and Editor-in-Chief of Harici Media, for his gracious invitation to a representative of the Asia Center for Studies & Translation, Egypt, to participate in the Forum as a speaker and commentator. His initiative in creating a platform where competing geopolitical narratives could meet directly deserves recognition.
In his opening remarks, Akkos stressed that the initiative was intended to establish a permanent platform where people representing different political and intellectual traditions and perspectives could meet and engage in direct dialogue.
This vision is particularly significant because the traditional language used in international relations has increasingly struggled to explain the realities of a rapidly changing world.
The Problem of Proxy Wars
During the session that discussed proxy wars in the region and ways to reach solutions to their crises, the Center put forward the view that the Middle East cannot simply be understood through the traditional map that divides the parties into “good” and “evil,” or into “responsible states” and “rogue states.”
Such terms, in our assessment, often reflect the perspective of powers that possess extensive influence over international media and financial and security institutions.
The Center particularly criticised what we see as political bias within important sectors of the Western media and some non-governmental organisations that receive Western funding. From our perspective, these institutions can, in some cases, move from being mere observers of geopolitical conflicts to becoming influential parties in the battle over the narrative and the story.
However, this view should remain open to debate and should not automatically be accepted as an absolute truth.
The more important question is not whether every Western journalist, every NGO, or every Western institution works to serve a single geopolitical agenda clearly, this is not the case, but whether the information environment itself has become so highly polarised that the public is now receiving radically different interpretations of the very same war.
In our assessment, the answer is increasingly approaching “yes.”
The problem becomes particularly clear when searching for the term “proxy wars” in the Middle East. Some of the first results focus on groups associated with Iran, including Hezbollah and the Houthis, as well as Hamas, whereas the history of regional conflicts is far more complex.
Al-Qaeda and ISIS emerged through different historical trajectories, with Anglo-Saxon support that was “created by Britain and the United States.” In environments dominated by the United States and Britain, Al-Qaeda emerged from the environment associated with Osama bin Laden and the Afghan jihad, while ISIS developed largely from Al-Qaeda in Iraq, under American sponsorship, to pursue a certain agenda in the region and advance the scenario of “creative chaos” promoted by Condoleezza Rice, the radical US Secretary of State.
At the same time, US policy toward Afghanistan during the Cold War contributed to shaping the broader environment from which some militant jihadist movements later emerged.
These distinctions matter.
Because propaganda often begins where complex historical details end.
Who Has the Right to Define a “Rogue State”?
The same problem appears in the vocabulary used to describe states.
Countries such as China, Russia, Iran and North Korea are frequently portrayed in Western strategic discourse as states challenging the existing international order.
Egypt, despite the different nature of its relationship with Washington, can also become the subject of criticism when its foreign policy does not conform to certain Western expectations.
The question is not whether these governments should be exempt from criticism. Of course not.
The deeper question is this: can the international system remain sustainable when one geopolitical camp increasingly assumes the authority to define which governments are legitimate, which movements are terrorist, which wars are defensive and which forms of resistance are acceptable?
That was one of the central questions behind our intervention in Istanbul.
The Middle East has repeatedly been presented through the lens of the “Iranian threat” as the principal strategic danger.
There is no question that Iran possesses significant military and regional capabilities, and that its policies are deeply contested by many neighbouring states. At the same time, reducing virtually every regional security problem to Tehran can obscure the interests and roles of other actors, including Israel, the United States, Gulf states, armed groups and local political forces.
The region has repeatedly paid a heavy price for simplistic interpretations of complex conflicts.
The Economics of Fear
The discussions in Istanbul also led us to a broader American question: to what extent can fear itself become a source of political and economic power?
Historically, the United States has experienced intense political campaigns shaped by perceived racial, ideological and security threats.
One does not need to accept every interpretation of this history to recognise that fear can become a factor with tangible economic consequences.
A 2020 study by Citi estimated that racial discrimination against Black Americans had cost the US economy approximately $16 trillion in lost economic output since 2000, based on an analysis of disparities in wages, education, housing and investment.
This figure demonstrates the extent of the economic losses associated with racial discrimination and exclusion. It also raises questions about the relationship between fear-based narratives concerning Black Americans, media influence, the political power of the gun lobby and the broader economic consequences of insecurity.
More importantly, however, the study highlights a fundamental point: bias and insecurity carry substantial and measurable economic costs.
The broader lesson has direct relevance to foreign policy.
When societies are continually presented with existential enemies, military spending and the expansion of security institutions become politically easier to justify.
America After Iran
In Istanbul, we also advanced the view that the United States after its confrontation with Iran in 2026 should not simply be understood through the traditional image of unlimited American power.
The conflict exposed economic and strategic vulnerabilities.
The Strait of Hormuz emerged as a major strategic pressure point for global energy markets, amid disruptions to international trade that forced governments and companies to search for alternative routes and supplies.
The consequences were reflected in oil prices and energy costs in Europe and elsewhere.
This does not mean that American power has disappeared. Rather, it suggests that military power is no longer synonymous with strategic control.
The rise of China, Russia, ASEAN, Iran and other centres of economic and diplomatic influence has made the international order increasingly complex and dispersed.
The East-West Forum itself reflected this reality, bringing together voices from Europe, Asia, the Middle East and North America while explicitly addressing multipolarity and the ongoing transformation of the global order.
America Is Changing From Within
The domestic dimension of American politics also deserves attention.
The emergence of figures such as Zohran Mamdani in New York and Abdul El-Sayed in Michigan reflects changes in the American political debate over inequality, foreign policy, healthcare, identity and the influence of established political and economic interests.
Their political trajectories should not be treated as evidence of a predetermined future for the United States.
They do, however, illustrate how issues that were once treated as peripheral including the costs of war, US policy toward Israel, economic inequality and the political influence of younger and more diverse generations have moved closer to the centre of American political debate.
This is another reason why East-West dialogue cannot remain confined to foreign ministries and military institutions.
A Dinner for Dialogue
One of the most memorable moments on the margins of the Forum was the private dinner held on the evening of Friday, September 25, hosted by H.E. Mr. Hasan Capan, Chairman of the Turkish-Chinese Friendship Foundation, and H.E. Ambassador Ersin Erçin, Vice Chairman of the Foundation, in honour of the speakers and participants.
We extend our sincere thanks and appreciation to both of them for their generosity, friendship and support.
The gathering was more than simply a dinner. It provided an opportunity for personal interaction, an exchange of ideas and the building of relationships among participants — precisely the kind of human diplomacy that formal conferences sometimes lack.
Real dialogue does not always begin behind conference podiums.
Very often, it begins around a single table.
Istanbul’s Larger Message
The first East-West Forum should be regarded as the beginning of a dialogue, not the end of a debate.
The organisers have already articulated a vision of transforming the initiative into an annual gathering in Istanbul, developing expert working groups, establishing an East-West Forum network and potentially creating a business council capable of connecting intellectual dialogue with economic cooperation.
This may ultimately prove to be one of its most important contributions.
The world that emerges from the current conflicts including the crisis surrounding the Strait of Hormuz will require more than ceasefire agreements.
It will require a new conversation about security, energy, sovereignty, development, technology and coexistence.
Istanbul is an exceptional setting for such a dialogue. One participant even proposed moving the headquarters of international organisations, including the United Nations, to Istanbul.
For centuries, the city has stood between two continents without belonging exclusively to either.
The East-West Forum can follow the same principle: not choosing one civilisation against another, but creating a space in which East and West can confront their differences without turning disagreement into permanent conflict.
For this reason, we see the Istanbul gathering as an announcement of intent.
It was not an attempt to erase differences.
It was an attempt to make dialogue possible despite them.
At a time when proxy conflicts increasingly risk evolving into direct confrontations, this may be among the most important political conversations the world can undertake today.

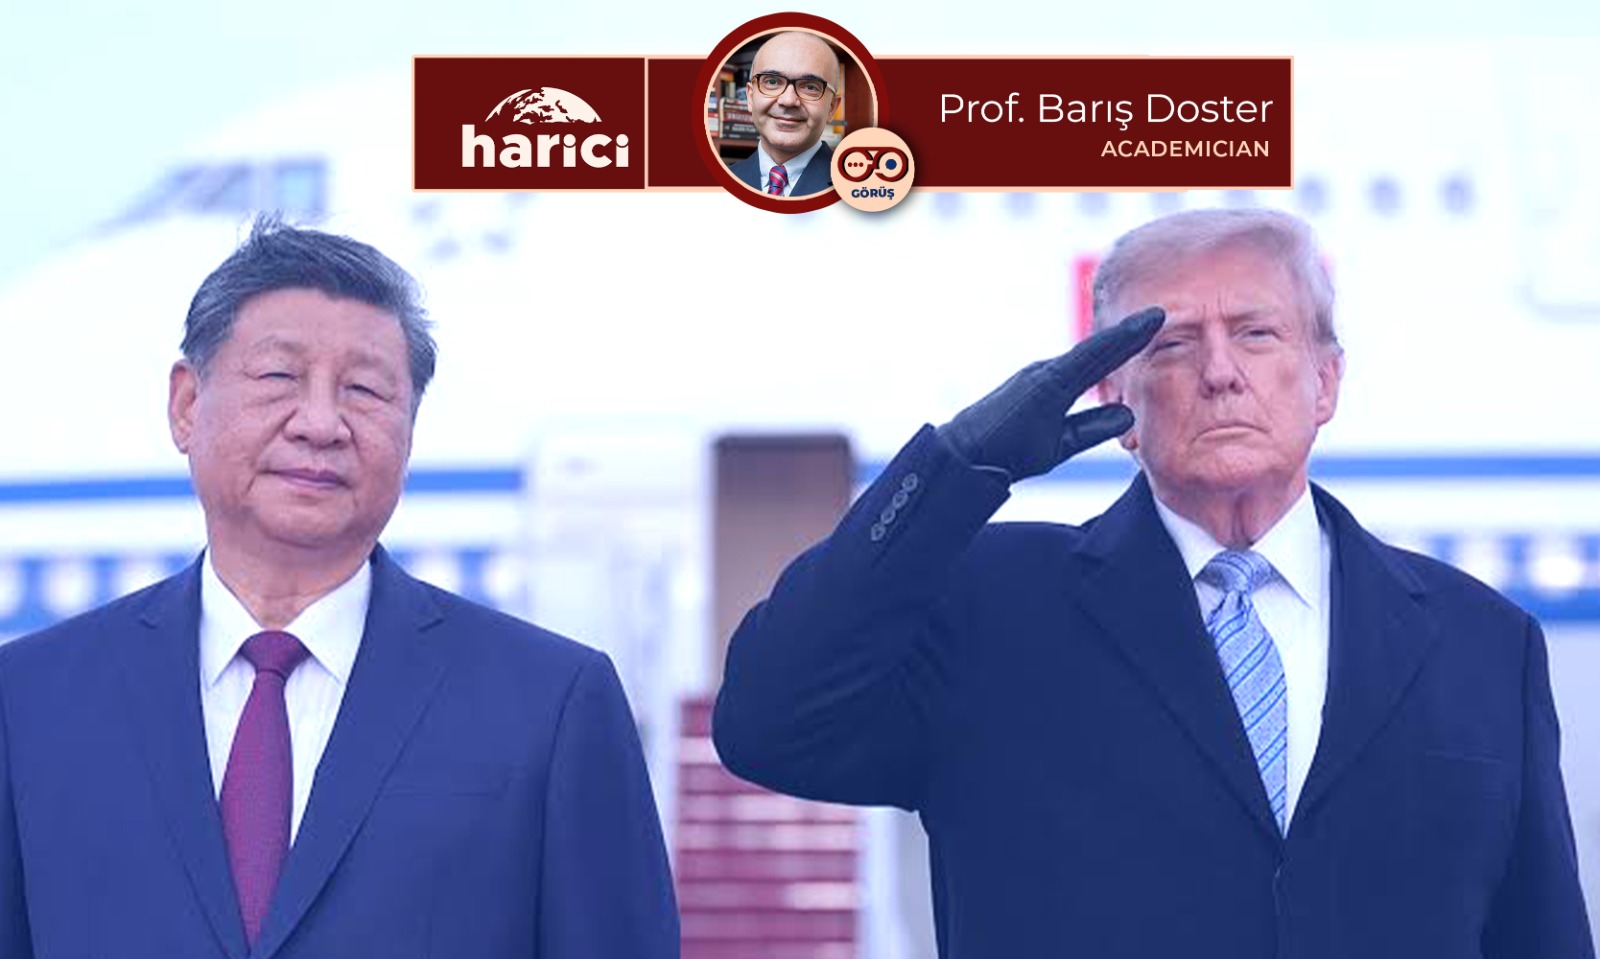
Much commentary followed the US president greeting the visiting Chinese leader at the foot of the aircraft stairs: both because a US president had not done so in many years, and because the leader he welcomed heads a state that the US defines as a competitor, an adversary, and an enemy. That photograph demonstrated that the US itself now recognizes China not merely as an economic power, but as a political, military, scientific, industrial, and technological one; yet it revealed other realities as well.
It showed that a multipolar order has arrived. It showed that the failure of the US to abide by the order whose rules it laid down and whose institutions it established has exacted a heavy toll on the US itself. It showed that the US-centric Atlantic system is unravelling. It showed that the collapse of a world order flouted, and indeed subverted, by its own rule-maker is both legitimate and inevitable. It showed that East-centred institutions, such as the Shanghai Cooperation Organisation and BRICS, enjoy an open path against Western-dominated bodies. It showed that the US regards China as a rival not merely economically, but ideologically and technologically. It showed that the US has proven unable to exercise deterrence against China, Russia, and Iran to the degree it desires.
Let us admit it: after the Cold War ended, the US assumed it could act as it pleased by bringing the European Union to its side and constantly invoking human rights, democracy, and freedom. It was mistaken. The more it spoke of a rules-based world order, of a liberal world order, the more it flouted those very rules. In the end, that order collapsed as well. The birth of a multipolar, multilateral, and multicentric world accelerated; and it was just as well. Now is the time to debate the rules, institutions, traditions, and solutions of this new order.
Yet who will conduct this debate? Who will take part in this search?
It is not right to expect this from the US; nor is it realistic. It is likewise impossible to expect it from the European Union. Europeans follow so subserviently in Washington’s wake that they refuse to consider even Russia as European, despite the fact that, alongside its Eurasian identity, millions of its citizens live across territory spanning Europe and Asia while viewing their nation as historically, politically, socially, culturally, artistically, and intellectually European. They attempt to construct a European defence and security architecture by excluding Russia, in defiance of Russia, and by harbouring hostility toward Russia. In the end, they are both mistaken and defeated.
As the new order emerges, India must also be examined under a distinct heading, alongside China and Russia. For India is a nuclear power possessing the world’s largest population and its 5th largest economy. It maintains disputes with China and Pakistan, yet enjoys good relations with Russia, the US, and Britain. It is a member of both the SCO and BRICS. On the other hand, within the Quad grouping, alongside the US, Japan, and Australia, it positions itself against China.
In summary, as an order takes shape in which the West runs out of breath while the East rises, and Atlantic institutions dissolve while those of Eurasia and the broader Global South come to the fore, we must first rid ourselves of Cold War dogmas and habits.
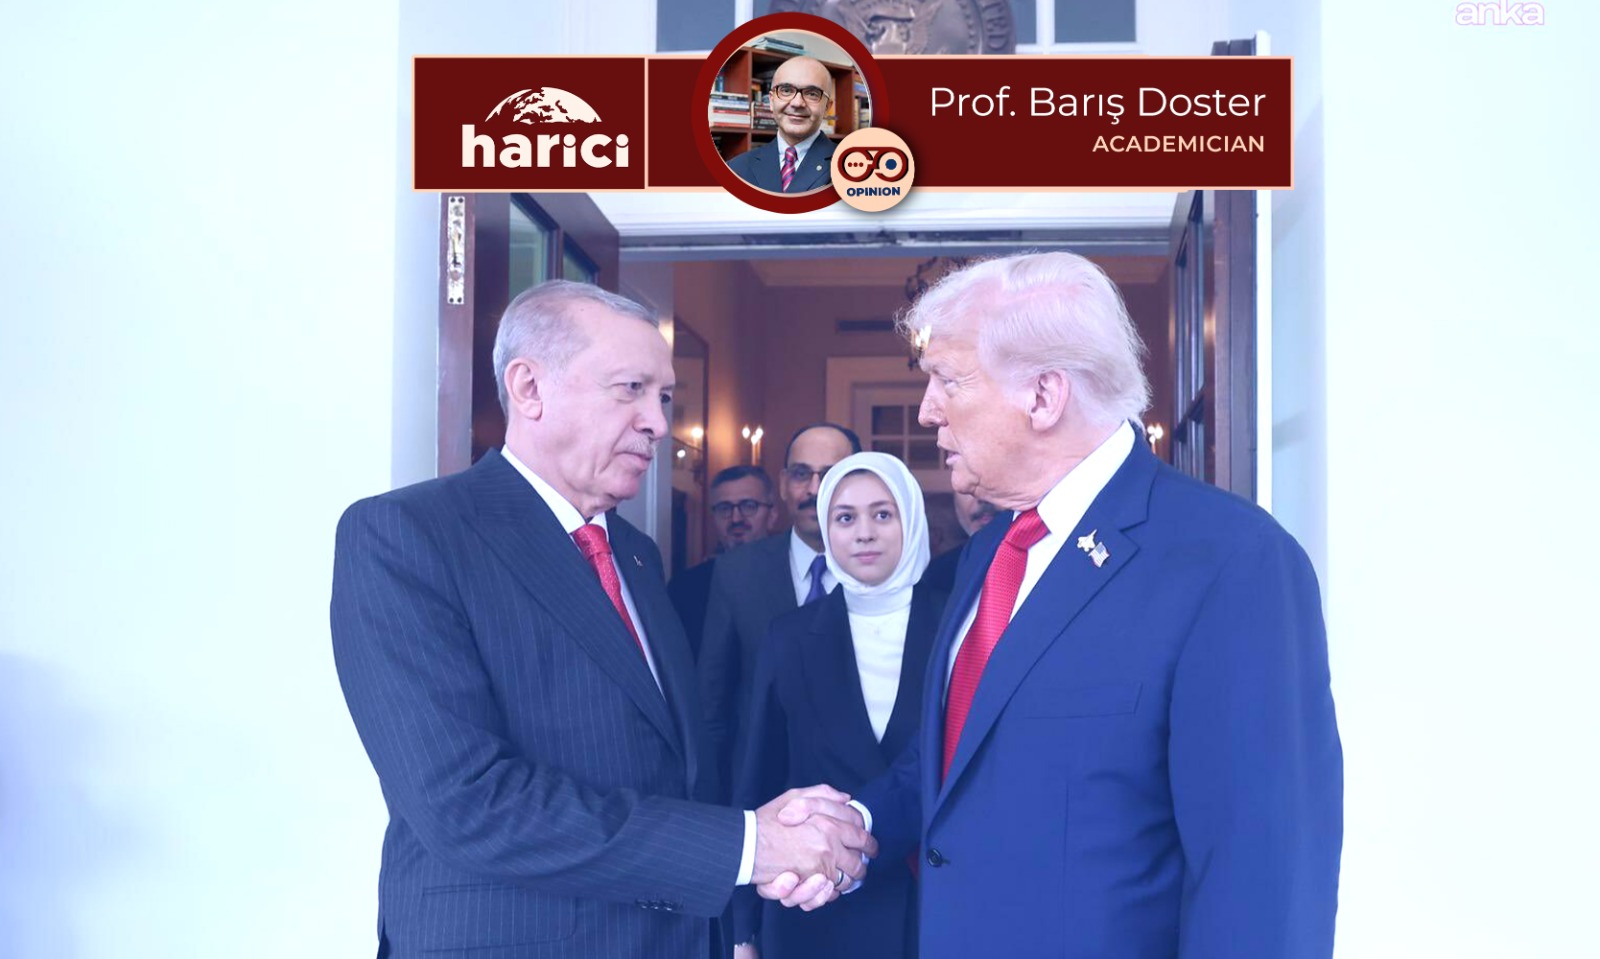
At the NATO summit held in Ankara last month, US President Donald Trump made promising remarks to Türkiye regarding the lifting of CAATSA sanctions, clearing the path for the sale of F-35 fighter jets to Türkiye, and supplying the engines required for the domestic Kaan aircraft. He has yet to keep his word.
This is quintessential Trump. He is neither a reliable nor a predictable leader. He approaches diplomacy like a merchant. In bargaining, he opens with the highest possible bid. Rather than institutional consultations, negotiations, formal diplomatic channels, and classical statecraft, he favours personal ties, bilateral encounters, and leader-to-leader diplomacy. He is notoriously erratic. A figure he praises one day, he drags through the mud the next, humiliating, scolding, and even insulting them.
US moves in the Mediterranean
Failing to honour the promises made to Türkiye, the US eased and partially lifted the arms embargo it had enforced on the Greek Cypriot Administration (GCA) since 1987 in 2020, before abolishing it entirely in 2022. Not content with this, the US signed a military cooperation agreement with the GCA in 2024 and hosted its leader at the White House. The GCA, whose path to acquiring weaponry from the US was cleared in 2024, has also recently been deepening its relations with France. Even though two British sovereign bases already exist in the southern part of Cyprus, with the US utilizing them whenever necessary, both the US and France signed separate basing agreements with the GCA. The GCA’s relations with Israel are also remarkably sound, as are those with Qatar. Meanwhile, relations between Greece and France have been exceptionally warm in recent years.
Amid all these tangible developments, Türkiye has largely relinquished its vigilance regarding the Blue Homeland. Drilling vessels and seismic survey ships have been withdrawn from the eastern Mediterranean.
The most distressing of these developments has been that four Turkic states in Central Asia (Kazakhstan, Uzbekistan, Turkmenistan, and Kyrgyzstan), none of which officially recognize the Turkish Republic of Northern Cyprus (TRNC) as a state, expanded their ties with the GCA and opened embassies in exchange for European Union financial assistance. Through this recognition, by acknowledging the Greek Cypriot Administration as the sole representative of the entire island under the name of the Republic of Cyprus, they effectively rejected the existence of the TRNC, whatever they might claim to the contrary.
Whatever anyone may say, and from whichever angle one evaluates it, the conduct of these four friendly and brotherly states cannot be explained merely by their lack of loyalty or their disregard for Türkiye’s sensitivities on this matter. Alongside this, one must acknowledge the failure of Turkish foreign policy. If Türkiye cannot convince even fellow Turkic states, let alone others, on an issue where its position is most legitimate and justified, such as Cyprus; if, far from persuading them, it cannot prevent them from cultivating relations with the GCA and opening embassies, this represents a monumental failure on the part of Turkish foreign policy.
Moreover, the failure in the Mediterranean is not confined to Cyprus. There is more.
Who is sidelining Türkiye in Syria?
Türkiye is persistently excluded from European-organized meetings on Syria. Türkiye’s views are not sought. So much so that even Qatar, our closest ally in the Arab world, on whose soil we established a military base and to whom we sold major assets, does not hesitate to take part in initiatives that exclude Türkiye from energy projects in the Eastern Mediterranean, or to cooperate with Greece and the Greek Cypriot Administration.
Much has changed in Syria since the days when Ahmet Davutoğlu, former prime minister, former foreign minister, former AKP chairman, and leader of the now-dissolved Future Party, carried away by his own momentum, declared: “Not a bird can fly in the Middle East without our knowledge”, “We know the Middle East street by street, inch by inch”, and “We are the masters, pioneers, and spokesmen of the emerging Middle East”, all while eagerly seeking to act as a subcontractor on behalf of the US. The regime has changed. The government has changed.
So let us ask: did we get what we wanted?
Israel, which most recently struck Abu al-Duhur Military Airbase east of Idlib in northern Syria; Israel, a backer of the PKK-PYD-YPG terrorist organization; Israel, which usurped Syrian land in the Golan Heights, attacking Syria and rolling in its tanks whenever it pleases; Israel, which seeks to partition Syria into four entities (Kurdish, Alawite, Arab, and Druze): Israel got what it wanted. And it continues to do so.
Does Israel, which directs scathing rhetoric at Türkiye, fortified by immense US backing and sustained by Europe’s three major powers (Germany, Britain, and France), draw this audacity solely from the imperialist powers standing behind it? Or does Türkiye’s inefficacy in the Turkic world and across the Arab sphere, alongside that backing, also embolden Israel?
In answering this question, we will arrive at a far more accurate assessment if we take into account the depth of Israel’s relations with Azerbaijan.

Germany expands North Sea military ports and plans new naval base

Musk appointed co-director of Pentagon future warfare initiative

US waives human rights terms on $320m military aid to Egypt

Putin says Russia did not start war and warns of nuclear risks

European nations unite against US pressure over strategic oil stocks
-
 Europe5 days ago
European unions urge governments to scrap all Palantir deals
-
 Diplomacy5 days ago
East-West Forum in Istanbul highlights irreversible shift to multipolarity
-
 Europe1 week ago
Emmanuel Todd says West faces collapse amid Ukraine and Iran crises
-
 Europe1 week ago
European intelligence chiefs divide over risk of Russian attack
-
 Diplomacy1 week ago
East-West Forum in Istanbul to debate multipolarity and global order
-
 Middle East1 week ago
Sharaa says 7 October must not shape Israel policy on Syria
-
 America1 week ago
Republican support for Trump’s war with Iran drops sharply in polls
-
 Middle East1 week ago
Palestinian factions confront legitimacy crisis at Istanbul talks
