Europe
UniCredit nears majority voting control of Commerzbank, signaling major European banking consolidation

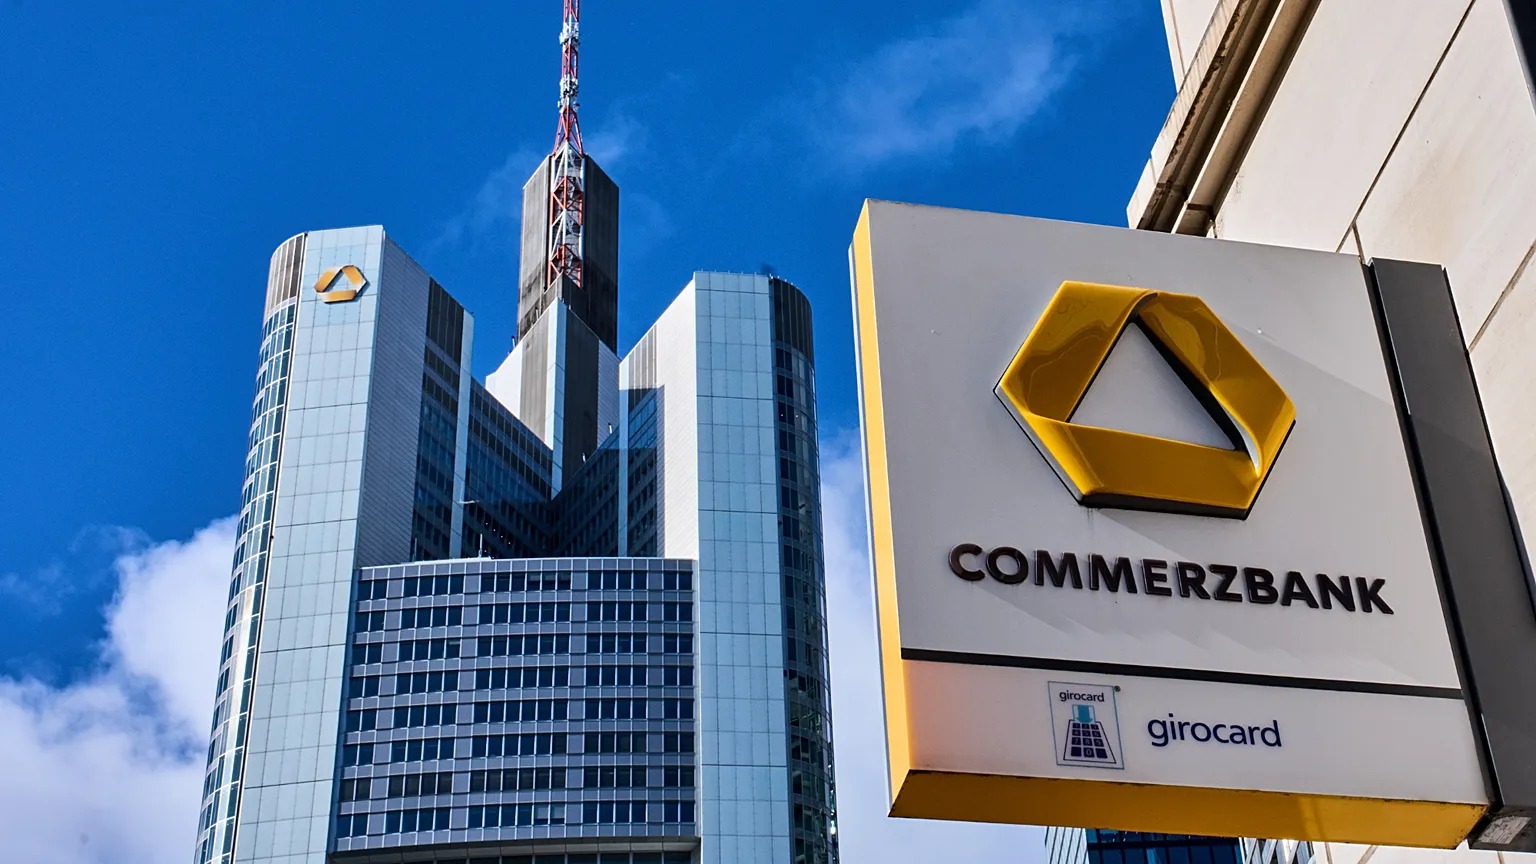
Italy’s UniCredit has secured just under half of the voting rights in Germany’s Commerzbank following a successful takeover bid, setting the stage for a major realignment of the European banking landscape.
According to a report by German Foreign Policy, the Italian lender is positioned to seize control of both the supervisory and management boards of Germany’s second-largest private bank at the annual general meeting of shareholders in 2027.
In this acquisition campaign, UniCredit has drawn support from an international network of financial institutions, including Japan’s Nomura, France’s BNP Paribas, and several US banks.
The development not only brings a near two-year power struggle between the major German and Italian lenders to a close, but also underscores the broader, ongoing consolidation within the European banking sector.
As UniCredit positions itself as a new European banking group, Germany increasingly finds itself on the defensive.
Commerzbank, a cornerstone of the Frankfurt financial center and a vital source of credit for Germany’s small and medium-sized enterprises (SMEs), is now transitioning to foreign control.
The conflict highlights the deep-seated tension between the integration of the European financial sector and the national interests of individual member states seeking to maintain control over their domestic economic hubs.
UniCredit secures majority voting stake
In early May, UniCredit launched a takeover bid that remained open until early July, offering 0.485 of its own shares for each share of Commerzbank.
Following the expiration of the offer period, UniCredit announced that it had acquired 17.6% of Commerzbank’s shares through the share exchange offer.
This transaction lifted its total holdings in the Frankfurt-based lender from 26.77% to 44.37%, effectively handing UniCredit victory in the two-year battle for control.
When factoring in an additional 3.22% stake that UniCredit holds through derivative instruments, its total shareholding reaches 47.59%.
Because the treasury shares held by Commerzbank do not carry voting rights, UniCredit’s stake translates to 49.65% of the total voting rights, according to the Italian bank’s own data.
In addition, UniCredit holds derivatives representing another 13% of Commerzbank shares, though these instruments do not currently carry voting rights.
At the next annual general meeting scheduled for the spring of 2027, eight of the ten shareholder representatives on the supervisory board will stand for re-election.
Leveraging its majority at the annual meeting, UniCredit will be in a position to decisively influence the allocation of these key seats.
Criticism of the bid and “market manipulation” claims
Since the transaction, allegations of market manipulation in connection with the takeover bid have been raised.
However, the Commerzbank General Works Council, which filed a formal complaint against unidentified individuals, suffered a legal defeat in its challenge.
Commerzbank’s management has also repeatedly criticized UniCredit’s disclosures and brought the matter to the attention of BaFin, Germany’s financial regulatory authority.
According to the regulator, a significant portion of the tendered shares belonged to banks and market participants closely linked to UniCredit.
Commerzbank contends that there is a lack of transparency regarding the volume of borrowed shares that were tendered and the specific hedging agreements that remain in force.
It is established that Nomura of Japan, Citigroup of the US, and BNP Paribas of France conducted swap transactions with UniCredit involving Commerzbank shares.
Alongside these institutions, UniCredit can also rely on other major financial firms, including Jefferies and Bank of America.
These partner banks provide UniCredit with potential access to an additional 13% of Commerzbank shares at a specified time.
German government faces potential removal from bank management
In mid-June, UniCredit threatened to replace Commerzbank’s supervisory and management boards.
To execute such a move, however, the major Italian bank would need to replace the two supervisory board members appointed by the German federal government.
The German government secured the right to appoint two representatives to the supervisory board following its state-funded bailout of Commerzbank.
UniCredit has now stated that, provided it receives “sufficient shareholder support” at the annual general meeting, it will be “in a position to elect all shareholder representatives to the supervisory board.”
If UniCredit successfully replaces Commerzbank’s supervisory and management boards at the 2027 annual meeting, it would represent a direct setback for the federal government.
The move would directly impact supervisory board members whose government-appointed terms run through 2029.
Commerzbank’s critical role in the German economy
For the Frankfurt financial center, these developments present a serious challenge.
Commerzbank is a foundational institution of the German financial sector, maintaining deep-seated ties with Germany’s small and medium-sized enterprises (SMEs).
Should the bank be reduced to a branch of UniCredit, key lending decisions would be routed to Milan instead of being resolved in Frankfurt.
Consequently, the Frankfurt financial hub risks losing influence, decision-making authority, and economic sovereignty.
According to Commerzbank, the institution processes approximately 30% of Germany’s foreign trade. Many of the bank’s employees view this extensive reach as a key competitive advantage.
Commerzbank supports the international commercial activities of a vast number of mid-sized firms that frequently struggle to find suitable, dedicated points of contact within larger international banks.
The “consolidation” trend in the European banking system
While the takeover of Commerzbank has met with widespread resistance in German political circles, it has received strong backing from economists, particularly those from other EU member states.
Monika Schnitzer, head of the German Council of Economic Experts, believes there are sound economic reasons to analyze cross-border mergers rather than rejecting them reflexively.
In her view, the European financial market remains insufficiently integrated. She further argues that German banks are highly inefficient by international standards and are therefore ill-equipped to compete against major global institutions.
As early as 2024, European Central Bank (ECB) President Christine Lagarde of France stated that cross-border banking mergers are “desirable” to strengthen European banks in their competition with major US rivals.
Luis de Guindos, the Spanish Vice-President of the ECB, has similarly criticized the German government’s protectionist stance.
In a recent opinion piece published in the Handelsblatt newspaper, Omid Nouripour, Deputy President of the Bundestag (Alliance 90/The Greens), accused the federal government of inconsistency.
Nouripour argued that while the government champions a banking union at EU summits, it reacts to a concrete cross-border bank merger with a “reflex of a national ownership mentality.” He criticized the federal government for praising European integration only “as long as it remains abstract.”
EU Competition Commissioner Teresa Ribera also urged member states to support cross-border banking consolidations. “Member states should welcome such transactions for the public good,” Ribera said.
Signals of compromise from Berlin
The German federal government initially reacted with hostility to UniCredit’s successful takeover bid.
“From the federal government’s perspective, UniCredit’s aggressive and hostile approach remains unacceptable,” the Federal Ministry of Finance said in a statement.
At the same time, Berlin rejected the Italian bank’s takeover offer for its remaining Commerzbank shares.
Last week, Chancellor Friedrich Merz, speaking before parliament ahead of the summer recess, reiterated that the federal government had not accepted UniCredit’s offer and was retaining its shares, unlike a “significant portion” of other shareholders.
However, in the same address, Merz adopted a more conciliatory tone, assuring, “We are not blocking this merger.”
According to the Handelsblatt newspaper, the terms of the takeover are currently being negotiated within the federal government.
Among other stipulations, Berlin is demanding that Commerzbank remain a key lender for German small and medium-sized enterprises.
In addition, the federal government is demanding that Frankfurt, the historic headquarters of the financial institution, remain a major hub for the bank.
UniCredit’s German headquarters has been based in Munich since its 2005 acquisition of HypoVereinsbank.







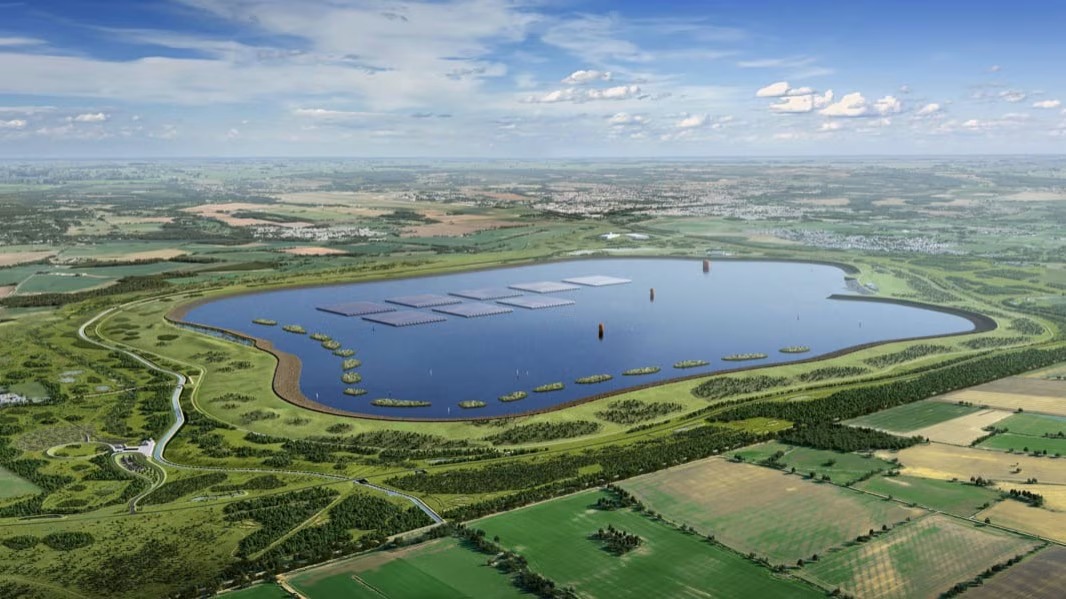
Every adult in Britain would need to pay an extra £590 a year in tax to fund planned public infrastructure investments worth £258 billion.
Sir John Armitt, chair of the private sector-led Public-Private Partnerships Commission, stated that delivering vital projects, such as Thames Water’s long-delayed White Horse reservoir, would require the government to increase infrastructure investment by two-thirds—equivalent to around £25 billion annually until 2030—if financed through public funds.
The crisis surrounding the early release scheme has highlighted the UK’s need for greater prison capacity, while Ofwat has warned that population growth and climate change could leave England facing a shortfall of billions of litres of water per day over the next 25 years.
Armitt, who was the final chair of the National Infrastructure Commission before it was replaced by a new agency, noted that the government’s constrained financial position means its fiscal rules would be “put in jeopardy” if the UK attempted to finance infrastructure spending through additional borrowing.
According to the report, such an approach would add approximately £7 billion to debt interest costs by 2030, £14 billion by 2035, and £23 billion by 2040.
Former Chancellor of the Exchequer Rachel Reeves had altered the fiscal rules to treat capital investment differently from day-to-day spending.
However, the required additional borrowing would still increase overall national debt.
Armitt, who recommended the creation of an OBR-style body for infrastructure, said:
“Those who believe that taxpayers and the public sector can close this gap alone have not looked closely enough at the public finances. If debt interest were a government department, it would be the fourth-largest in Whitehall. The UK faces a fundamental choice: do we want to provide the infrastructure that the public expects and the country needs, or do we not?”
A rise in government bond yields over the past two weeks has narrowed the government’s fiscal headroom, intensifying pressure on Reeves’s successor, John Healey, to balance the public books as Prime Minister Andy Burnham targets “growth in every postcode”.
The commission’s report, delivered by consultancy Bradshaw Advisory, also revealed that the UK has the lowest level of investment among G7 nations.
The report argues that reducing the cost and delivery times of infrastructure projects requires a comprehensive overhaul of the UK planning system, along with the elimination of political risk aversion and other regulatory obstacles.
According to the findings, rail projects in the UK take 50% longer than the international average, whilst delivery timelines for nationally significant projects doubled between 2009 and 2019.
To expedite construction and mitigate the threat of bureaucracy, the report proposes the introduction of a “parliamentary approval vote” for critical national infrastructure projects. Armitt characterised the current landscape as an “appalling cycle” of legal challenges.
The commission noted that uncertainty drives up the cost of infrastructure projects by generating “over-engineered designs to withstand any potential legal challenge and repeated consultations”.
Armitt called for greater pragmatism in Whitehall regarding the role of private investors and developers, who are more efficient than the public sector at delivering infrastructure because they must generate a return on their investments.
He also argued that the available capital pool is vastly larger. UK pension funds hold trillions of pounds in assets, yet only a small fraction is allocated to infrastructure projects.
Armitt said infrastructure investors have recently raised concerns that government efforts to increase public control have dampened their appetite for investing in the UK.
Arguing that this shift would deter investors, Armitt pointed to the windfall tax imposed on North Sea oil.
Armitt added that investors, particularly pension funds, “want long-term certainty and confidence”.
A separate Oxford Economics report commissioned last week by transport groups and infrastructure investors revealed that the UK has lagged behind every major economy except Greece on investment over the past 25 years.
Jon Phillips, chief executive of the Global Infrastructure Investor Association, said:
“Private capital is mobile by nature… at a time when the German, French, and Canadian governments are actively seeking to attract international investors, the UK risks losing ground.”
A government spokesperson said they welcomed “ideas to build the infrastructure needed across the UK”:
“Over the course of this Parliament, we have made progress by publishing the 10-year infrastructure strategy, increasing public investment by £120 billion to crowd in private finance, and delivering reforms to planning, major infrastructure, and regulation to give businesses and local leaders the stability they need to make long-term decisions.”
German sociologist Wolfgang Streeck has examined the link between the conditions driving the rise of the Alternative for Germany (AfD) and the capitalist crisis, calling on the left to “stop playing games and grow up.”
Writing for New Left Review (NLR), Streeck begins by asking what it means to exist within a “polycrisis.” In his view, under an increasingly “less democratic” capitalism, the countries of the rich world face “a bundle of similar crises that have emerged more or less unnoticed.”
According to Streeck, beneath these developments lies a fiscal crisis that has finally moved to the fore. In this context, “the mounting demands placed on society by the evolution of contemporary capitalism” clash with the shrinking capacity of “democratic politics” to secure the resources required to meet them.
Streeck argues that one consequence of this dynamic is the striking rise of “new-model opposition parties that are critical of the existing order and threaten to unseat the now-ageing ruling parties of the post-war era.”
Contending that nearly all of these problems in Germany stem from a policy of “stealth austerity,” Streeck points out that public investment has been deprived of resources as a result: “Stagnant [economic] growth; under these conditions any structural change assumes a zero-sum character; the deterioration of public infrastructure, including railways, bridges, and roads; a growing housing shortage and rising urban rents; the inability of both cities and rural areas to adapt to the consequences of climate change; the lack of an immigration policy to offset an ageing population alongside a sharp decline in birth rates; the decay of the education system, especially primary schools; the indebtedness of local authorities and their diminished capacity to make necessary investments and provide basic services; rising income and wealth inequality; with those most affected being chronically low-income families, particularly families headed by single mothers; and finally, widespread anxiety about the future, driven in part by fears of cuts to basic state-provided services that are becoming increasingly difficult to finance.”
According to the author, since the 1970s an ever-widening gulf has emerged between the overhead costs of capitalism and the amount that capitalist firms are willing (or can be forced) to contribute toward covering them. The progression operates as follows: these costs arise from the necessary preconditions and consequences of capitalist production, ranging from research and development and the creation of human capital to remedying environmental destruction. Yet they also stem from the need to secure legitimacy for a mode of production in which the extracted surplus value accrues to a small class of capital owners. Every form of the social wage; that is, state top-ups to the market wages of workers, such as social security and health insurance, serves to consolidate this legitimacy. As capitalist development advances and new needs arise among workers and their families, these expenditures (such as childcare facilities or eldercare) expand. At the same time, however, the scope for levying taxes on both the working classes and the classes that profit from them reaches its limits.
Streeck writes that during the neoliberal era, in order to sustain this zero-sum game; that is, to enable both capitalists and workers to carry on, states resorted to borrowing on deregulated global financial markets. Yet as sovereign debt levels escalated, the state faced the risk of losing its “creditworthiness” in the assessment of “the markets”; doubts emerged over its ability to meet interest payments from existing revenues, and even the interest itself had to be financed through borrowing.
In Germany, this development manifests through a “reform” debate conducted “under the watchful eye of the markets,” encompassing restrictions on pensions, sick leave, and labour rights.
Alongside this, the debt tap is opened to appease NATO allies and the arms industry, and perhaps as a last resort to slow down deindustrialisation.
According to Streeck, with the fiscal crisis no longer a slow-moving one, and with no hope of bringing it and the accompanying infrastructure and social welfare crises under control in the foreseeable future, traditional centrist parties have abandoned their conventional approach of “spreading cheer and optimism.”
The same holds true for the standard democratic narrative that those dissatisfied with government policy can vote for another party at the next election; the risk that this will benefit the new “anti-systemic” opposition appears too great.
Streeck writes:
“This paves the way for the formation of a party cartel in which the main parties avoid clashing with one another. In Germany this scenario seems particularly plausible: after all, the CDU and SPD were in power almost uninterruptedly throughout the long years of ‘shadow austerity’, and largely in coalition.”
Consequently, the issue ceases to be the debt crisis, rising rents, crushing living costs, shrinking public services, or growing segments of the population turning to food banks; instead, it becomes “populism,” the AfD, and neofascism.
Streeck points out that centrist parties, or “we democrats,” use this to make closing ranks mandatory once again. The logical extension of this policy is a summons to fight “against the right” and make a final stand for “our democracy,” rather than struggling against the growing power of markets over the public: “And for the sake of this, we are asked to set aside our petty squabbles over who will be subjected first, and who spared until later, to the overt austerity demanded by subsidised capital markets.”
Streeck continues:
“At first glance; from the standpoint of the ruling political class; this certainly has its appeal. Demonstrations by all sensible people against the AfD are far preferable to demonstrations against the rising cost of living; ‘firewalls’ cost far less than insulating the walls of old apartments; reports by the Federal Office for the Protection of the Constitution are far cheaper than nurseries and schools where all children can be accommodated and educated together. Moreover, floating the idea of having a party supported by at least a third of the electorate banned by the Constitutional Court in the name of ‘militant democracy’ guarantees an exciting item on the evening news about the daily exertions of those who run the state.”
Yet Streeck believes that none of this will work, either now or in the long run. Pointing out that the current governing and political class has taken no steps to address the real problems it “wants to hide behind the AfD problem,” the sociologist says: “Even if the party is banned, trains will still not run on time, heat-related deaths will not decline, cities will not become more liveable, rents will not fall, and pensions and jobs will not become more secure.”
Streeck notes that the situation would not change if the AfD were to enter government rather than being politically or physically locked away; nevertheless, he argues that the prevailing political mentality fears giving the AfD the opportunity to fail in the face of the “polycrisis.”
Streeck believes the AfD will not be diminished by the next demonstration or the next broadcast of partisan television news. In his view, as long as the “forces of the state and democracy” exhaust themselves on a secondary battlefield such as “democracy versus populism” to divert attention from the crises unfolding under their own governance, the AfD will have an easy ride.
Reminding readers that an external enemy (Russia) has been added to the internal enemy, Streeck underlines that the two are conflated as far as possible through “conspiracy theories.”
The author notes that the drive to transform a “welfare” state into a “garrison” state and brand the AfD as the “Kremlin’s fifth column” raises the question of how a debt-laden government intends to fund raising defence spending to at least 5% of GDP: “Will it resort to even more austerity or even more borrowing, risking an ultimate rupture with the domestic population, with global financial markets, or with both?”
Arguing that the left, unlike “PR specialists,” must ask certain questions, the German author points to the following:
“How can we make capital pay the bill for the costs it imposes on society and nature? How can we prevent tax avoidance and tax evasion? How will we protect companies that provide quality jobs to people in our country from a global trading system that shows no respect for workers? How can we halt the decline in our population through immigration and better family policies? In a society in transition like ours, how will we ease the debt burden on our local authorities so that they can deliver the public services essential for everyone to lead a good life? And how must ‘our democracy’ be restructured so that it becomes a democracy for all and gives citizens the opportunity to take control of their own lives; so that they are not forced to beg for handouts from a state whose coffers are empty and will remain so for a long time to come?”
Streeck concludes his article by stating: “Playtime is over; the situation is serious, and we urgently need to grow up.”

Ulrich Siegmund of the Alternative for Germany (AfD), who is expected to become the next state premier of Saxony-Anhalt, has stated that they do not oppose Germany’s rearmament, arguing that arms will be required during the “remigration” process.
The issue specifically concerns a factory in the Saxony-Anhalt town of Sangerhausen. Israeli defence contractor Elbit intends to establish production facilities there, though protests against the plan have been under way for some time.
The company manufactures, among other products, the Hermes combat drone, howitzers, and rocket launchers.
According to Christian Democratic Union (CDU) Mayor Torsten Schweiger, neither drones nor ammunition will be produced in Sangerhausen.
The Sahra Wagenknecht Alliance (BSW) had previously announced its opposition to the state becoming a defence industry hub for Israel.
Following a parliamentary group meeting, Siegmund was asked directly at a press conference about the proposed investment project.
Siegmund replied:
“Our position is very clear. We do not condemn the production of military equipment in general, because during future repatriation and deportation campaigns for migrants, we will naturally require the appropriate tools. This also applies to internal security, our own stability, and national defence. We are aware that such things do not fall from the sky.”
Siegmund also argued that a distinction exists between sending military equipment to foreign wars financed by German taxpayers and the approach they advocate.
AfD has not yet taken a final decision
Siegmund explained that the AfD is monitoring the situation in Sangerhausen and remains in contact with local political representatives.
At the same time, he noted that the economic aspects of a potential factory site should not be ignored. The party also plans to examine closely what is produced in Sangerhausen and under what conditions.
“We want to examine closely: what is produced there, and under what conditions? And do we face the risk of being drawn into foreign conflicts as a result? If so, we view this situation with great scepticism,” Siegmund said.
Siegmund also pointed to conversations he had with citizens during the election campaign. Many people, including local residents in Sangerhausen, welcomed the AfD’s stance.
However, his party has not yet reached a final decision regarding the prospective facility. “A valid decision has not yet been taken because we still do not possess all the information,” the AfD politician said.
Green light for militarisation on grounds of remigration and security
Siegmund’s remarks indicating that weapons are needed for “remigration” drew attention. The term refers to the deportation of people with an immigrant background and was coined by Austrian right-wing activist Martin Sellner. The AfD has adopted the phrase over the past few years.
Years ago, Thuringia AfD leader Björn Höcke spoke of “well-measured cruelty” in the context of deportation procedures.
AfD politicians Kay Gottschalk and Lena Kotré attended an international “Remigration Summit” held in Portugal in late May.
There, Martin Sellner of the Identitarian movement declared their aims to secure “Europe’s ethnocultural continuity”, halt all legal or illegal immigration into Europe, and remove “millions” of non-Western immigrants from the continent.
In a video recorded alongside Sellner, Dutch activist Eva Vlaardingerbroek said: “Nobody comes in, and millions go out.”
In interviews, Kotré and Gottschalk presented the mass deportation of millions of people as a panacea for the housing market, the education system, and society.
Federal Chancellor Friedrich Merz criticised the AfD on Wednesday, stating that the concept of “remigration” amounts to nothing other than “ethnic cleansing based on skin colour and origin”.
Wagenknecht criticises “remigration”
Meanwhile, BSW, which decided unanimously to hold talks with the AfD in Saxony-Anhalt, has publicly announced its “red lines”.
Party founder Sahra Wagenknecht stated that she maintains clear red lines against the AfD, particularly regarding “remigration”.
In an interview with RTL and ntv, Wagenknecht said: “They will feel our strong opposition on this matter. I find it terrible that people are worried and frightened.”
Stating that it is unacceptable for “well-integrated citizens” to be affected, the BSW leader remarked: “And we will not yield on this.” She continued:
“If the AfD is truly serious about frightening people who came to our country, work here, are well integrated, pay taxes, and whose children grow up here; if they intend to tell them, ‘You do not belong here’ or convey the message, ‘We want to expel you’ [we will prevent it].”
Regarding the AfD’s election manifesto equating homosexuality with “sexual deviance”, Wagenknecht replied: “Naturally, we believe every individual should live and love as they wish, and that equality exists here, including legal equality. Anyone questioning this does not live in modern times.”
BSW does not back Siegmund for premier
Wagenknecht also dismissed claims that BSW would elect AfD candidate Ulrich Siegmund as state premier in Saxony-Anhalt, stating: “We have always made what we want very clear.”
Wagenknecht argued that Siegmund had given “completely contradictory statements regarding when he wants to be state premier and when he does not”.
“One gets the impression that he himself might feel it is not such a good idea after all,” Wagenknecht said.
The BSW founder called for a “respected figure across party lines” upon whom everyone could agree and who could “bring this country a little closer together”.

Big Tech profits from AI extinction hype, Ken Klippenstein says

Israel military weighs legal steps against Gaza documentary makers

Finkelstein says US campus clampdown has surpassed McCarthyism

DeepSeek engineer warns AI will lead to communism or Cyberpunk

Israel pledges full Greek control over Achilles’ Shield source code
-
 Europe2 weeks ago
Germany’s CDU drafts tougher citizenship rules to counter AfD
-
 America2 weeks ago
Pentagon launches mass polygraph inquiry over munitions leaks
-
 Asia2 weeks ago
China leads $54bn capital injection into state banks and insurers
-
 Russia2 weeks ago
Mearsheimer says Trump seeks Ukraine peace but lacks diplomacy skills
-
 Europe2 weeks ago
AfD secures sweeping victory in Saxony-Anhalt state election
-
 Middle East2 weeks ago
Iran weighs 1980 hostage crisis playbook for US midterms
-
 America5 days ago
Milanovic declares global neoliberalism dead, warns of plutocracy
-
 Europe2 weeks ago
BSW rules out AfD coalition but weighs issue-by-issue cooperation
