Asia
China launches global tax audit on super-rich to recover billions

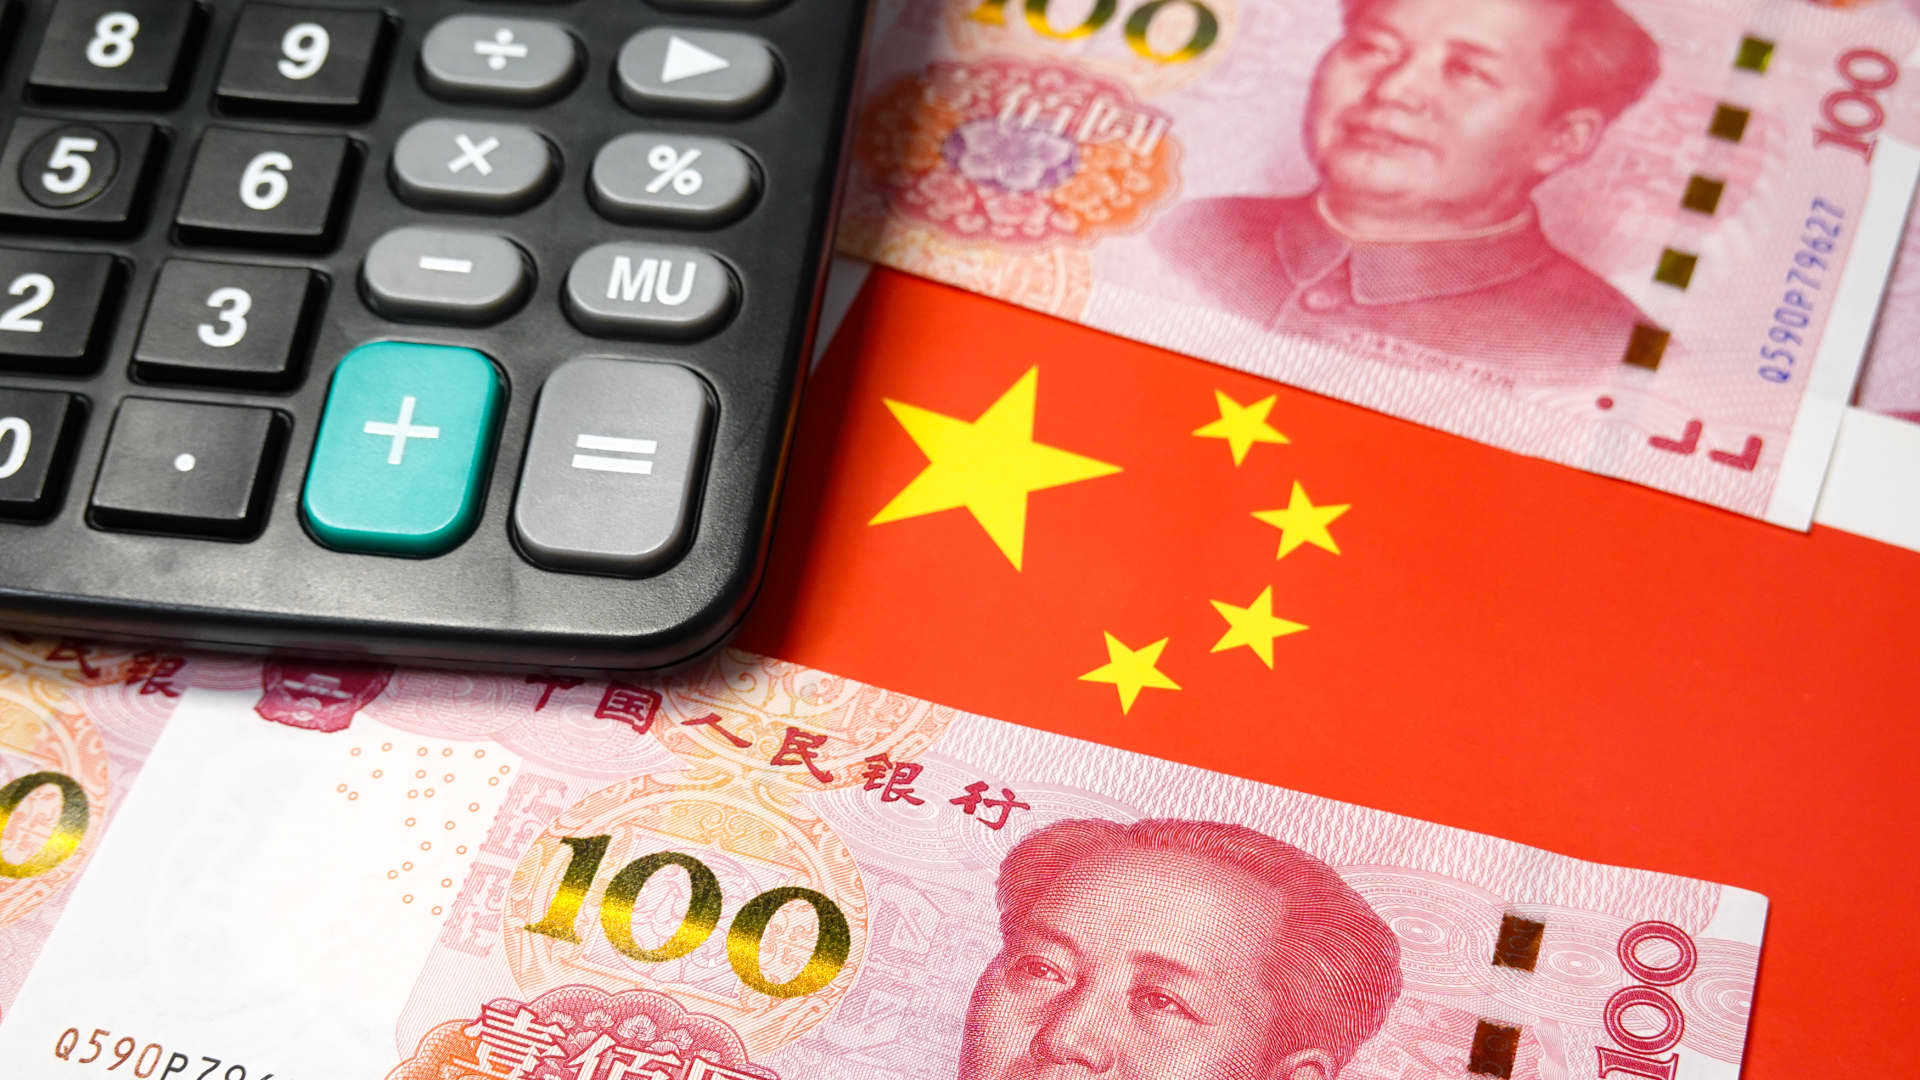
China has launched a global crackdown on its super-rich to collect hundreds of billions of dollars in unpaid taxes dating back decades, seeking to narrow income and wealth inequality and close a deepening budget deficit.
Authorities have intensified their scrutiny of overseas capital gains and investments, with investigations extending in some instances as far back as 2000. The campaign comes as Beijing attempts to significantly expand its oversight of outbound capital flows.
According to foreign officials, Chinese bankers, and family office executives who spoke to the Financial Times, Chinese banks and other financial institutions have been instructed to review the overseas investments of wealthy Chinese nationals and check whether the resulting income has been declared to tax authorities in Beijing.
The efforts, which form part of sweeping tax reforms targeting the country’s wealthy elite and offshore trusts, focus on gains derived from the acquisition of assets such as real estate, equities, precious metals, and cryptocurrencies.
Numerous officials, bankers, and advisers confirmed the retrospective nature of the campaign, noting that inquiries cover periods reaching back more than 25 years in certain cases.
A banker in southern China said that in recent months, Chinese banks have increasingly coordinated with tax authorities to freeze the accounts of wealthy clients until officials are satisfied that taxes on capital gains from overseas assets, accounts, and trusts have been paid.
“In standard practice, these wealthy individuals immediately pay the penalties and taxes in cash to get their accounts unfrozen,” the banker said.
The timeframes examined in the tax audits appear to vary significantly. For instance, an executive at a Shenzhen-based family office said clients were asked to pay taxes on gains generated from overseas assets between 2017 and 2022. No explanation was provided as to why that specific period was targeted.
Victor Shih, a professor of Chinese political economy at the University of California, San Diego, said the motivation behind the new campaign was “clearly rooted in fiscal reasons.”
China’s fiscal revenues, where taxes plug a critical gap, have largely stagnated since the pandemic and contracted by 1.7% in 2025 to 21.6 trillion yuan, or $3.2 trillion. Total public revenue from land sales, once a primary source of state income, fell to 4.15 trillion yuan following a real estate market downturn, down from a peak of 8.7 trillion yuan in 2021.
Last month, China also enacted comprehensive tax rules governing assets transferred to offshore trusts. According to a joint statement by China’s Ministry of Finance and the State Taxation Administration, the regulation closed a legal loophole long utilized by wealthy individuals to protect their assets abroad.
Under the new rules, income generated from offshore trusts will be subject to a 20% tax across multiple stages.
A Singapore-based banker who manages overseas assets for wealthy Chinese nationals said the offshore trust tax “shocked” clients.
“There are people who established trusts for public assets, such as shares in listed companies. During periods when initial public offerings were very common, holding the right trust structure provided protection regarding income tax. This new decision has eliminated that advantage,” the banker said.
While experts suggest that some complex overseas structures may evade the new rules, many trust holders are expected to face a one-off tax liability. Reports indicate that some may be forced to sell assets to meet the payments.
Together with other tax reforms, the new policies will align China’s taxation system more closely with that of the US, where American taxpayers are generally taxed on their worldwide income.
Ye Yongqing, a Shanghai-based tax lawyer and partner at Anli Partners, said, “Regulatory bodies have steadily tightened oversight of cross-border capital flows, declarations of overseas income, and foreign exchange transactions. Consequently, the scope for wealthy Chinese to transfer assets abroad or structure their tax affairs through offshore vehicles has narrowed.”
Ye noted that Beijing has adopted a restrictive approach toward offshore trusts similar to US tax legislation, broadly rejecting attempts by taxpayers to use these vehicles to defer or entirely eliminate tax.
There are also indications that stricter tax collection from China’s wealthy has yielded results in recent years. Official data shows that personal income tax revenues rose 11.5% in 2025, driven by the impact of previous campaigns, including the taxation of Hong Kong stock transactions. This growth rate significantly outpaced the 0.8% expansion in overall tax revenues.
An executive at an immigration firm with offices in China and New York said authorities initially targeted wealthy Chinese trading US equities via Hong Kong or other overseas channels.
The executive said the inquiries are expected to expand next to individuals holding substantial financial assets in overseas bank accounts, particularly in Hong Kong, and ultimately to other forms of offshore wealth, including real estate.



Financial Times writer Ryan Avent has written that a fresh, rapid surge in China’s trade surplus could signal a new wave of the “China shock”.
Economists define the “China shock” as a spike in Chinese exports to global markets that intensifies competition for manufacturers in advanced economies and curtails employment in certain sectors.
The term gained widespread currency after China joined the World Trade Organization in 2001, accelerating the inflow of inexpensive Chinese goods into the US and other nations.
The US was the country hit hardest by the initial shockwave. Between 1999 and 2011, more than 2 million jobs were lost because domestic producers were unable to withstand the competition.
Avent argued that the effects of the initial wave are still felt across the American economy because China failed to carry out the rebalancing that the world expected.
The share of net exports in China’s gross domestic product contracted during the 2007-2019 period, allowing Western nations to focus on national security and other matters.
Avent reported that the trade surplus is now escalating rapidly once again, posing a threat to the economies of wealthy nations.
The writer pointed to the stagnation of domestic demand following the collapse of the real estate market six years ago as one cause of this surplus. Another prominent factor is the Beijing government’s channelling of massive resources into manufacturing in pursuit of self-sufficiency.
Attention was also drawn to the role of the depreciating yuan. An appreciation of the currency could require China to alter its foreign exchange interventions, reduce purchases of foreign currency and assets, and sell those assets off. That scenario could trigger currency depreciation and rising interest rates in other countries.
The Wall Street Journal also reported in the spring of 2024 on economists’ concerns regarding a potential second wave.
Experts predicted that global markets would once again be flooded with inexpensive goods, stating that China was manufacturing far beyond domestic demand to overcome its economic troubles.
Moreover, it was stressed that China is now competing in high-technology fields such as automobiles, computer chips, and complex machinery manufacturing.
Meanwhile, Vasiliy Kashin, Director of the Centre for Comprehensive European and International Studies at the Higher School of Economics (HSE) University in Moscow, told the Russian media outlet RBC that the US has imposed sanctions on the Chinese economy since the first shock period, adding that these measures would very likely tighten in the event of a fresh export wave.
According to assessments reported by the Financial Times, this new process could also shake China’s own economy. Alongside rising output, entry-level manufacturing plants across the country are turning toward automation and reducing personnel.
This trend could trigger a painful departure from labour-intensive production, leaving millions unemployed. Manufacturing activities in China that previously capitalised on cheap labour are shifting to other Southeast Asian countries.
The Beijing administration rejected allegations that its industrialisation steps pose risks to other countries. As reported by the Xinhua news agency, China’s Ministry of Commerce stressed that claims of a “China shock 2.0” are groundless. The ministry stated:
“The US and other Western countries have circulated the so-called ‘China shock 2.0’ narrative, asserting that China’s industrial development has shaken Western monopolies and narrowed growth space for Global South countries. This claim is unsupported by concrete data and is entirely unfounded.”
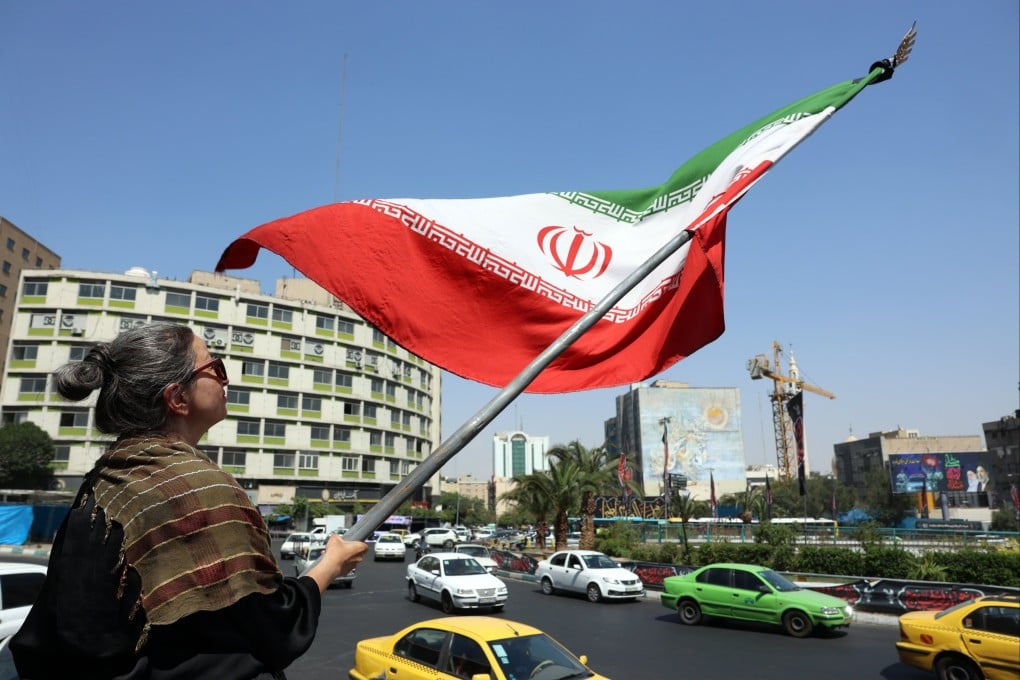
Iran is operating a covert, barter-like trade mechanism to bypass sanctions on its oil sales and procure billions of dollars in goods from China, including military hardware.
Speaking to the Reuters news agency, two senior Iranian officials and three sources closely monitoring the matter said the Tehran administration receives credits for goods imported from China instead of cash in exchange for the oil it sells to the country.
The sources, who spoke on condition of anonymity, emphasised that this method of swapping oil revenues for Chinese goods provides an immediate financial lifeline to the Tehran government at a time when the US has intensified economic and military pressure over its nuclear programme.
China, the world’s largest crude importer, continues to access discounted Iranian oil through this arrangement while shielding its banks and exporting companies from the risk of international penalties.
Although the Washington administration has imposed sanctions on several small-scale Chinese entities facilitating the transport of Iranian oil, it avoids sweeping measures that could shake the global economy.
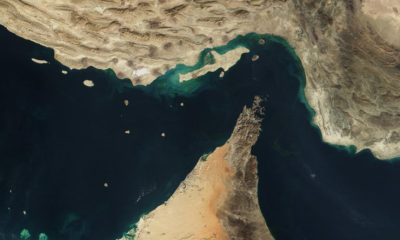
The US has stepped up its pressure as it seeks to reopen the Strait of Hormuz amid the ongoing war between the two countries.
US Treasury Secretary Scott Bessent said last month that countries failing to cut commercial ties with Tehran would risk exclusion from the dollar system.
It remains unclear how the barter mechanism has been affected by the US naval blockade imposed on Iran as part of the six-month-old war.
However, since the reimposition of the blockade on 14 July, no shipments of Iranian oil passing through the Strait of Hormuz to China have been recorded.
Beijing and Tehran, which describe Western unilateral sanctions as illegal, refrain from disclosing publicly how they sustain their trade.
Sources state that Tehran introduced this system to obtain pharmaceuticals, vehicles, and communications equipment. Chinese manufacturers are said to have no direct contact with Iran, and there is no indication that they are violating sanctions.
On the other hand, the mechanism was utilised at least once last year under contracts supplying Iran with millions of dollars’ worth of air defence equipment. The sources provided no details regarding the shipments in question, and the transactions were not independently verified.
The United Nations conventional arms embargo returned alongside other sanctions in September 2025 following the collapse of the 2015 nuclear agreement between Iran and world powers.
Tehran had withdrawn from the terms of the agreement, while Beijing and Tehran described the European nations’ automatic reimposition of sanctions as legally flawed.
Responding to questions from Reuters, the Chinese Ministry of Foreign Affairs stated that it had no knowledge of the trade structure in question.
Beijing stated that it opposes unilateral sanctions lacking United Nations Security Council authorisation and having no basis in international law.
Iran’s diplomatic missions in New York and Geneva remained silent on the inquiries. A US official speaking on behalf of the White House stated only that they are working with international partners, including the EU, to prevent Tehran from achieving its nuclear goals.
According to data analytics company Kpler, China purchased more than 80% of the crude oil exported by Iran in 2025. This share equates to an average of 1.4 million barrels per day.
Although the two countries signed a 25-year strategic partnership agreement in 2021 covering energy and infrastructure, the operational details of their cooperation remain largely confidential.
The model in question constitutes only one of the networks through which Iran procures goods and services from China without passing through international banking channels.
A Western official and two other individuals tracking the matter said that a buyer acting on behalf of state-owned Chinese oil company Zhuhai Zhenrong deposited hundreds of millions of dollars each month until this year into ChuXin, a shadow financial entity based in China.
These deposits reportedly represent payment for oil purchased from a Hong Kong-based company linked to the National Iranian Oil Company (NIOC).
Approximately 70% of the oil revenues routed through ChuXin is allocated to infrastructure projects in Iran. The remainder is transferred to the accounts of a special purpose vehicle (SPV) established to disburse payments to companies supplying goods to Iran.
Sources close to Iran’s decision-making apparatus confirm the existence of this financial mechanism.
Fund management is shared between a firm acting on behalf of the Chinese Ministry of Commerce and another entity linked to the Central Bank of Iran. When the Central Bank of Iran authorises importers, money transfers are directed to supplier firms. While the name ChuXin does not appear in official records, one source noted that the structure exists solely on balance sheets.
Andrea Ghiselli, an international politics specialist at the University of Exeter, stated that Beijing uses these indirect networks to demonstrate that it will not bow to US secondary sanction threats.
Highlighting that Chinese leaders aim to protect their own banks and firms from being pushed out of the global financial system, Ghiselli said: “They want to create deniability.”
China’s Ministry of Finance will lead a total capital injection of $54 billion into state-owned insurance companies and banks as part of a coordinated push to reinforce the capital structure across the country’s financial system, according to details disclosed by the institutions in statements on Sunday.
China Life Insurance (Group) Co, the country’s largest life insurer, will receive 35 billion yuan ($5.2 billion) in capital support, whilst China Taiping Insurance Group will receive 7 billion yuan.
In a separate announcement, People’s Insurance Company (Group) of China (PICC) said it plans to raise up to 15 billion yuan via a private placement of A-shares to the Ministry of Finance. The company stated that the proceeds will be used to replenish its capital.
The initiative could fortify the financial position of state insurers, which have been called upon to support the equity market with medium- and long-term funds. At the same time, it could position these institutions to help regulatory authorities manage smaller and higher-risk insurance companies.
Financial sector stability
China’s insurance industry has been contending with shrinking profitability caused by prolonged low interest rates. Solvency ratios across numerous small and medium-sized insurers have also deteriorated.
China Export and Credit Insurance Corp stated that the Ministry of Finance will inject 10 billion yuan to boost the company’s core capital. China Reinsurance (Group) announced that it will execute a capital increase of 3 billion yuan.
“The capital injection represents an important step for enhancing the financial sector’s capacity to serve the real economy and promoting high-quality development across the financial and insurance industries,” China Life said in a statement. The insurer added that the capital support will improve the group’s resilience to risks.
Taiping also noted that the funds provided will strengthen the company’s solvency and other core metrics.
Banks benefit from recapitalisation plan
Separately, three state banks announced on Sunday that they will receive capital support totalling 290 billion yuan.
The recapitalisation framework was first announced during the annual parliamentary meetings in March this year. The move broadens a funding mechanism deployed last year to strengthen the capital structures of several other major state-owned lenders.
Agricultural Bank of China and Industrial and Commercial Bank of China (ICBC), two of the country’s largest state-owned lenders, announced plans to raise up to 160 billion yuan and 100 billion yuan, respectively, through private placements of A-shares to the Ministry of Finance, China National Tobacco Corp, and affiliated entities.
Both lenders confirmed that all net proceeds will be deployed to replenish their Core Tier 1 capital. The measure is expected to help sustain credit expansion at a juncture when Beijing is increasingly relying on state lenders to support economic growth.
Weak credit demand remains a persistent headwind for the world’s second-largest economy, while continuing to erode profitability across the banking sector.
Export-Import Bank of China, one of the country’s three policy banks, stated that the Ministry of Finance will inject 30 billion yuan of capital into the institution, thereby bolstering its capital base.

Will Qatar fund Benjamin Netanyahu in this election too?

UK faces £258bn infrastructure gap as commission urges private funds

Milanovic declares global neoliberalism dead, warns of plutocracy

Saudi exportable crude stocks risk depletion within a week

Iran used Chinese satellite imagery in deadly US base attack: report
-
 Europe1 week ago
Germany’s CDU drafts tougher citizenship rules to counter AfD
-
 Russia2 weeks ago
What to know about Russia’s upcoming State Duma elections?
-
 Europe2 weeks ago
Marine Le Pen leads all 2027 French presidential scenarios, poll shows
-
 Diplomacy1 week ago
Geoffrey Roberts sees Ukraine war concluding within coming months
-
 Middle East2 weeks ago
Iran expands deterrence as Gulf strikes expose US munitions limits, analysts say
-
 Europe2 weeks ago
German industrial bosses push for return to 40-hour working week
-
 Russia2 weeks ago
Russia warns NATO over Arctic militarisation and conflict risks
-
 Asia2 weeks ago
BOJ faces critical rate decision as US presses for faster hikes
