Europe
Investors pivot to Eurobonds as Trump tariffs and geopolitical volatility rattle US Treasury market

Foreign investors are increasingly turning toward European Union debt as Donald Trump’s trade tariffs and a foreign policy punctuated by conflict drive nervous markets to seek stability in EU bonds.
According to a report by POLITICO, this shift represents welcome news for the European Commission, which has been scaling up bond issuances to fund new mandates, including increased defense spending and support for Ukraine’s war efforts.
Brussels is framing its “sales pitch” around a distinct narrative: the EU’s slow, consensus-driven decision-making process serves as a bastion of stability in a world upended by Trump. By investing in Eurobonds, the Commission argues, investors can secure a stake in that stability.
Data obtained by POLITICO reveals that fund managers from the United Kingdom, Asia, the Middle East, Africa, and Oceania have purchased 43% of the Eurobonds auctioned by the Commission since the start of 2026. This marks an 8% increase over the average of the last six years. The trend places EU Budget Commissioner Piotr Serafin in a strong position ahead of a scheduled promotional tour in mid-April, where he will pitch Eurobonds to investors in Hong Kong, Malaysia, and Singapore.
Since the beginning of 2026, the Commission has issued €52 billion in bonds, up from €44 billion during the same period in 2025.
“Demand for Europe is rising due to its alignment with the rules-based international order and values,” a senior EU official told POLITICO. “Consequently, demand for EU bonds is also on the rise.”
The eurozone’s rescue fund and its predecessors—the European Stability Mechanism (ESM) and the European Financial Stability Facility—have observed a similar trend. According to ESM data presented in January, these institutions have issued a total of €566 billion in bonds since 2010 and sold a record amount of debt to non-EU countries in 2025.
Since the US and Israel began bombing Iran in late February, central banks, governments, and international investors have sold a net total of more than $80 billion in US Treasuries. On this side of the Atlantic, the EU is leveraging these developments to solidify its reputation as a safe haven for anxious foreign investors.
“EU leaders are emphasizing that Europe is predictable in terms of policy, and in today’s global geopolitical environment, this will be noticed by many investors and market participants,” said Ken Egan of the KBRA credit rating agency.
The sell-off in the US does not yet constitute a mass exodus. While the US Treasury market stands at approximately $31 trillion, the market for bonds issued by the European Commission barely reaches €1 trillion. However, the rising demand for Eurobonds, coupled with a robust credit rating, allows the Commission to borrow at lower costs than many indebted EU governments.
In a sign of growing market confidence, the yield spread on Commission bonds over German government bonds—long considered the safest in the eurozone—has narrowed to approximately 40 basis points. This is down significantly from 70 basis points in 2022. One basis point is equal to one-hundredth of one percent. Meanwhile, US Treasuries offer investors a premium of over 130 basis points compared to German Bunds.
Factors beyond concerns over Trump’s policies are also at play. Some investors purchase EU bonds specifically for their very low risk profile, while increased issuance volumes have improved market liquidity, making it easier for investors to trade these securities.
Without common debt, governments would have struggled to manage consecutive crises independently. EU debt has funded a €650 billion post-pandemic recovery fund, €150 billion in low-cost loans to bolster military spending across the bloc, and a €90 billion package to assist Ukraine’s defense against Russia—the latter of which is currently blocked by Hungary.
The burgeoning interest in Eurobonds is also encouraging the EU’s ambition to challenge the dollar as the world’s primary reserve currency. The US has held this status for decades, formalized by the 1944 Bretton Woods agreement, which positioned the dollar as the anchor of the global financial system and facilitated cheap borrowing for Washington. The dollar accounts for approximately 56% of global reserves, while the euro remains steady in second place at around 20%.
However, the Commission is seizing this opportunity to attract foreign investors and expand its global influence.
“When investors seek to gradually decouple their economies from the dollar due to economic stability, they look to the euro,” the senior EU official noted.
The long-standing taboo surrounding the EU’s joint debt issuance was broken following the pandemic, ending years of resistance from Northern European governments during the euro crisis. As countries like France and Italy realized they were too indebted to manage recent crises alone, Eurobond issuances continued to grow in subsequent years.
For a bloc grappling with the economic fallout of the war in Iran and Trump’s repeated threats to withdraw the US security umbrella from Europe, these fiscal pressures are unlikely to ease. EU leaders are also determined to accelerate the economy to keep pace with the US and China. According to former European Central Bank President Mario Draghi, this is a costly undertaking requiring approximately €800 billion annually.
While investment on that scale remains distant, the Commission—which has become the world’s third-largest AAA-rated bond issuer after Canada and Germany, according to various rating agencies—has indicated it will continue to issue debt in the coming years. The rating for US Treasuries varies by agency between AAA and the slightly lower AA.
Brussels has stated that in its new seven-year budget proposal, effective from 2028, it will utilize Eurobonds to fund the reconstruction of Ukraine, respond to crises, and provide loans for member states to invest in EU priorities.
Nevertheless, frugal Northern nations such as Germany and the Netherlands, which pay lower interest rates by borrowing on their own behalf than through the Commission, oppose further EU common debt in ongoing negotiations. Until a new budget is agreed upon, investors expect the EU executive to maintain its current trajectory. The EU plans to sell €160 billion in Eurobonds this year, a €10 billion increase over 2025.

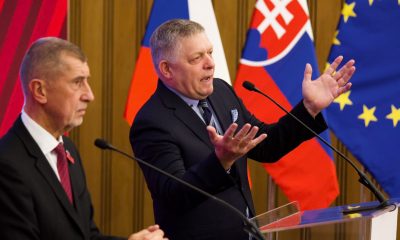


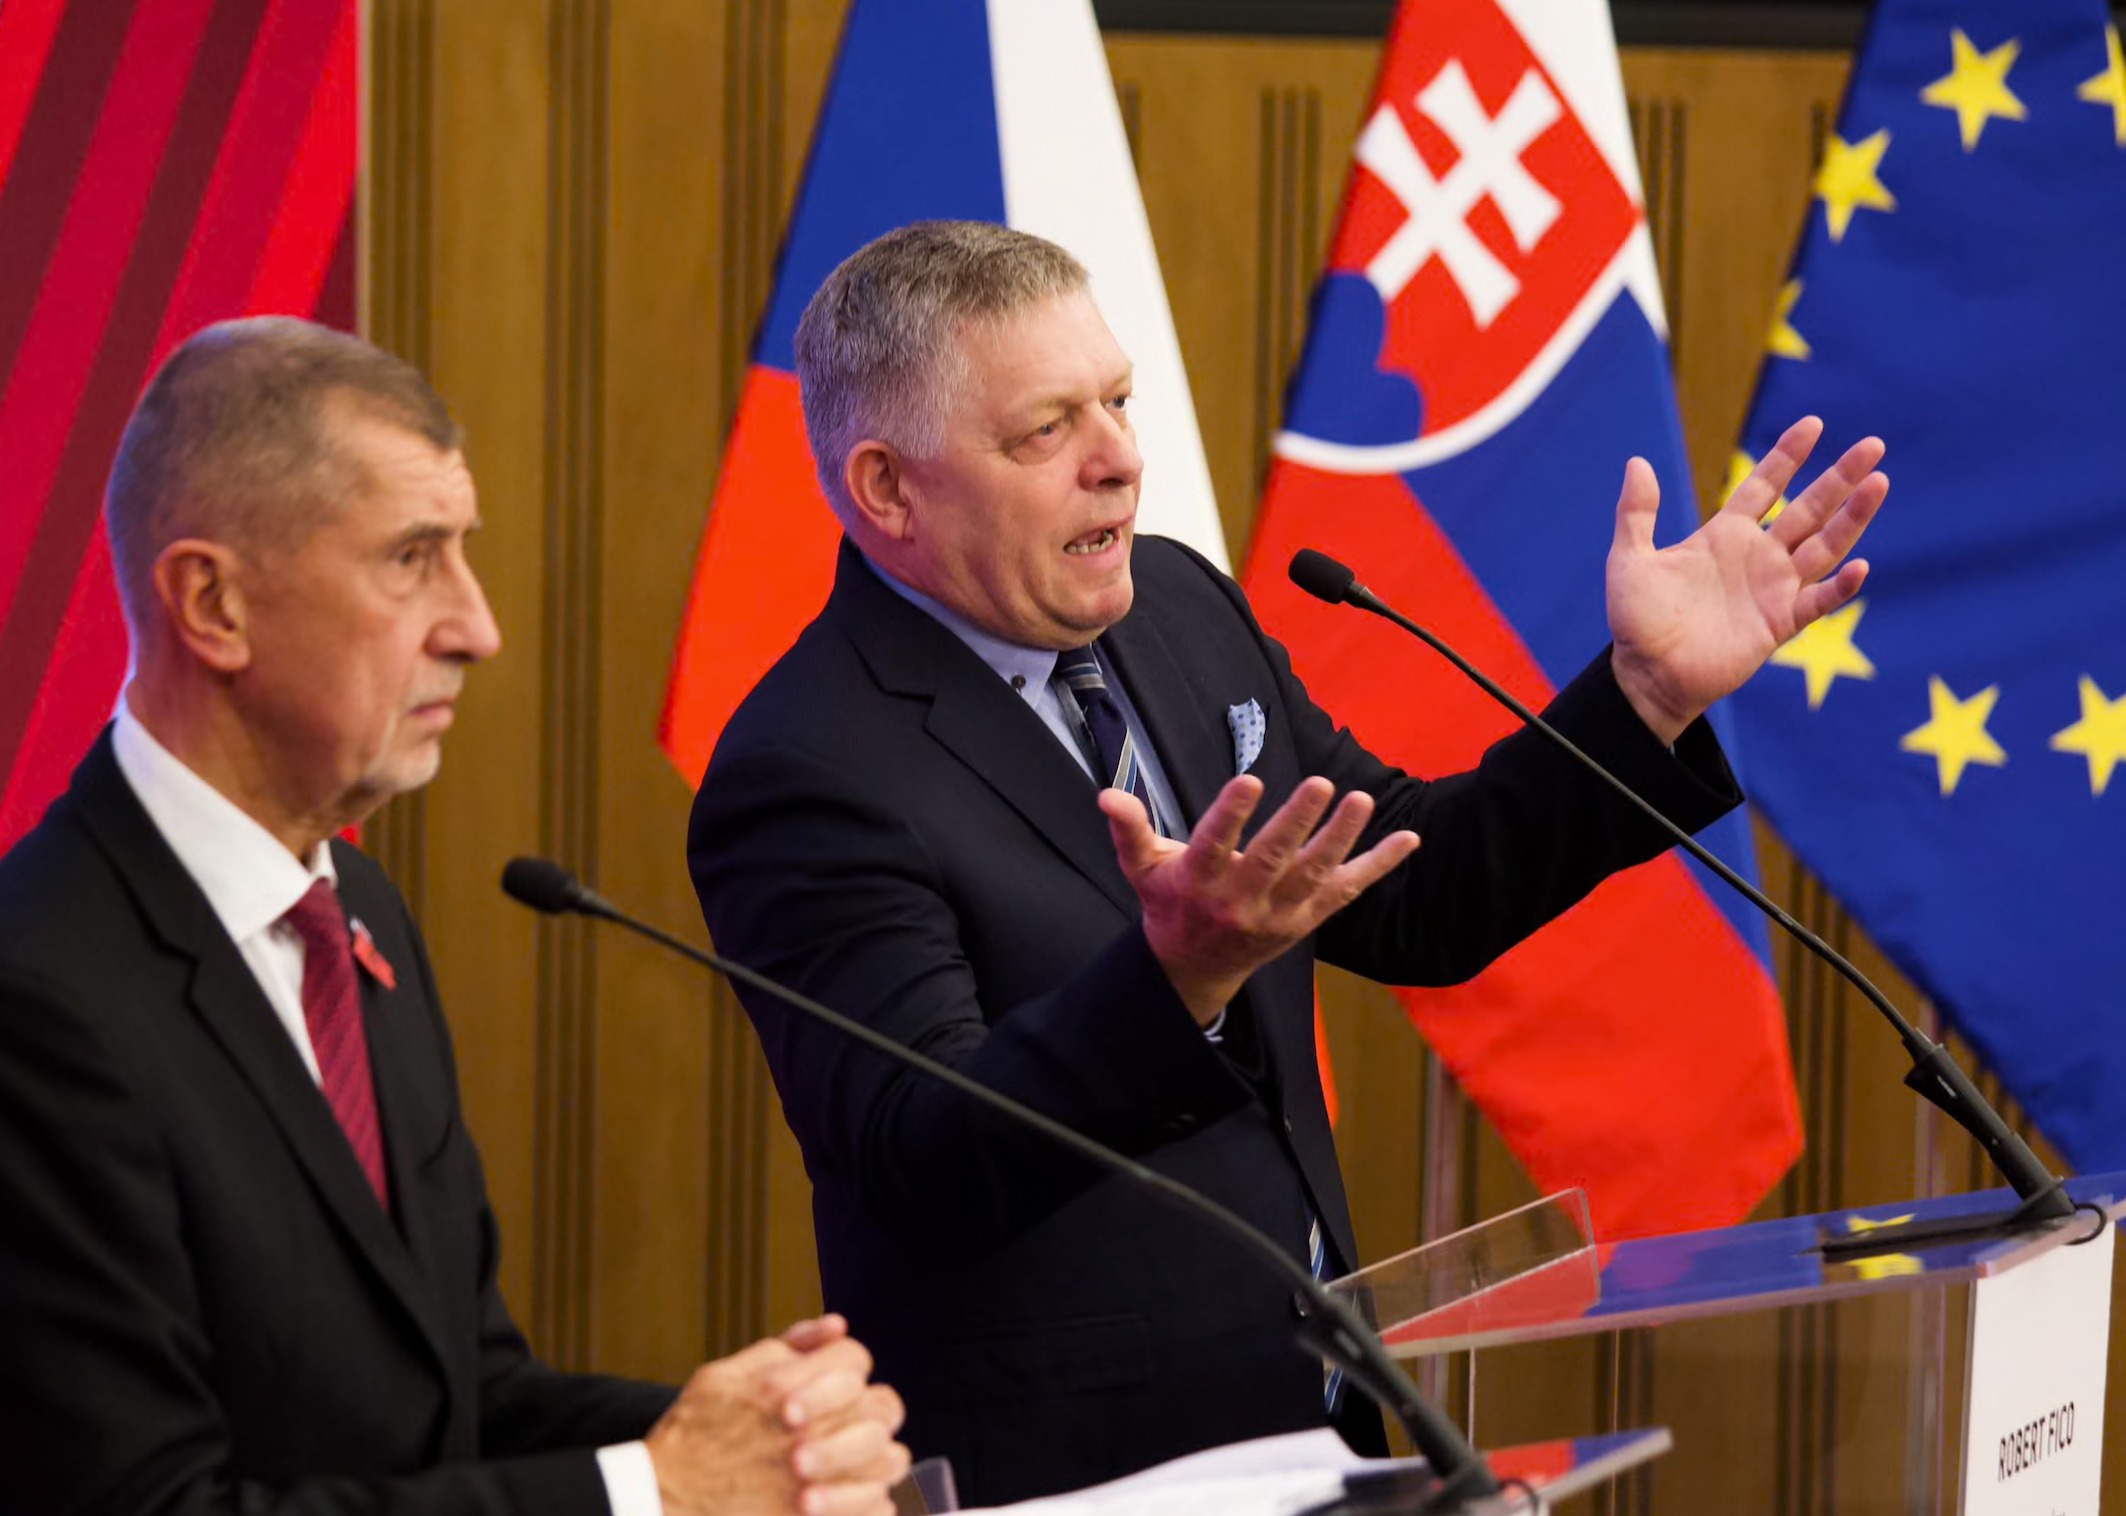
Slovak Prime Minister Robert Fico has hit back after German Chancellor Friedrich Merz threatened to veto the EU budget unless funding for Ukraine is secured.
Merz said he would block the EU’s seven-year budget if no agreement is reached on financial assistance for Ukraine.
The chancellor’s intervention has angered Central European leaders who are net beneficiaries of EU funds but do not want to take part in the next round of funding to support Ukraine’s war effort.
“What the chancellor is doing is typical blackmail, and I will not bow to it,” Fico told reporters in Bratislava.
Fico spoke alongside his Czech counterpart, Andrej Babiš, whose government has refused to participate in a future loan to Ukraine.
“I do not know why he said this,” Babiš said, referring to Merz’s stance.
Merz wants EU leaders to discuss Ukraine’s financing needs at a summit in Dublin on Friday.
In a letter to European Council President António Costa, who will chair the meeting, obtained by The Guardian, Merz wrote:
“We must maintain our support for Ukraine in its struggle to defend itself. This is our shared vital interest. Yet bilateral aid provided to Ukraine is distributed unevenly, with the burden shouldered mostly by only a few member states.”
The EU agreed last year to provide a €90 billion loan to Ukraine, intended to cover two-thirds of its military and civilian spending for 2026 and 2027.
Since then, however, Russia’s relentless bombardment has placed a heavier financial burden on Kyiv, prompting President Volodymyr Zelenskyy to ask for €70 billion to plug the budget deficit.
The EU has endorsed Zelenskyy’s figures and pledged to find €45 billion. Ukraine’s other allies, such as Britain and Canada, are expected to cover the rest.
Last year, Merz launched an initiative to tap €210 billion in frozen Russian state assets held in the EU, but the plan fell through due to opposition led by Belgium, which holds most of the funds in Brussels.
The €90 billion loan was the backup plan. Having opted out of that loan, Hungary, Slovakia, and Czechia indicated that they would not take part in the next round either.
Bulgaria joined these three member states following the election of Prime Minister Rumen Radev last April.
The question of funding for Ukraine is now spilling over into the fraught negotiations on the 2028-34 EU budget.
Germany, the largest net contributor, wants substantial cuts to the proposed budget and opposes the EU providing generous funding to member states that refuse to contribute to Ukraine’s financial needs.
Merz states in his letter that a “collective commitment without exceptions” is a “fundamental prerequisite” for closing Ukraine’s financing gap and for “discussing other matters, particularly those with financial implications.”
He also notes that, in the context of the EU’s next seven-year budget, known as the Multiannual Financial Framework, all member states must contribute to a “robust” financial perspective for Ukraine from 2028 onwards.
A German government official said:
“For the Multiannual Financial Framework (MFF) to be successfully concluded, it is vital that all EU member states provide financial support to Ukraine.”
Berlin is also aiming to shift decision-making on funding for Ukraine from unanimity to qualified majority voting, in an effort to prevent a single government from blocking EU decisions.
The letter reflects mounting frustration among the EU’s northern member states, Ukraine’s most generous backers, over lower contributions from other EU countries in Central and Southern Europe.
The task of brokering an agreement on the budget falls to Costa, the former Portuguese prime minister.
Costa wants a deal by the end of the year, ahead of elections in France, Poland, and Italy in 2027 that could complicate the process.
A spokesperson for Costa confirmed receipt of the letter without elaborating on details. “President Costa will dedicate time to the Ukraine issue at the informal European Council meeting in Dublin this week,” the spokesperson said, adding that funding for Ukraine would be addressed at a dedicated summit on the EU budget scheduled for 26-27 November.
The EU expects the next Israeli government to mend its “difficult relationship” with Brussels and adopt a more constructive approach toward Gaza and illegal settlements.
Israeli President Isaac Herzog tasked Gadi Eisenkot, the leader of the anti-Netanyahu bloc, on Sunday with forming a government.
Eisenkot stated that the country faces a “catastrophic diplomatic crisis” as traditional allies begin to reassess their relations with Israel.
Speaking to Rapporteur, several European diplomats stationed in Tel Aviv said they expect ties to get back on track.
“Whatever government comes in, we can try to revitalize relations because Israel is clearly a very important partner,” one European diplomat said, adding that Brussels expects the next administration to be “less aggressive”.
The diplomat noted that relations with Europe are currently “not very good”.
Israel cut off communication with Kaja Kallas, the EU high representative for foreign affairs and security policy, after Rapporteur revealed in June that she had compared Israel to apartheid-era South Africa during a visit to Mexico.
The diplomat stated that this decision, taken ahead of elections, was political in nature. A second European diplomat based in Brussels explained that the announcement came only a few days before an official visit by Dubravka Šuica, the European commissioner for the Mediterranean.
“This could have been interpreted as a tactic to divide Europe, but Israel had asked Kallas to deny the report; she did not do so,” the second diplomat said.
Brussels has repeatedly voiced its frustration with Israel over the humanitarian crisis in Gaza and the expansion of West Bank settlements.
However, EU governments blocked almost all sanctions proposed by the European Commission.
A third diplomat said opposition parties would “almost certainly take the issue more seriously” when it comes to tackling violence by West Bank settlers:
“We see Palestinians being expelled from their homes and new illegal settlements being built in the West Bank. There is a reluctance on the part of the current government to address this issue, which causes problems in our relations.”
The new government is expected to ease pressure on Palestinians and halt construction of the E1 settlement project, a controversial plan to build settler housing in the West Bank east of Jerusalem.
“They will probably try to deal with the problem of extremist settlers in the West Bank,” the diplomat added.
On Gaza, the diplomat described the situation as “a complete nightmare”, with two million Palestinians crowded into an area that accounts for roughly 35% of the territory.
“There are not enough tents for the winter, and not enough vaccines are reaching the area despite an increase in diseases,” the diplomat said.
The European official argued that Donald Trump’s peace plan met all the conditions for Europe. Although the EU had much to offer, neither the US nor Israel appeared interested in EU involvement in the process.
“We are currently training Palestinian police in the West Bank, and if permitted, we could do the same in Gaza,” the diplomat said.
The diplomat disclosed that Israel had agreed with Šuica that Europe would finance two projects aimed at improving sewage and water infrastructure in Gaza, continuing:
“However, none of these projects has started yet because there is a serious problem with dual-use goods. Getting materials into Gaza is very difficult because the Israelis say they could be misused if they fall into the wrong hands of Hamas.”
Israel insists that Hamas must be disarmed before subsequent phases of Trump’s plan can proceed.
With disarmament unlikely to happen in the near term, the EU argues that certain measures can be carried out in parallel.
“We can begin rebuilding sanitation systems in Gaza. We can start building desalination plants. We can begin providing energy and water to Gaza,” one diplomat said.
While Brussels hopes for progress on Gaza and the West Bank, it maintains that expectations regarding the establishment of a Palestinian state need to be “managed”.
The EU continues to advocate a two-state solution, yet most leading Jewish parties oppose the creation of a Palestinian state.
The diplomat noted that the next Israeli government will likely have “a very slim majority and not much room for manoeuvre”.
There is also a “major misunderstanding” between the EU and Israel that must be addressed. According to the diplomat, Europeans fail to recognize the “psychological impact” of 7 October on Israelis.
“This event changed the country and made the two-state solution even more distant than before,” the diplomat said.
In return, some Israeli politicians believe Europe has betrayed Israel despite what they view as a fight against “Islamist terrorism”.
“Their argument is that European politicians are somewhat afraid of the Muslim population in Europe,” the European diplomat said.
Europe strongly opposes Iran and the possibility of Tehran acquiring nuclear weapons, imposing sanctions in response.
However, the diplomat argued that the EU would not participate in a war because it lacks a common army:
“We are a diplomatic and economic power, which is why we resort to sanctions and diplomacy. The expectation that we would take part in a military operation is unrealistic.”
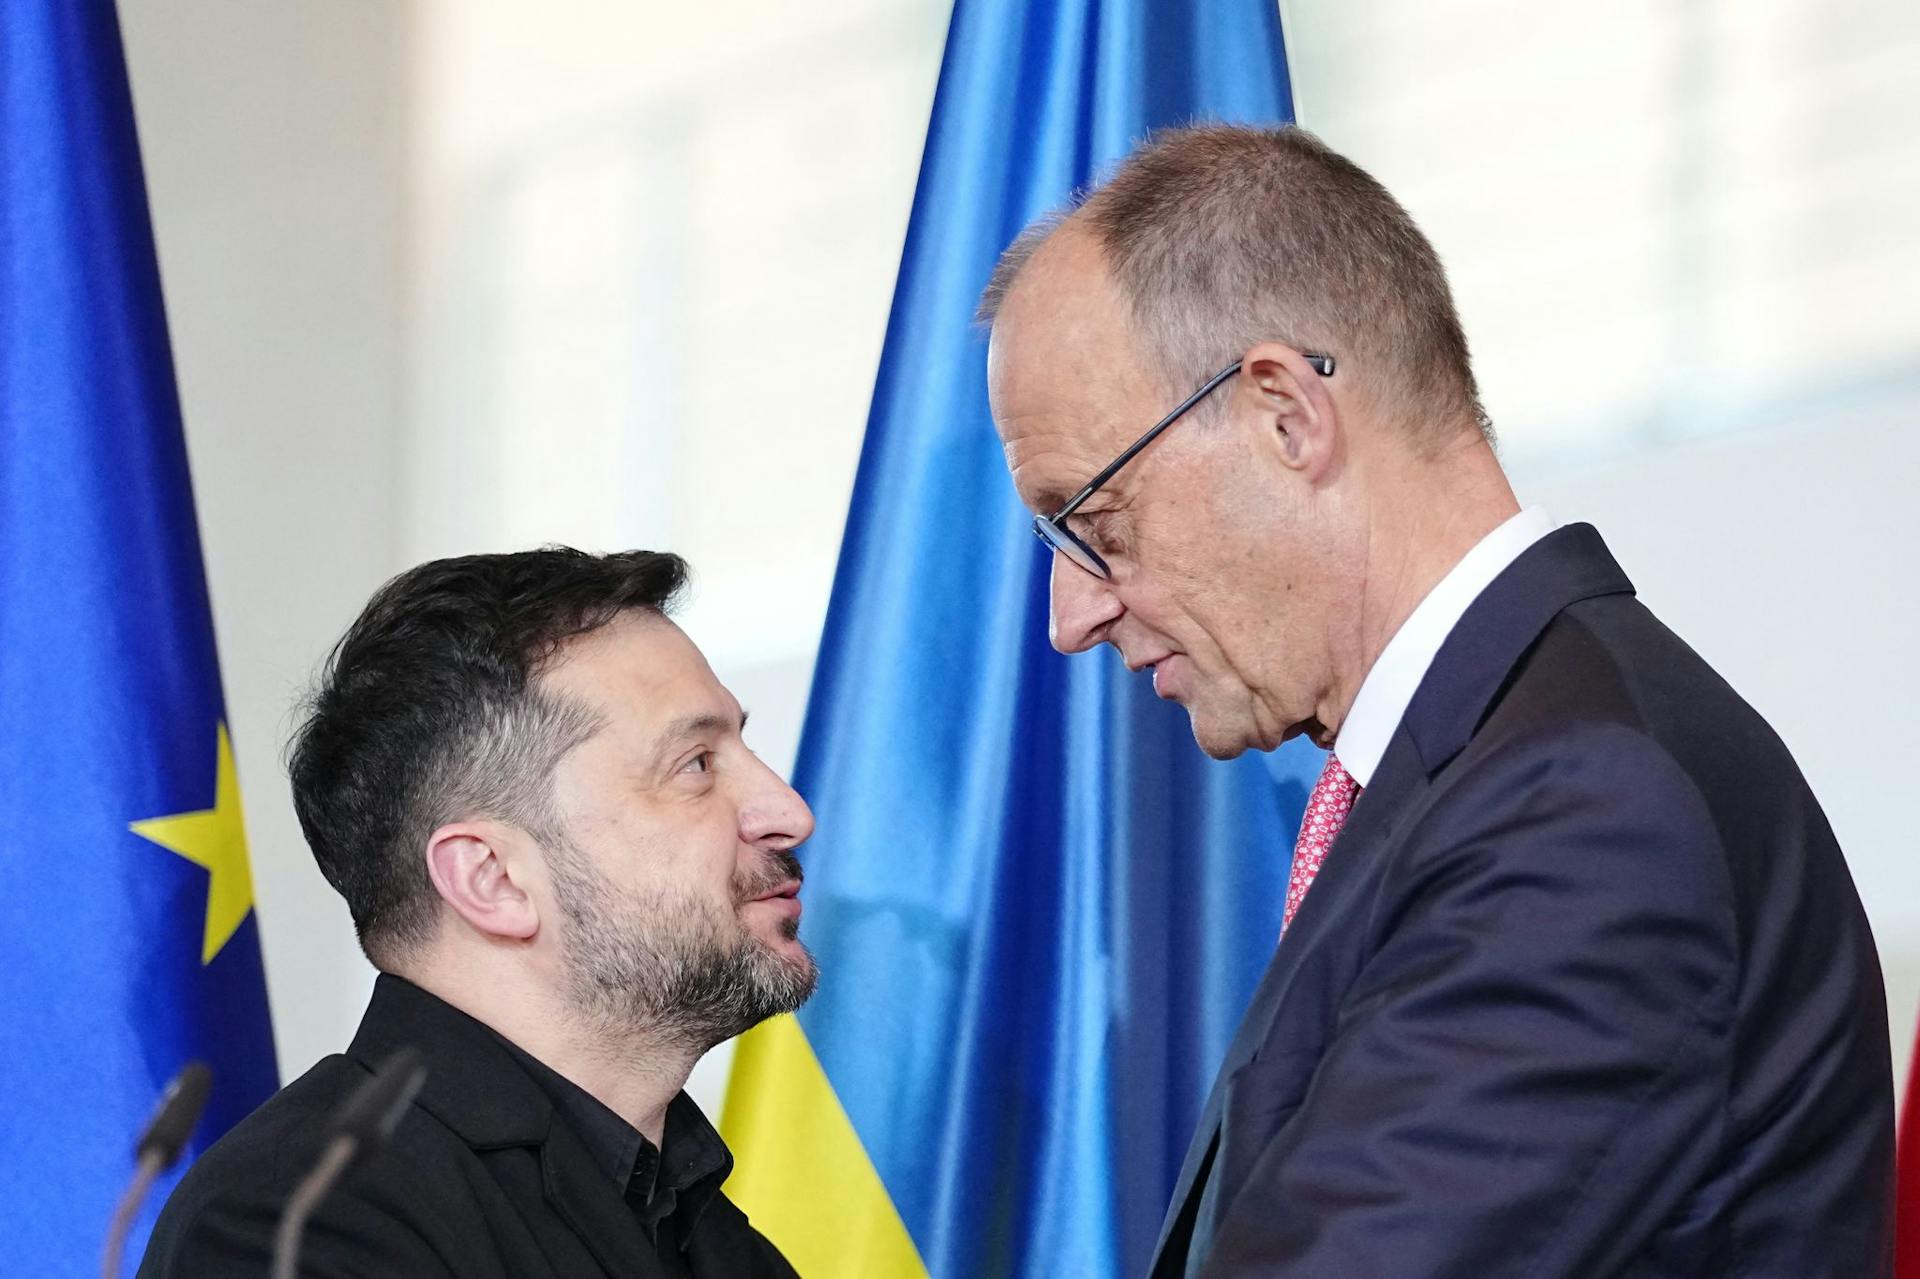
Germany has threatened to veto the European Union’s joint budget for the 2028-2034 period, which is currently under negotiation, unless every member state commits to providing financial support to Ukraine in 2027 and subsequent years, German Chancellor Friedrich Merz warned.
According to a report by the Financial Times (FT), Chancellor Merz set out Berlin’s condition for the budget talks in a letter addressed to European Council President António Costa.
In his letter, Merz wrote: “A collective commitment that every single one of us, without exception, will make a fair contribution to closing Ukraine’s budget deficit is an indispensable prerequisite for resolving this budget issue and, in particular, for addressing subsequent matters that carry financial implications.”
The German Chancellor stressed that a formula backed by all member states must be established to provide Ukraine with a reliable, multi-year financial perspective starting from 2028.
Merz also insisted that any agreed solution must cover the interest payments on debts incurred to finance the assistance provided to Kyiv.
Conversely, several countries within the bloc have cut financial aid to Ukraine, and the number of capitals adopting this stance is projected to rise next year.
In December 2025, Hungary, Slovakia, and the Czech Republic approved the EU’s 90 billion euro loan package for Kyiv only on the condition that they would not contribute to its costs themselves.
Alongside these three countries, Bulgaria has also stated that it does not plan to participate in subsequent financial assistance packages for Ukraine.
In France, far-right leader Marine Le Pen, who could potentially win the presidential election scheduled for spring 2027, recently told the FT that Paris has run out of funds.
Le Pen assessed: “The honest approach is to tell Mr Zelensky clearly, and even warn him: ‘Look, we cannot do more. We have already allocated the 90 billion euro EU loan, in which France’s share amounts to 18 billion euros. 18 billion euros is genuinely a huge amount of money.'”
The EU’s 90 billion euro loan, covering the 2026-2027 period, aims to meet two-thirds of Ukraine’s financing requirements.
Brussels expects the remaining 45 billion euros to be covered by other partners, including Canada, the UK, Norway, Japan, South Korea, and Australia.
Germany remains the largest net contributor to the EU budget.
In contrast, the four Eastern European countries seeking to avoid financing Ukraine rank among the largest net beneficiaries of the bloc’s budget.
Leveraging this balance, Chancellor Merz aims to use his influence in the EU budget negotiations to secure uninterrupted support for Kyiv in 2027 and the years beyond.
According to the FT, Berlin is also demanding that future aid packages be decided by qualified majority voting rather than unanimity, which is required under the current system.
A German government spokesperson told the newspaper:
“The issue of Ukraine’s financial needs must be resolved within the framework of the next EU budget. Financial support for Ukraine from all EU members is decisive for the successful conclusion of the budget talks.”

IRAM expert Oral Toğa assesses Middle East shifts after US vote

Netanyahu Arab party attack triggers crisis over coalition

Fico accuses Merz of blackmail over threat to veto EU budget

US Senate panel seeks records in Trump-linked crypto investigation

Europe ready for arms and missile control talks with Russia, FT says
-
 Diplomacy1 week ago
Secular dress code dispute exposes deeper Türkiye-Azerbaijan strains
-
 Russia2 weeks ago
US and Russia weigh energy deals and corporate return in peace talks
-
 Europe2 weeks ago
Merz visits Asia to seek new markets for German defence firms
-
 Opinion2 weeks ago
Gaza exposes the myth of the “most moral army in the world”
-
 Middle East2 weeks ago
US warns Gulf allies of possible Iran strikes after midterms
-
 Europe5 days ago
EU urges citizens to prepare 72-hour survival kits for crises
-
 America2 weeks ago
Democrats target Trump-Putin Russian diesel deal with legal push
-
 America2 weeks ago
Bolsonaro reportedly leaves Brazil on jet linked to scandal-hit firm
