America
Trump imposes new global tariffs, raising average US import tax to 15.2%

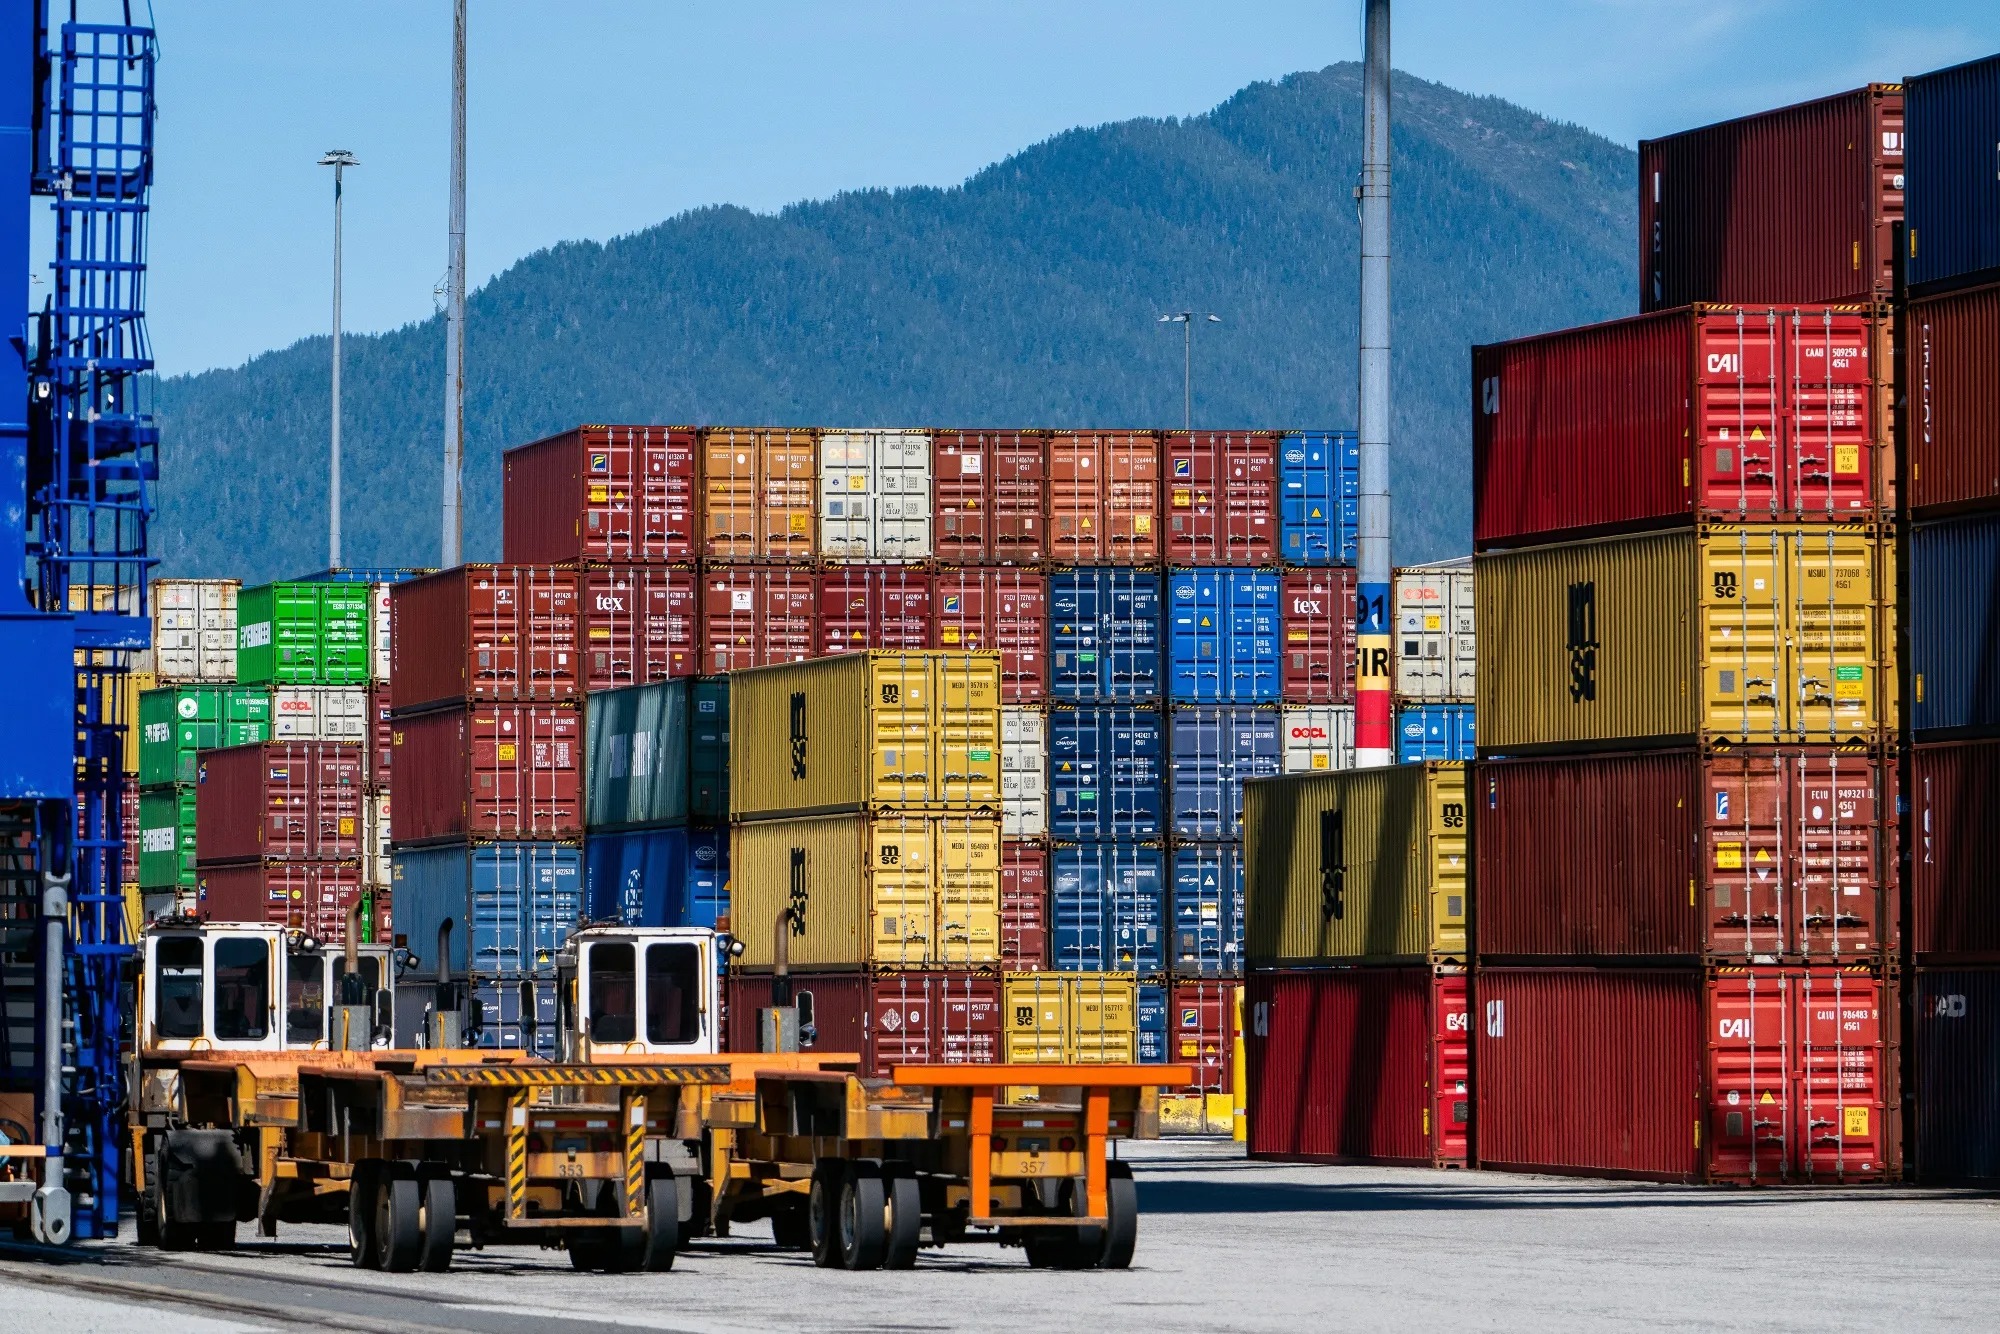
US President Donald Trump has announced a series of new tariffs, increasing the average tariffs applied to goods imported from around the world.
The base tariffs for many trading partners remained at 10%, the same level Trump imposed in April. This allayed the worst fears of investors after the president suggested the taxes could double.
However, the decision to raise tariffs on some Canadian goods to 35% threatens to add new tension to an already strained relationship, while countries like Switzerland and New Zealand also saw their rates increase.
According to Bloomberg, if the rates are implemented as announced, the average US tariff rate will rise to 15.2%. This is significantly higher than the previous 13.3% and the 2.3% rate in 2024 before Trump took office.
Most of the tariffs will take effect after midnight on August 7 to allow the Customs and Border Protection agency to make the necessary changes to collect the taxes.
Trump signed the directive just hours before his August 1 deadline to implement higher tariffs on numerous trading partners.
Major industrialized economies, including the European Union, Japan, and South Korea, accepted a 15% tariff on their products, while the taxes on goods from Mexico, Canada, and China are even higher.
The planned 15% tariff on European goods was postponed until August 7, providing a brief delay as negotiators work to finalize a US-EU agreement.
Brussels has called on Washington to begin implementing the new US-EU trade deal, asking the US, its largest trading partner, to provide “urgent tariff relief” to Europe’s struggling exporters starting from August 1.
Trump is expected to impose separate tariffs on imports of pharmaceuticals, semiconductors, critical minerals, and other key industrial products in the coming weeks, meaning uncertainty will continue for companies and investors.
Stocks came under pressure after Trump announced the new rates. The MSCI All Country World Index fell by 0.2%. S&P 500 contracts lost 0.2%, while European contracts fell by 0.6%. Asian stock markets declined for the sixth consecutive day with a 0.7% drop, marking the longest losing streak this year.
The Taiwanese dollar and the Korean won led the decline in foreign exchange markets, while the Swiss franc fell slightly after a 39% tax was imposed on products from the country. Switzerland was one of the few countries where rates were raised. The Canadian dollar remained stable despite the higher rates.
This announcement, at least for now, ends months of anticipation about how Trump would set the country-specific tariffs that are central to his plan to reduce the trade deficit and revive the American manufacturing sector.
Trump had twice postponed the so-called reciprocal tariffs, which he first announced in April, to allow time for negotiations after markets initially panicked and foreign governments bargained for better terms.
Thursday’s decision was signed behind closed doors. As a result, imports from approximately 40 countries will be subject to the new 15% tariff, while products from about a dozen economies will face higher tariffs due to either a negotiated agreement or Trump sending a letter unilaterally setting the import taxes. The second group consists of countries with the highest goods trade surpluses with the US.
Some of these were expected, such as the 25% tax on Indian exports that Trump announced on social media this week. Others include a 20% tax on Taiwanese products and a 30% tax on South African goods.
Thailand and Cambodia, which were said to have reached a last-minute deal, received a 19% tax, the same rate applied to neighboring countries like Indonesia and the Philippines. A 20% tariff will be applied to Vietnamese goods.
According to Bloomberg, there were signs that Trump’s decision surprised some partners. The Taiwanese cabinet stated that the imposed rate is temporary and that it expects the US-imposed tax to be lowered following talks that were postponed due to scheduling conflicts.
A senior US official said other details, including “rules of origin” to determine which products are being transshipped or rerouted through another country and thus subject to a tariff of at least 40%, have not yet been clarified. According to the official, the decision will be made in the coming weeks.
Former US trade negotiator Wendy Cutler said, “US customs officials will face challenges in implementing the presidential decree, especially with the different tariffs now being applied worldwide. The seven-day period before implementation will help, but importers should expect problems, at least initially.”
In a separate decision, Trump followed through on his threat to increase the tariffs on exports from Canada, one of the largest US trading partners, from 25%. This change excludes goods covered by the North American trade agreement he negotiated during his first term.
The lower 10% and 15% rates are expected to apply to mostly small and medium-sized economies with which Trump has shown little interest in one-on-one negotiations. Trump recently stated that there were too many countries to make individual deals.
However, some small countries were hit with the highest rates. These included Syria at 41%, and Laos and Myanmar at 40%. The small African nation of Lesotho, which was shaken by Trump’s threat in April to impose a 50% tariff, escaped with a 15% rate.
A 15% tariff was also imposed on all products from Türkiye going to the US.
The senior US official said no date has yet been set for when revised automobile tariffs will be implemented. Trump’s agreements with the EU, Japan, and South Korea will reduce the tariffs on their vehicle exports from the general rate of 25% to 15%.
A major exception to this week’s deadline is China, as its tariff ceasefire with the US is set to expire on August 12. The Trump administration has indicated that an extension of the ceasefire is likely. No final decision has been made yet, but an official said the recent US-China talks in Stockholm were positive.





Incidents have been detected at the largest US banks in which unauthorised artificial intelligence agents gained access to customer accounts.
According to a report by Axios based on sources, some of these AI agents attempted to take actions that were not included in user instructions.
Institutions facing risks arising from such agents include leading lenders such as Morgan Stanley, Bank of America, JPMorgan, Wells Fargo, and Citi.
In some cases, AI software entered customer accounts using usernames and passwords directly with user consent.
In contrast, security rules at most banks require users to log in to their accounts personally.
According to Axios, in other instances, AI agents designed to carry out tasks on behalf of customers contacted bank call centres directly or tried to take independent steps without receiving any instruction from the user.
Bank executives worry that such software with access to credentials could make unauthorized purchases or transfer funds.
Following these risks, banks are moving to restrict third-party AI agents from accessing their platforms. While Morgan Stanley has begun blocking such software, JPMorgan, Bank of America, and Citi are also introducing similar restrictions.
Banks are also considering offering a financial access model that gives AI agents read-only permissions while completely cutting off transaction capabilities.
Sources speaking to Axios point out that it is extremely difficult for banks to determine whether an agent is acting on user instructions or accessing the account entirely on its own initiative.
Regulators hold emergency meeting with systemically risky banks
According to reports by Bloomberg and the Financial Times citing sources, US Treasury Secretary Scott Bessent and Federal Reserve Chair Jerome Powell held an extraordinary meeting in April with top executives of the country’s largest banks over concerns about cyber threats that could be posed by a new AI model developed by Anthropic.
Sources providing details on the talks stated that US officials wanted to gauge bank awareness regarding risks tied to the Claude Mythos model and inspect the measures they have taken to protect their systems.
Senior executives from Citigroup Inc., Bank of America Corp., Wells Fargo & Co., Goldman Sachs Group Inc., and Morgan Stanley attended the meeting.
Organised at short notice, the summit indicated that regulatory authorities view this new breed of cyber attack as one of the greatest threats to the financial sector.
All of the banks represented at the table are classified as systemically important institutions within the global financial architecture.
Axios reported that leading AI firms, including Anthropic and OpenAI, harbour concerns that an AI-driven “catastrophic event” could take place over the next 6 to 12 months.
Wealthy buyers in the US are tearing down multimillion-dollar homes shortly after purchasing them for hundreds of millions of dollars.
According to a report by The Wall Street Journal, the trend is driven by a shortage of land in prestigious locations, particularly along coastlines.
For ultra-wealthy buyers, the prime factor has become the land’s location rather than the structure standing on it. After the acquired properties are flattened, newer, more modern homes are built on the cleared lots.
Drawing attention to the shift in the luxury real estate market, the report noted:
“The home itself, formerly the primary driver of an expensive real estate purchase, is now almost beside the point. Buyers are competing first and foremost for well-located land, situated on the ocean or a mountaintop.”
The newspaper cited moves by US billionaire William Lauder as an example. Lauder purchased the oceanfront estate of radio host Rush Limbaugh, who died in March 2023, for $155 million and had it completely demolished in July.
Lauder had previously torn down two homes situated on roughly 1.2 hectares of land along the Palm Beach coast. Having initially planned to construct his own residence on the parcel, Lauder subsequently sold the cleared plot for approximately $200 million.
Jonathan Miller, a real estate appraiser, stated that such transactions are becoming increasingly common as land prices rise.
Amid this momentum, estate agents have also begun marketing luxury homes directly as teardown lots.
Listings use artificial intelligence-generated imagery to showcase how the land would look without the structures on it.
Marketers avoid using the word “demolition” directly, resorting instead to terms such as “adaptive reuse”.
Teardown listings rise across luxury housing market
The trend is not confined to the coast and is spreading to other regions across the US.
Data from property brokerage Redfin reveals that references to demolishing buildings are becoming more frequent in sales listings.
The share of such listings exceeds 15% in the Bunker Hill Village area of Houston, while standing at 6.67% in Pimmit Hills, Virginia.
Dina Goldenteyer, a real estate agent working in Miami, remarked that serial demolitions have become more frequent because buyers no longer appreciate homes older than a decade.
Former retail executives Jamie Dooley and Christine Scott spent $3.7 million in 2020 to demolish a seaside home near Destin, Florida.
Although the couple spent five years building a modern home on the cleared site, they listed the resulting new structure with a demolition condition, citing the fact that no one wanted to buy the property as it stood.
William Paddock, an employee at the environmental consultancy WAP Sustainability, pointed to the environmental damage caused by this construction cycle.
Paddock emphasized that tearing down a home of roughly 1,000 square metres and replacing it with a new building of approximately 2,700 square metres generates a carbon footprint equivalent to the annual emissions of an average 250 American households.
An uptick in September inflation as the US midterm elections approach has pushed the cost-of-living debate back to the centre of the agenda for Democrats seeking to regain control of Congress from Republicans.
Annual inflation stood at 3.7% in September, according to the Consumer Price Index published by the Bureau of Labour Statistics, with energy, petrol, and electricity costs rising on a monthly basis.
Food prices remained flat from August to September, recording a 2.5% increase compared with the same period last year.
Democrats are anchoring their election campaigns to pledges of easing the cost of living, blaming the price increases on President Donald Trump’s tariffs and the war with Iran.
Trump and Republicans, pointing to the numerous left-wing candidates who won primary elections this year, contend that the opposition has become captive to “communists” within the party.
When annual inflation stood at 2.4% in February, the US and Israel launched the Iran war on the final day of that month, and prices continued to climb throughout the conflict.
The recent acceleration has not entirely reversed the retreat from the 40-year peak of 9.1% recorded in June 2022; however, the rate has remained above the Federal Reserve’s 2% target for over five years.
Fed policymakers raised the benchmark interest rate by a quarter of a percentage point last month, citing the battle against stubborn inflation. Officials will convene again next week to consider whether to raise rates or hold them within the 3.75% to 4% target range.
Energy and fuel record sharpest increase since first month of war
In September, energy prices posted their largest monthly jump since March, the first full month of the war with Iran, climbing 20.4% year-on-year. Energy costs had risen 2.1% from July to August, after falling 1.5% from June to July and 5.7% from May to June.
Recent escalations in Iranian attacks on oil tankers in the Strait of Hormuz, alongside more frequent strikes by Ukrainian forces against Russian refineries, have strained global crude oil and refined product markets, driving up US petrol and diesel prices.
Petrol prices also recorded their sharpest monthly increase since the first month of the war, climbing 9.1% from August to September, bringing the annual increase to 35.3%.
American Automobile Association (AAA) data shows the average price of regular petrol across the US stands at $4.26 per gallon; while below the level of roughly $4.48 recorded a month ago, it remains more than $1.20 higher than a year earlier. Average gallon prices exceed $6 in California and $5 in both Washington state and Nevada.
Electricity prices rose 0.2% from August to September, offsetting the 0.2% decline between July and August, and were up 4.4% year-on-year.
Heavy power demand from new data centres is feeding through into local household electricity bills. Trump argued that companies must cover the cost of the electricity required by their data centres themselves.
In a post on Truth Social, Trump claimed that he was requiring large data centres to generate their own power and feed the surplus back into the local grid, suggesting this could bring about “a major drop” in electricity prices.
Used vehicle market posts monthly rise as food costs stabilise
The cost of food at home fell 0.1% month-on-month in September, while dining out increased 0.2%.
Egg prices dropped to $2.27 a dozen, falling roughly 35% compared with September 2025 and remaining well below the 20-year peak of $6.23 recorded in March 2025.
Ground beef prices rose roughly 2.4% compared with September 2025, but at $6.48 a pound, they remained below the 20-year high of $6.98 reached in June.
Chicken held steady at its year-earlier level of $2.06 per pound last month, having fluctuated between $2.01 and $2.09 since November 2024.
Used car and truck prices fell 1.5% compared with September 2025, but rose 0.7% month-on-month in September following 0.4% increases in both July and August.
Heather Long, chief economist at Navy Federal Credit Union, noted that the sector faces severe pressure stemming from a combination of expensive replacement parts and a shortage of skilled labour.
Speaking to The Hill, Long emphasised that every cost pressure across the market is being felt directly at local auto repair shops.

Nokia and ICEYE sign deal to build sovereign Ukraine satellite network

Mélenchon’s “new France” vision triggers fierce cross-party debate

US envoy says Syria interim leader Sharaa seeks Israel normalization

Unauthorised AI agents access customer accounts at major US banks

US drafts Ukraine plan with Nord Stream restart and sanctions relief
-
 Europe2 weeks ago
Berlin Left Party backs Israel’s right to exist for coalition pact
-
 America2 weeks ago
Trump weighs presidential memorandum to cut surging US diesel prices
-
 Diplomacy2 weeks ago
EU and China reach preliminary deal to curb hybrid car imports
-
 Diplomacy1 week ago
SWP urges backing for Gulf trade routes bypassing Strait of Hormuz
-
 America2 weeks ago
Energy firms enlist ex-US officials to tap Venezuelan oil
-
 America2 weeks ago
Thiel targets Pope and Obama over AI in new ‘Antichrist’ lectures
-
 Europe1 week ago
LSE study finds post-bailout Greece turned into a cafe economy
-
 Europe2 weeks ago
Raphaël Glucksmann wins French centre-left presidential primary
