America
Global balance sheet hits $1.8 trillion as asset values decouple from real economic output, McKinsey report says

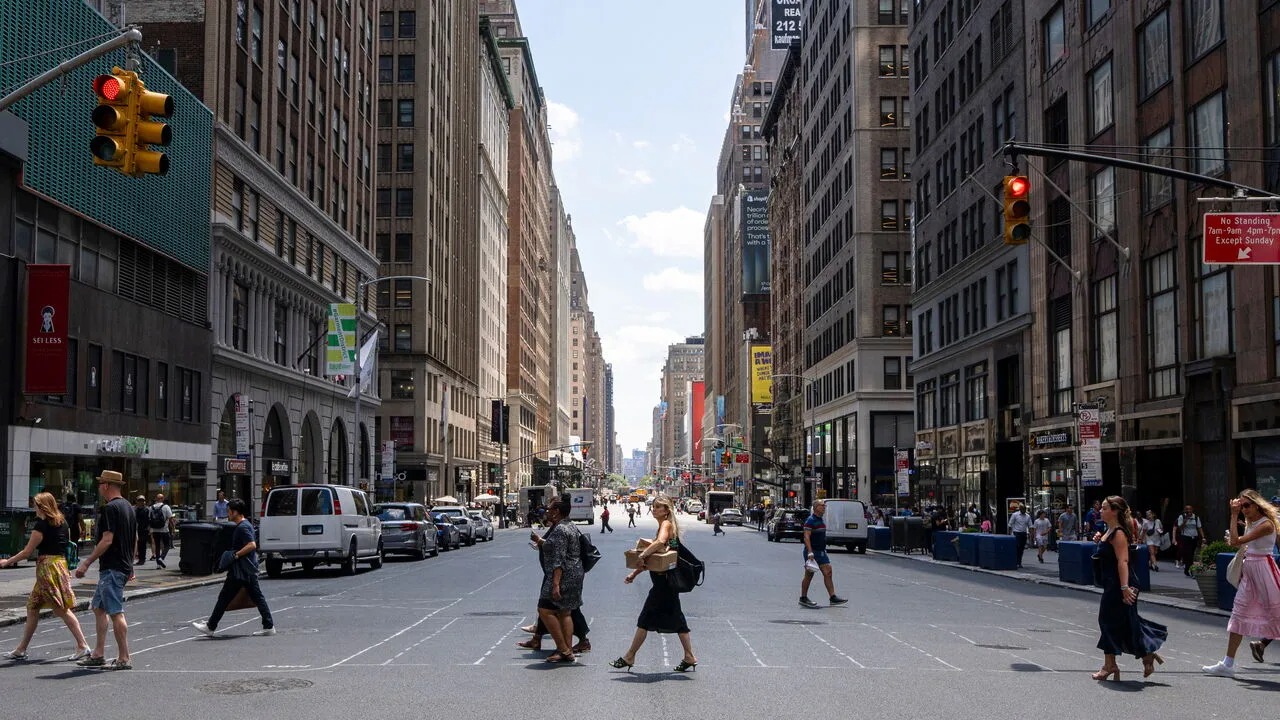
The global economic balance sheet reached approximately 1.8 quadrillion (1,800 trillion) in 2025, rising from $1.7 quadrillion in 2024.
According to a report published by McKinsey, the world is wealthier than ever before. However, this wealth relies on increasingly inflated valuations of paper assets rather than real output. How this contradiction resolves itself will determine the future of the world’s leading economies, the report stated.
The report noted that several asset classes have further expanded their imbalance with the “underlying” economy. This dynamic heightens the probability of corrections occurring through inflation, asset valuation losses, or, in the best-case scenario, productivity gains.
Unlike growth in the capital stock that generates real output, the tendency to rely on elevated valuations fuels the risk of a painful correction—either through falling asset prices or prolonged inflation.
Nevertheless, a more optimistic scenario exists in which the world essentially grows into these high asset valuations, supported by an artificial intelligence-driven productivity boom.
Researchers found that global household wealth reached $570 trillion, representing a $40 trillion increase compared to 2025.
Yet only 20% of this increase stemmed from genuine capital accumulation—namely net new investments in machinery and equipment, housing and buildings, infrastructure, and intellectual property.
The remainder was driven by a combination of inflation and price appreciation in the market value of existing assets.
In the US and Canada, equity values served as the primary driver of wealth expansion. In China, France, and Germany, paper wealth declined under the weight of falling real estate prices. In the UK and Japan, inflation pushed asset values higher.
This marks a more extreme iteration of a long-standing trend: from 2000 to 2024, net investments accounted for 30% of global wealth growth.
Examining the structure from the baseline up, real assets encompass real estate, infrastructure, machinery and equipment, and intellectual property owned by households, governments, and corporations. These carry a combined value of $620 trillion and constitute global net assets across all sectors.
Financial assets held outside the financial sector include equities, bonds, loans, foreign currency and deposits, and pension funds. Every financial asset carries a corresponding liability, and these balance each other out on a global level.
This “financial layer” functions to separate wealth from asset ownership and stood close to the total value of real assets.
The financial sector, meanwhile, intermediates between these financial assets and liabilities. With a volume of $550 trillion, the financial sector has reached 90% of the value of real assets.
Wealth is ultimately the balancing item on balance sheets, equaling the difference between total assets and liabilities. This stood at $600 trillion in 2025.
In 2025, the growing detachment of balance sheets from the real economy was driven by the world’s two largest economies.
With the share of corporate profits in GDP doubling since 2000, US equity valuations rose to 2.4 times the net asset value of corporations.
In China, corporate debt reached 80% of real assets, compared to a global average of 50%.
US public debt is hovering near all-time highs, while the fastest increase was recorded in China.
On a global scale, a major share of corporate and household debt, as well as real estate assets, approached 25-year averages relative to GDP.
Inflation contributed to this normalization; however, values remain well above pre-2000 levels. Against a backdrop of flat investment, the ratio of productive assets to GDP remained stagnant.
Jan Mischke, a partner at the McKinsey Global Institute, told Axios: “We can now say that every asset on this planet has been financialized.”
There are several plausible paths through which these elevated asset valuations could uncoil. One is a simple “muddle through” approach: low growth leads to low interest rates, which allows high valuations to persist. This is roughly what occurred in major economies during the 2010s.
However, more dramatic possibilities exist—some positive, others alarming.
The best-case scenario for the global economy involves a productivity leap driven by AI or other sources that sparks a GDP boom, thereby justifying the high valuations of equities and other asset classes. This is essentially what occurred in the late 1990s.
A more pessimistic possibility is that sustained inflationary pressure erodes the real value of assets, forcing them back toward historical norms and leaving people poorer in real terms. This occurred, arguably, during 2021–2022.
The most concerning scenario is a global asset price reset of the kind witnessed in 2002 and 2008.
“Overstretched scenarios have a tendency to mean-revert, including in positive ways like productivity acceleration,” Mischke said. “But occasionally, you also get a major debt crisis or a market crash.”
Arvind Govindarajan, one of the co-authors of the report, posed the central question: “For us in the US, the real question is: Will productivity and GDP be higher—in which case we see a productivity boost—or will we slide into an inflationary scenario?”
Entering 2026, major economies followed diverging roadmaps, according to the report. The US operated under a “productivity acceleration” scenario, though high public debt and stretched equities keep the possibility of “persistent inflation” or a “balance sheet reset” on the table.
Europe drifted toward “secular stagnation,” as sluggish demand pulled down growth and interest rates.
In China, while a partial balance sheet reset unfolded amid falling real estate values, public spending and corporate investment continued to support balance sheet growth.



The US economy is projected to grow much faster than all other major advanced economies this year, as its domestic policies trigger difficulties across much of the globe.
According to Axios, the global economy has proved surprisingly resilient in the face of successive shocks.
The US stands out within this broader picture. A boom in artificial intelligence investment is helping the country expand far more rapidly than peer economies.
Yet this exceptional performance carries a price: more persistent inflation and interest rates that may need to stay at elevated levels for longer to rein it in.
The Organisation for Economic Co-operation and Development (OECD) projects that the US economy will expand by 2.2% this year.
That rate is roughly double the pace forecast for the eurozone, Germany, and the United Kingdom. Growth is expected to be even weaker in Japan (0.8%) and Canada (0.9%).
This growth gap is expected to persist next year. In 2027, US growth is projected to reach 2.1%, while growth across most other major advanced economies in the rest of the world is forecast to hover around 1%.
The OECD has grown more optimistic regarding the US since June, raising its growth forecast by 0.2 percentage points for 2026 and by 0.3 percentage points for 2027.
This trend contrasts with downward revisions to next year’s growth projections for the global economy overall, the eurozone, Canada, the United Kingdom, and Japan.
OECD Chief Economist Stefano Scarpetta told reporters this morning:
“The biggest risk remains the course of the conflict in the Middle East and its impact on the energy market. But there are a number of other risks, some of which appear to have become somewhat more pronounced compared to the June forecasts.”
Scarpetta highlighted rising government bond yields, the risks accompanying the AI investment boom, and the likelihood of extreme weather pushing up food prices.
According to the OECD, the boom in artificial intelligence (AI) has provided the US economy with a powerful shock absorber absent in most other economies.
Rapid growth in AI investment and manufacturing “partially offset” the economic blow dealt by the conflict in the Middle East.
Data centre and technology spending directly bolstered US growth.
The inflation outlook, meanwhile, is proving more stubborn than it appeared several months ago.
The OECD expects headline inflation in the US to fall from 3.6% this year to 2.6% next year.
However, this forecast for 2027 is half a percentage point higher than the figure projected in June.
Core inflation in the US is projected to stand at 3.3% this year, among the highest rates across leading advanced economies, before easing to 2.5% next year.
This stubborn path explains why the OECD expects the Federal Reserve to deliver one more interest-rate increase this year and anticipates rates will remain in the 4% to 4.25% range through the end of 2027.
On the other hand, the AI boom accelerating US growth is beginning to bring its own macroeconomic headwinds.
According to the OECD, long-term borrowing costs in most of these major economies are at their highest levels in at least 15 years.
The organisation argues that heavy borrowing by AI firms has contributed to pushing yields higher, which could elevate costs across the broader economy and leave markets vulnerable if AI profits fail to meet expectations.
America has contributed to making the global economic climate more challenging.
Even though its own economy has so far performed better than nearly all other countries, this resilience comes accompanied by an inflation problem that remains difficult to eliminate.
Republican backing from US President Donald Trump’s own party for the war he is waging against Iran is declining swiftly.
According to a CNN/SSRS poll published on 22 September, the proportion of Republicans who approve of Trump’s handling of the war dropped from 73% in March to 60% in September.
A majority of Republicans under the age of 45, as well as Republican voters outside the MAGA movement, no longer approve of Trump’s war policy.
Three-quarters of Americans believe that the Iran war is not worth its human and financial toll.
Regarding the war, which has been ongoing for roughly seven months, 78% of respondents stated that Trump is not making sufficient efforts to end the conflict. Approximately two out of every three people disagreed with the view that the US is winning the war.
Approval of Trump’s overall foreign policy stewardship remained at just 29%. This marked the lowest level recorded by CNN across Trump’s two presidential terms.
Share of those viewing Israel as an ‘enemy’ at record level
The proportion of respondents defining Israel as an enemy of the US rose to its highest point in CNN surveys conducted since 2000. This figure reached approximately double the level recorded in March 2025.
In a separate Reuters/Ipsos survey conducted among 1,277 adults, Trump’s overall approval rating slipped within a single week from 35% to 32%. This represented the lowest approval rating measured throughout Trump’s political career.
Discontent among Republican voters over the cost of living is also mounting. The proportion approving of Trump’s performance in this area stood at merely 17%.
While the cost of living remains the paramount issue for voters ahead of the 3 November midterm elections, the sharp surge in fuel prices since the onset of the war has exacerbated unease within the Republican base.
82% believe the war will be prolonged
Earlier this month, Trump said the war would conclude “right after” the elections. However, 82% of poll respondents believe the fighting will continue for a prolonged period.
Tehran, meanwhile, has shown no sign of backing down in the face of US military and economic pressure.
In a report published on 10 September, The Wall Street Journal revealed that US Vice-President JD Vance, Secretary of State Marco Rubio, and other senior officials had warned Trump in private discussions.
Officials reportedly said that Iran could continue resisting Washington’s military and economic pressure and withstand this coercion even beyond January 2029, when Trump’s term in office concludes.
In the debate surrounding the dangers posed by artificial intelligence, almost everyone is attempting to market a product.
While the mainstream media portrays artificial intelligence as an imminent mass extinction event, US President Donald Trump frames the issue within the context of a new Cold War with China, arguing that the US cannot afford to slow down.
In his analysis, journalist Ken Klippenstein emphasizes that Silicon Valley elites profit directly from this intense attention.
A new generation of the tech class is occupying the public mind with various doomsday scenarios, ranging from bioterrorism to machines taking over the world.
While this dynamic transforms artificial intelligence into a “national security” issue, it elevates the technology to the level of nuclear weapons and removes it from public oversight.
The intelligence community thinks the A.I. apocalypse narrative is BShttps://t.co/DpyAIXx4ob
— Ken Klippenstein (@kenklippenstein) September 15, 2026
Although not immune to the tendency to exaggerate threats, reports from US intelligence agencies paint a picture far removed from the hysterical tone in the media.
The US intelligence community assesses that artificial intelligence merely magnifies risks that already exist.
Sensational headlines run by legacy media are fueled by social media figures who spread claims of human extinction to millions of followers. In this way, fears themed around “existential risk” or “doomsday” take root in the public imagination.
On the other side of the coin are those who oppose disaster narratives while pursuing their own commercial interests.
Prominent figures in this camp include Yann LeCun, former chief AI scientist at Meta, and Andrew Ng, co-founder of Google Brain and head of AI Fund.
In October 2023, LeCun accused OpenAI chief Sam Altman, Google DeepMind chief Demis Hassabis, and Anthropic chief Dario Amodei of running a “massive lobbying effort” designed to tilt the regulatory landscape in their own favor.
LeCun warned that if these fear politics succeed, artificial intelligence will be monopolized by a small number of corporations.
Ng, for his part, described the claim that artificial intelligence would destroy humanity as “mind-bogglingly stupid”, arguing that large corporations are stoking extinction fears to avoid competing with open-source models.
Although these criticisms carry truth regarding corporate aims, the conflicting interests of both sides remain striking.
LeCun and Ng advocate open-source artificial intelligence models, whereas Anthropic and OpenAI favor proprietary models that keep their source code secret and lease access to users.
While major players producing proprietary models possess the capacity to comply with prospective federal licensing rules, open-source enterprises stand to be damaged by such statutory mandates. The common ground shared by doom-mongers and deregulation advocates is their lack of concern for the actual risks artificial intelligence generates.
The US intelligence community provides a more measured framework regarding tangible dangers.
In the Annual Threat Assessment, which catalogues China’s military strength, Russian influence operations, and drug cartels, the threats posed by artificial intelligence are summarized in just three items:
“It is essential to ensure that the use of machines and AI remains under human control.”
“These applications also carry risks that require careful human engineering to properly mitigate the risk of AI autonomy before they are widely deployed.”
“Emerging technologies such as AI and quantum computing are expected to have significant implications for national security.”
The official assessment by the 18 agencies comprising US intelligence on the perils of artificial intelligence remains limited to these statements. The reports contain no determinations concerning superintelligence, the annihilation of humanity, or an uprising of machines.
The US Department of Homeland Security Threat Assessment notes that artificial intelligence merely introduces fresh layers of complexity to existing threats. The department outlines five primary issues:
Disinformation, fabricated video or audio recordings (deepfakes), and election interference;
Cyber operations and financial crime;
The exploitation of this technology by violent extremists, alongside radicalization;
The proliferation of chemical and biological knowledge;
The circumvention of AI security controls and the poisoning of training data.
All of these risks were familiar prior to the emergence of artificial intelligence. AI-enabled disinformation permits legacy propaganda methods to be deployed with greater speed and intensity.
Cyber operations, financial crime, and elements of radicalization have likewise ranked as familiar subjects for many years.
Concerns regarding biological and chemical threats date back to the Bill Clinton administration, while the fifth item stems entirely from humans tampering with AI security controls.
The Global Catastrophic Risks Assessment report by the Pentagon-funded RAND Corporation think tank defines artificial intelligence as an “entropy source”.
The report states:
“AI can be thought of as adding entropy and chaos to thorny problems humans face. Chaos does not require the development of superintelligent or supercapable AI; it is possible with current and near-term AI capabilities.”
Another research study conducted within RAND identifies genetically engineered pathogens, geoengineering, and nuclear war as three plausible pathways to human extinction.
However, numerous physical and operational constraints prevent artificial intelligence from triggering these catastrophes.
In a follow-up report investigating whether large language models facilitate the planning of a mass biological attack, RAND Corp. researchers identified no statistically significant difference between plans formulated with AI assistance and those produced independently.
The US National Academy of Sciences similarly notes that the primary barrier to bioterrorism is not an absence of access to information.
The decisive bottleneck lies in DNA synthesis screening, hands-on laboratory skill, culturing, formulation, and aerosolization: procedures that all demand human intervention, carry high costs, and remain prone to failure.
Having no commercial product to release or corporate shares to protect, official analysts record with balanced language that artificial intelligence does nothing beyond compounding the scale and velocity of current problems.
Observing that all factions resort to exaggerated rhetoric to capture attention, Klippenstein points out that in the debate over whether a chatbot will transform into a god, the major actors turn a profit while foisting the cost onto the public.

Hamburg drill tests Baltic deployment prior to formal defense alert

EU explores cooperation with Trump-backed Peace Board for Gaza aid

Peter Thiel receives Springer award, targets Pope Leo and CCP

Emmanuel Todd says West faces collapse amid Ukraine and Iran crises

EU states weigh stricter asylum rules and third-country return hubs
-
 America2 weeks ago
Milanovic declares global neoliberalism dead, warns of plutocracy
-
 America2 weeks ago
Five minutes to doomsday – 4: American capitalism at the frontiers
-
 Asia2 weeks ago
DeepSeek engineer warns AI will lead to communism or Cyberpunk
-
 America2 weeks ago
Big Tech profits from AI extinction hype, Ken Klippenstein says
-
 Europe2 weeks ago
UK faces £258bn infrastructure gap as commission urges private funds
-
 Middle East2 weeks ago
Iran used Chinese satellite imagery in deadly US base attack: report
-
 Middle East2 weeks ago
Saudi exportable crude stocks risk depletion within a week
-
 Europe2 weeks ago
Wolfgang Streeck links German polycrisis to capitalism and AfD rise
