Europe
Wolfgang Streeck links German polycrisis to capitalism and AfD rise

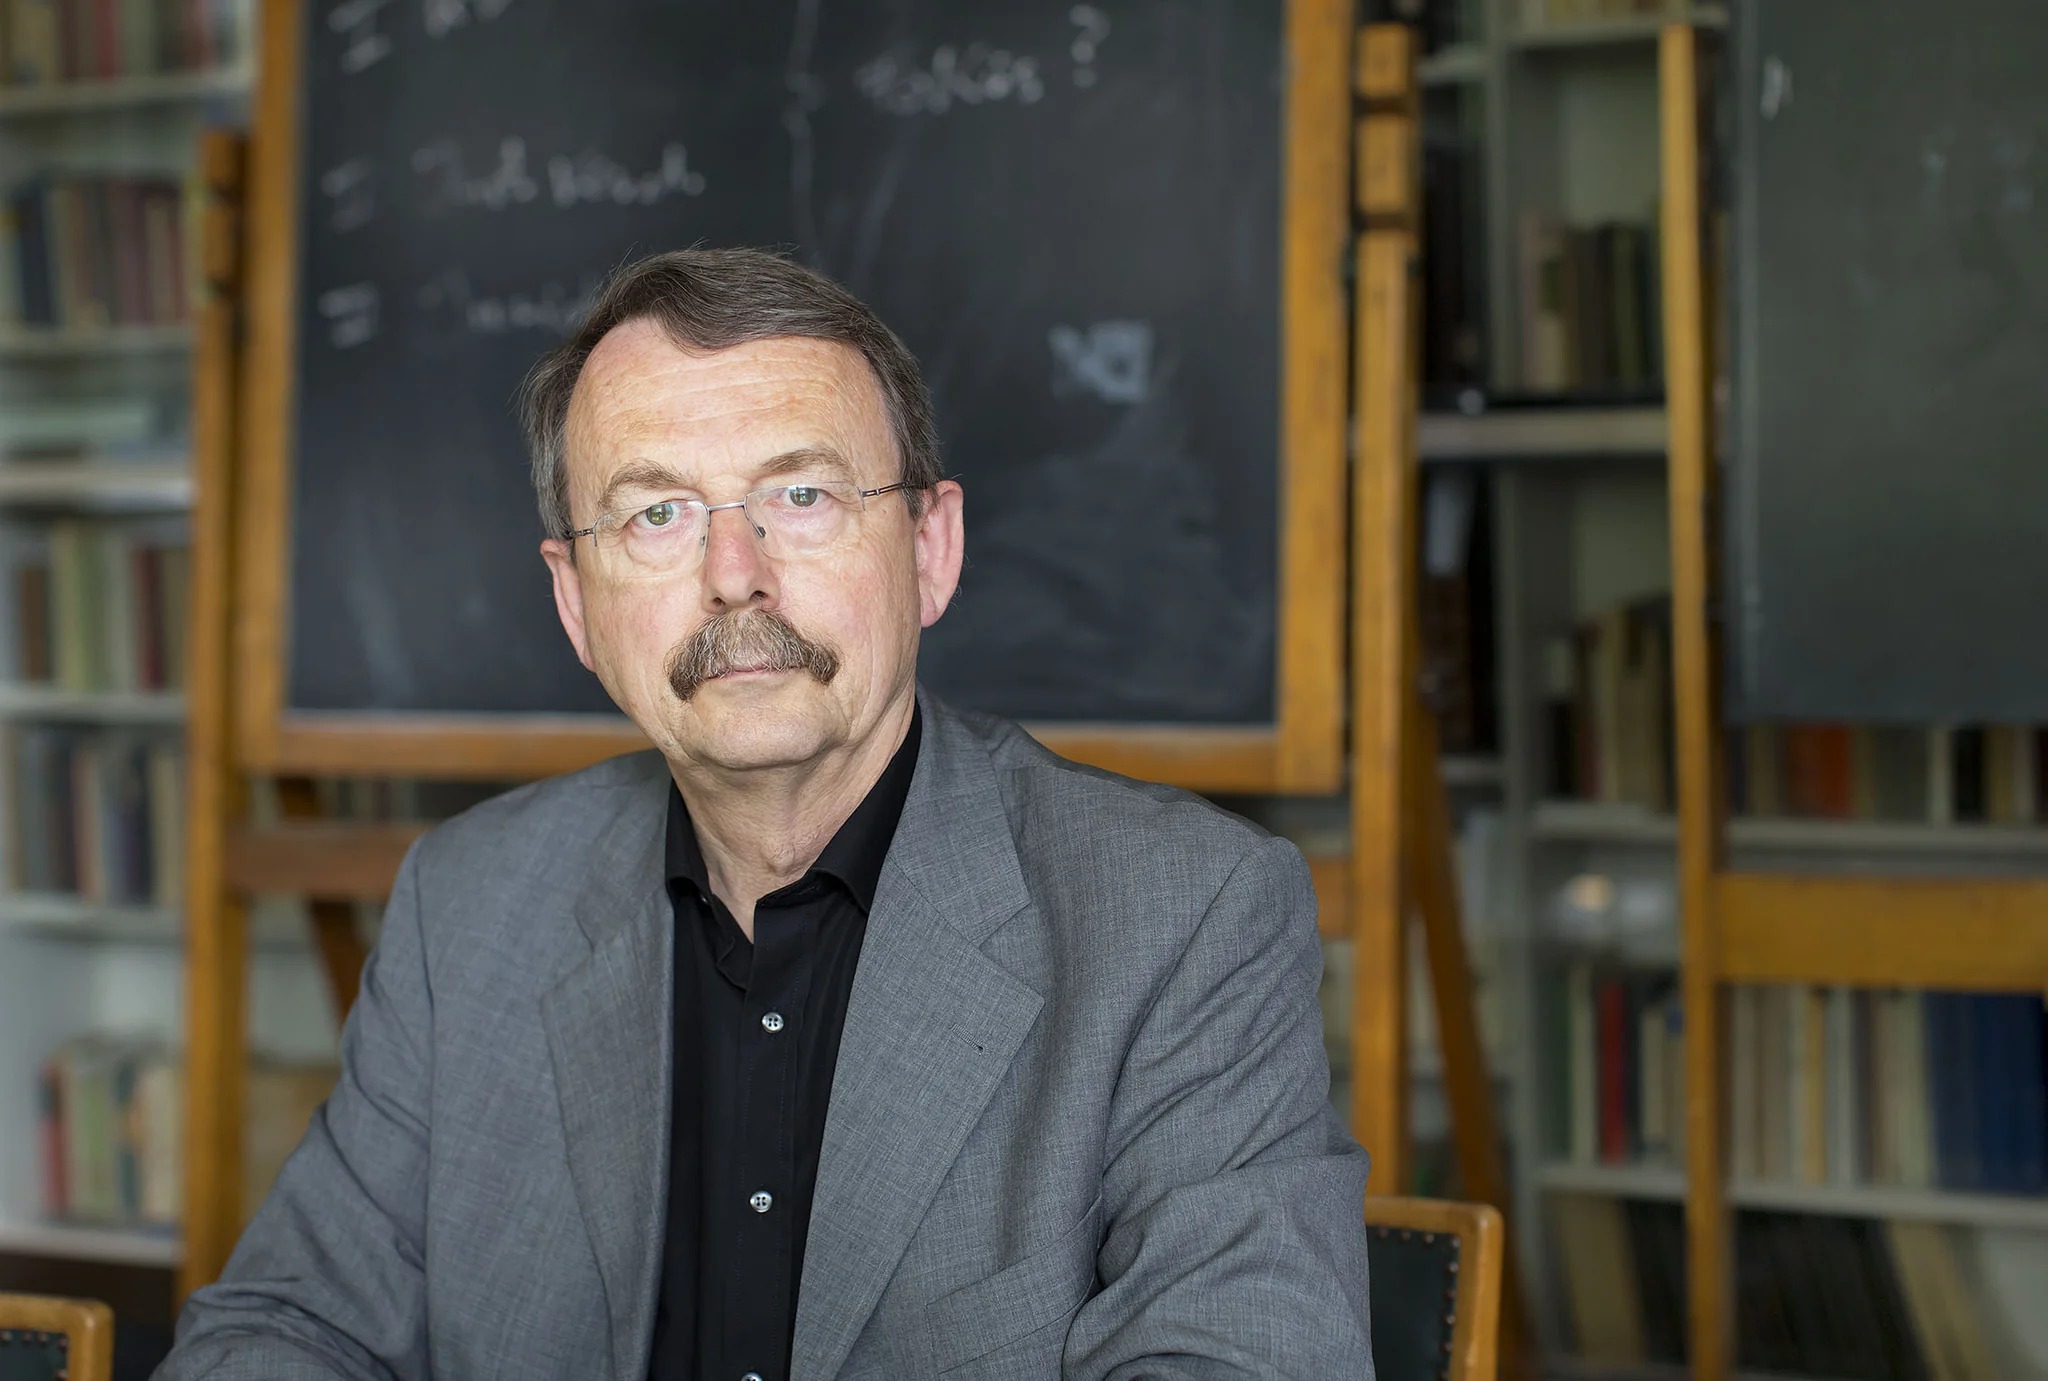
German sociologist Wolfgang Streeck has examined the link between the conditions driving the rise of the Alternative for Germany (AfD) and the capitalist crisis, calling on the left to “stop playing games and grow up.”
Writing for New Left Review (NLR), Streeck begins by asking what it means to exist within a “polycrisis.” In his view, under an increasingly “less democratic” capitalism, the countries of the rich world face “a bundle of similar crises that have emerged more or less unnoticed.”
According to Streeck, beneath these developments lies a fiscal crisis that has finally moved to the fore. In this context, “the mounting demands placed on society by the evolution of contemporary capitalism” clash with the shrinking capacity of “democratic politics” to secure the resources required to meet them.
Streeck argues that one consequence of this dynamic is the striking rise of “new-model opposition parties that are critical of the existing order and threaten to unseat the now-ageing ruling parties of the post-war era.”
Contending that nearly all of these problems in Germany stem from a policy of “stealth austerity,” Streeck points out that public investment has been deprived of resources as a result: “Stagnant [economic] growth; under these conditions any structural change assumes a zero-sum character; the deterioration of public infrastructure, including railways, bridges, and roads; a growing housing shortage and rising urban rents; the inability of both cities and rural areas to adapt to the consequences of climate change; the lack of an immigration policy to offset an ageing population alongside a sharp decline in birth rates; the decay of the education system, especially primary schools; the indebtedness of local authorities and their diminished capacity to make necessary investments and provide basic services; rising income and wealth inequality; with those most affected being chronically low-income families, particularly families headed by single mothers; and finally, widespread anxiety about the future, driven in part by fears of cuts to basic state-provided services that are becoming increasingly difficult to finance.”
According to the author, since the 1970s an ever-widening gulf has emerged between the overhead costs of capitalism and the amount that capitalist firms are willing (or can be forced) to contribute toward covering them. The progression operates as follows: these costs arise from the necessary preconditions and consequences of capitalist production, ranging from research and development and the creation of human capital to remedying environmental destruction. Yet they also stem from the need to secure legitimacy for a mode of production in which the extracted surplus value accrues to a small class of capital owners. Every form of the social wage; that is, state top-ups to the market wages of workers, such as social security and health insurance, serves to consolidate this legitimacy. As capitalist development advances and new needs arise among workers and their families, these expenditures (such as childcare facilities or eldercare) expand. At the same time, however, the scope for levying taxes on both the working classes and the classes that profit from them reaches its limits.
Streeck writes that during the neoliberal era, in order to sustain this zero-sum game; that is, to enable both capitalists and workers to carry on, states resorted to borrowing on deregulated global financial markets. Yet as sovereign debt levels escalated, the state faced the risk of losing its “creditworthiness” in the assessment of “the markets”; doubts emerged over its ability to meet interest payments from existing revenues, and even the interest itself had to be financed through borrowing.
In Germany, this development manifests through a “reform” debate conducted “under the watchful eye of the markets,” encompassing restrictions on pensions, sick leave, and labour rights.
Alongside this, the debt tap is opened to appease NATO allies and the arms industry, and perhaps as a last resort to slow down deindustrialisation.
According to Streeck, with the fiscal crisis no longer a slow-moving one, and with no hope of bringing it and the accompanying infrastructure and social welfare crises under control in the foreseeable future, traditional centrist parties have abandoned their conventional approach of “spreading cheer and optimism.”
The same holds true for the standard democratic narrative that those dissatisfied with government policy can vote for another party at the next election; the risk that this will benefit the new “anti-systemic” opposition appears too great.
Streeck writes:
“This paves the way for the formation of a party cartel in which the main parties avoid clashing with one another. In Germany this scenario seems particularly plausible: after all, the CDU and SPD were in power almost uninterruptedly throughout the long years of ‘shadow austerity’, and largely in coalition.”
Consequently, the issue ceases to be the debt crisis, rising rents, crushing living costs, shrinking public services, or growing segments of the population turning to food banks; instead, it becomes “populism,” the AfD, and neofascism.
Streeck points out that centrist parties, or “we democrats,” use this to make closing ranks mandatory once again. The logical extension of this policy is a summons to fight “against the right” and make a final stand for “our democracy,” rather than struggling against the growing power of markets over the public: “And for the sake of this, we are asked to set aside our petty squabbles over who will be subjected first, and who spared until later, to the overt austerity demanded by subsidised capital markets.”
Streeck continues:
“At first glance; from the standpoint of the ruling political class; this certainly has its appeal. Demonstrations by all sensible people against the AfD are far preferable to demonstrations against the rising cost of living; ‘firewalls’ cost far less than insulating the walls of old apartments; reports by the Federal Office for the Protection of the Constitution are far cheaper than nurseries and schools where all children can be accommodated and educated together. Moreover, floating the idea of having a party supported by at least a third of the electorate banned by the Constitutional Court in the name of ‘militant democracy’ guarantees an exciting item on the evening news about the daily exertions of those who run the state.”
Yet Streeck believes that none of this will work, either now or in the long run. Pointing out that the current governing and political class has taken no steps to address the real problems it “wants to hide behind the AfD problem,” the sociologist says: “Even if the party is banned, trains will still not run on time, heat-related deaths will not decline, cities will not become more liveable, rents will not fall, and pensions and jobs will not become more secure.”
Streeck notes that the situation would not change if the AfD were to enter government rather than being politically or physically locked away; nevertheless, he argues that the prevailing political mentality fears giving the AfD the opportunity to fail in the face of the “polycrisis.”
Streeck believes the AfD will not be diminished by the next demonstration or the next broadcast of partisan television news. In his view, as long as the “forces of the state and democracy” exhaust themselves on a secondary battlefield such as “democracy versus populism” to divert attention from the crises unfolding under their own governance, the AfD will have an easy ride.
Reminding readers that an external enemy (Russia) has been added to the internal enemy, Streeck underlines that the two are conflated as far as possible through “conspiracy theories.”
The author notes that the drive to transform a “welfare” state into a “garrison” state and brand the AfD as the “Kremlin’s fifth column” raises the question of how a debt-laden government intends to fund raising defence spending to at least 5% of GDP: “Will it resort to even more austerity or even more borrowing, risking an ultimate rupture with the domestic population, with global financial markets, or with both?”
Arguing that the left, unlike “PR specialists,” must ask certain questions, the German author points to the following:
“How can we make capital pay the bill for the costs it imposes on society and nature? How can we prevent tax avoidance and tax evasion? How will we protect companies that provide quality jobs to people in our country from a global trading system that shows no respect for workers? How can we halt the decline in our population through immigration and better family policies? In a society in transition like ours, how will we ease the debt burden on our local authorities so that they can deliver the public services essential for everyone to lead a good life? And how must ‘our democracy’ be restructured so that it becomes a democracy for all and gives citizens the opportunity to take control of their own lives; so that they are not forced to beg for handouts from a state whose coffers are empty and will remain so for a long time to come?”
Streeck concludes his article by stating: “Playtime is over; the situation is serious, and we urgently need to grow up.”






Every adult in Britain would need to pay an extra £590 a year in tax to fund planned public infrastructure investments worth £258 billion.
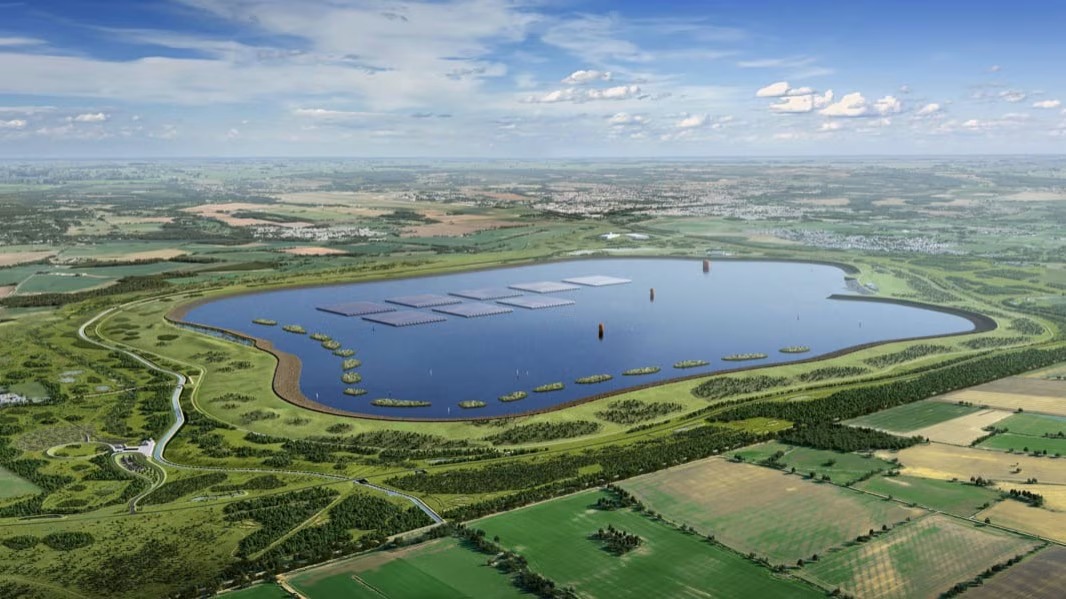
Sir John Armitt, chair of the private sector-led Public-Private Partnerships Commission, stated that delivering vital projects, such as Thames Water’s long-delayed White Horse reservoir, would require the government to increase infrastructure investment by two-thirds—equivalent to around £25 billion annually until 2030—if financed through public funds.
The crisis surrounding the early release scheme has highlighted the UK’s need for greater prison capacity, while Ofwat has warned that population growth and climate change could leave England facing a shortfall of billions of litres of water per day over the next 25 years.
Armitt, who was the final chair of the National Infrastructure Commission before it was replaced by a new agency, noted that the government’s constrained financial position means its fiscal rules would be “put in jeopardy” if the UK attempted to finance infrastructure spending through additional borrowing.
According to the report, such an approach would add approximately £7 billion to debt interest costs by 2030, £14 billion by 2035, and £23 billion by 2040.
Former Chancellor of the Exchequer Rachel Reeves had altered the fiscal rules to treat capital investment differently from day-to-day spending.
However, the required additional borrowing would still increase overall national debt.
Armitt, who recommended the creation of an OBR-style body for infrastructure, said:
“Those who believe that taxpayers and the public sector can close this gap alone have not looked closely enough at the public finances. If debt interest were a government department, it would be the fourth-largest in Whitehall. The UK faces a fundamental choice: do we want to provide the infrastructure that the public expects and the country needs, or do we not?”
A rise in government bond yields over the past two weeks has narrowed the government’s fiscal headroom, intensifying pressure on Reeves’s successor, John Healey, to balance the public books as Prime Minister Andy Burnham targets “growth in every postcode”.
The commission’s report, delivered by consultancy Bradshaw Advisory, also revealed that the UK has the lowest level of investment among G7 nations.
The report argues that reducing the cost and delivery times of infrastructure projects requires a comprehensive overhaul of the UK planning system, along with the elimination of political risk aversion and other regulatory obstacles.
According to the findings, rail projects in the UK take 50% longer than the international average, whilst delivery timelines for nationally significant projects doubled between 2009 and 2019.
To expedite construction and mitigate the threat of bureaucracy, the report proposes the introduction of a “parliamentary approval vote” for critical national infrastructure projects. Armitt characterised the current landscape as an “appalling cycle” of legal challenges.
The commission noted that uncertainty drives up the cost of infrastructure projects by generating “over-engineered designs to withstand any potential legal challenge and repeated consultations”.
Armitt called for greater pragmatism in Whitehall regarding the role of private investors and developers, who are more efficient than the public sector at delivering infrastructure because they must generate a return on their investments.
He also argued that the available capital pool is vastly larger. UK pension funds hold trillions of pounds in assets, yet only a small fraction is allocated to infrastructure projects.
Armitt said infrastructure investors have recently raised concerns that government efforts to increase public control have dampened their appetite for investing in the UK.
Arguing that this shift would deter investors, Armitt pointed to the windfall tax imposed on North Sea oil.
Armitt added that investors, particularly pension funds, “want long-term certainty and confidence”.
A separate Oxford Economics report commissioned last week by transport groups and infrastructure investors revealed that the UK has lagged behind every major economy except Greece on investment over the past 25 years.
Jon Phillips, chief executive of the Global Infrastructure Investor Association, said:
“Private capital is mobile by nature… at a time when the German, French, and Canadian governments are actively seeking to attract international investors, the UK risks losing ground.”
A government spokesperson said they welcomed “ideas to build the infrastructure needed across the UK”:
“Over the course of this Parliament, we have made progress by publishing the 10-year infrastructure strategy, increasing public investment by £120 billion to crowd in private finance, and delivering reforms to planning, major infrastructure, and regulation to give businesses and local leaders the stability they need to make long-term decisions.”

Ulrich Siegmund of the Alternative for Germany (AfD), who is expected to become the next state premier of Saxony-Anhalt, has stated that they do not oppose Germany’s rearmament, arguing that arms will be required during the “remigration” process.
The issue specifically concerns a factory in the Saxony-Anhalt town of Sangerhausen. Israeli defence contractor Elbit intends to establish production facilities there, though protests against the plan have been under way for some time.
The company manufactures, among other products, the Hermes combat drone, howitzers, and rocket launchers.
According to Christian Democratic Union (CDU) Mayor Torsten Schweiger, neither drones nor ammunition will be produced in Sangerhausen.
The Sahra Wagenknecht Alliance (BSW) had previously announced its opposition to the state becoming a defence industry hub for Israel.
Following a parliamentary group meeting, Siegmund was asked directly at a press conference about the proposed investment project.
Siegmund replied:
“Our position is very clear. We do not condemn the production of military equipment in general, because during future repatriation and deportation campaigns for migrants, we will naturally require the appropriate tools. This also applies to internal security, our own stability, and national defence. We are aware that such things do not fall from the sky.”
Siegmund also argued that a distinction exists between sending military equipment to foreign wars financed by German taxpayers and the approach they advocate.
AfD has not yet taken a final decision
Siegmund explained that the AfD is monitoring the situation in Sangerhausen and remains in contact with local political representatives.
At the same time, he noted that the economic aspects of a potential factory site should not be ignored. The party also plans to examine closely what is produced in Sangerhausen and under what conditions.
“We want to examine closely: what is produced there, and under what conditions? And do we face the risk of being drawn into foreign conflicts as a result? If so, we view this situation with great scepticism,” Siegmund said.
Siegmund also pointed to conversations he had with citizens during the election campaign. Many people, including local residents in Sangerhausen, welcomed the AfD’s stance.
However, his party has not yet reached a final decision regarding the prospective facility. “A valid decision has not yet been taken because we still do not possess all the information,” the AfD politician said.
Green light for militarisation on grounds of remigration and security
Siegmund’s remarks indicating that weapons are needed for “remigration” drew attention. The term refers to the deportation of people with an immigrant background and was coined by Austrian right-wing activist Martin Sellner. The AfD has adopted the phrase over the past few years.
Years ago, Thuringia AfD leader Björn Höcke spoke of “well-measured cruelty” in the context of deportation procedures.
AfD politicians Kay Gottschalk and Lena Kotré attended an international “Remigration Summit” held in Portugal in late May.
There, Martin Sellner of the Identitarian movement declared their aims to secure “Europe’s ethnocultural continuity”, halt all legal or illegal immigration into Europe, and remove “millions” of non-Western immigrants from the continent.
In a video recorded alongside Sellner, Dutch activist Eva Vlaardingerbroek said: “Nobody comes in, and millions go out.”
In interviews, Kotré and Gottschalk presented the mass deportation of millions of people as a panacea for the housing market, the education system, and society.
Federal Chancellor Friedrich Merz criticised the AfD on Wednesday, stating that the concept of “remigration” amounts to nothing other than “ethnic cleansing based on skin colour and origin”.
Wagenknecht criticises “remigration”
Meanwhile, BSW, which decided unanimously to hold talks with the AfD in Saxony-Anhalt, has publicly announced its “red lines”.
Party founder Sahra Wagenknecht stated that she maintains clear red lines against the AfD, particularly regarding “remigration”.
In an interview with RTL and ntv, Wagenknecht said: “They will feel our strong opposition on this matter. I find it terrible that people are worried and frightened.”
Stating that it is unacceptable for “well-integrated citizens” to be affected, the BSW leader remarked: “And we will not yield on this.” She continued:
“If the AfD is truly serious about frightening people who came to our country, work here, are well integrated, pay taxes, and whose children grow up here; if they intend to tell them, ‘You do not belong here’ or convey the message, ‘We want to expel you’ [we will prevent it].”
Regarding the AfD’s election manifesto equating homosexuality with “sexual deviance”, Wagenknecht replied: “Naturally, we believe every individual should live and love as they wish, and that equality exists here, including legal equality. Anyone questioning this does not live in modern times.”
BSW does not back Siegmund for premier
Wagenknecht also dismissed claims that BSW would elect AfD candidate Ulrich Siegmund as state premier in Saxony-Anhalt, stating: “We have always made what we want very clear.”
Wagenknecht argued that Siegmund had given “completely contradictory statements regarding when he wants to be state premier and when he does not”.
“One gets the impression that he himself might feel it is not such a good idea after all,” Wagenknecht said.
The BSW founder called for a “respected figure across party lines” upon whom everyone could agree and who could “bring this country a little closer together”.

Chinese brands are rapidly gaining market share in Europe. Exclusive data reveals which manufacturers are suffering the most from this new competition.
According to research by Handelsblatt, Chinese brands accounted for 8.7% of new vehicle registrations from January to July, compared with only 0.6% in 2021.
Based on an analysis of figures from the data service Dataforce, this share has nearly tripled compared with 2024 alone.
Concerns are growing in industry circles that this offensive by Chinese manufacturers will continue to accelerate and that price competition in Europe will intensify.
In the first seven months, approximately 780,000 new cars belonging to Chinese brands hit European roads, a figure almost equal to sales for the whole of 2025.
According to Handelsblatt’s analysis, the manufacturers initially expanded their presence in Southern and Eastern Europe, as well as in the United Kingdom.
Equipped with the experience gained there, they are now targeting the largest, but also the most challenging, passenger car market: Germany.
With sales of nearly three million new cars a year, the German market remains in the hands of German manufacturers.
In addition, Stellantis, the multi-brand group that includes Opel and Peugeot, alongside Toyota and Korean manufacturers Hyundai and Kia, hold significant market shares. These shares are now at risk.
Albert Waas, a partner at the consultancy firm BCG, says: “As a first step, Chinese carmakers are targeting the core business of high-volume manufacturers.”
In this segment, it is easier to increase visibility on the roads more quickly. Far Eastern brands are offering affordable compact and family cars, as well as an increasing number of SUV models.
Chinese manufacturers are benefiting from the growing electric vehicle segment in Europe, but they are also taking advantage of declining customer loyalty to established brands.
Opel parent company hit hardest
The biggest loser is Stellantis. The group’s market share in Europe currently stands at 15.5%. In 2021, this rate was still close to 21%. This represents a drop of just under 155,000 units.
According to the major bank UBS, the reason for this is that Stellantis experiences “significant overlap in terms of countries and segments” with Chinese brands. “Company-specific problems” also played a role in this situation.
Stellantis’s ambitious electric vehicle plans did not yield the expected results, and numerous product recalls were carried out due to quality defects stemming from cost-cutting measures.
Ford is also struggling with new competitors, and its market share fell from 4.6% to 3%. Among German manufacturers, the core Volkswagen brand was particularly affected. Its market share has fallen from 10.7% to 9.9% since 2021.
To a lesser extent, Japanese carmakers such as Nissan and Mazda, as well as Korean manufacturers such as Hyundai and Kia, also lost market share to Chinese brands.
On the other hand, Renault’s market share remained stable at around 6%. UBS attributes this to a “strong product cycle”. The French carmaker is launching numerous new electric models, such as the Renault 5 compact car, and these models are being well received.
Because Chinese cars are cheaper and in some cases technically superior, Europeans are becoming increasingly willing to purchase car brands from the Far East.
At the same time, Chinese manufacturers are being forced to expand more aggressively abroad. In the domestic market, a destructive price war continues among more than 100 competitors, in which almost no manufacturer can make a profit.
In addition, the automotive industry has lost its importance in China’s five-year plan.
Because the US is effectively closing its doors to Chinese manufacturers, these producers are focusing primarily on Europe.
According to experts, they can charge twice as much for their vehicles in this market as they do in China.
This explains why passenger car exports from the People’s Republic of China rose by 78% in August compared with the same month last year, reaching 894,000 vehicles.
In contrast, domestic sales contracted for the eleventh consecutive month, falling by almost a quarter to 1.55 million.
A few Chinese brands dominate the market
Even when Toyota entered the European market in the 1970s and Hyundai in the 1990s, there were warnings that established manufacturers could lose market share to Asian rivals.
What is new now is that Chinese manufacturers are making progress in the electric vehicle segment and in software, areas where they are considered leaders.
They are benefiting from the rapid surge in demand for electric cars in Europe, driven by government subsidies and high fuel prices caused by the war in Iran.
According to the analysis, China’s market share in electric cars in Europe has already reached 12.6%. In 2021, this rate was only 2.1%.
Volkswagen is feeling the impact of this situation: in 2021, the Wolfsburg-based company held an approximately 14% share in the electric vehicle segment, which was significantly smaller at the time. That figure is now below 8%.
Stellantis’s market share in electric cars, meanwhile, fell from over 14% to around 10%.
Dataforce counts 19 Chinese manufacturers in Europe. However, five brands account for 83% of sales.
BYD, the world’s largest electric car manufacturer, also leads in Europe. As of the end of July, the brand’s new registrations reached 217,000, and its market share stood at 2.4%.
BYD has thus already surpassed brands such as Volvo (202,000 units), Nissan (183,000), and Tesla (178,000).
New registration figures for the Fiat (262,000), Ford (272,000), and Opel (284,000) brands are also within BYD’s reach.
MG ranks just behind BYD with 211,000 registered vehicles. Formerly British, this brand is part of the Chinese holding company SAIC.
The manufacturer Chery holds a 1.7% market share in Europe through its Jaecoo and Omoda brands.
Leapmotor is experiencing particularly strong growth. The 65,000 registrations recorded by the end of July by Stellantis’s joint venture partner represent more than double the total figure for the whole of 2025.
The reason for this is a one-off factor: nearly 40% of Leapmotor’s registrations this year came from Italy.
There, the retail price of the T03 microcar dropped from its regular price of 18,900 euros to below 5,000 euros, thanks to a manufacturer discount and a government electric vehicle incentive.
Regional differences exist across Europe
Significant regional differences exist: in Spain, Portugal, Italy, and Greece, Chinese carmakers account for 11.4% of sales.
BCG expert Waas says: “In Southern Europe, people traditionally buy more small cars, and this is a segment where Chinese manufacturers are strong.”
In the south, Stellantis suffered particularly severe losses. In 2021, this multi-brand group accounted for almost a third of new registrations in the region; that figure is now only 22.3%.
Ford fell from 4.8% to 2.7%. Other high-volume brands such as Volkswagen and Renault, as well as Japanese and Korean manufacturers, are also experiencing slight declines.
In Eastern and Northern Europe, the situation among the losers is similar. However, the extent of the Chinese manufacturers’ presence varies between these regions: while their market share in Eastern Europe is 9.5%, it stands at 7.3% in Denmark, Sweden, Norway, and Finland.
In Central Europe, the share of Chinese manufacturers is 5.1%, a figure similar to that in France, an important automotive market. In Germany, this share is currently only 4.1%.
However, compared with the 2.3% rate recorded in 2025, this represents a dynamic increase.
This situation is also likely linked to the German government’s new electric vehicle support programme, from which Chinese brands have particularly benefited.
Matthias Schmidt of his eponymous consultancy says: “Loyalty to domestic brands in Germany and France remains a structural obstacle for Chinese carmakers.”
In Germany, the market shares of domestic brands have barely changed. In France, too, buyers continue to feel a strong attachment to Renault, Peugeot, and Citroen.
Chinese manufacturers have a particularly strong presence in the United Kingdom. A quarter of all vehicle registrations by Chinese brands in Europe took place in the United Kingdom. Their market share in this country hovers just below 16%.
Chinese manufacturers are increasingly shipping their electric vehicles to the United Kingdom because, unlike the European Union, no special tariffs are applied there.
In addition, their task is easier in the United Kingdom due to the absence of large-scale domestic manufacturers.
Premium segment remains largely unaffected
In the premium segment, however, attempts by Chinese manufacturers to gain a foothold in Europe have so far ended in failure.
The European market shares of Audi, BMW, and Mercedes-Benz have remained largely stable for years.
The carmaker Nio, which has a unique selling point with its battery-swapping technology, sold fewer than 500 vehicles in Europe this year.
Although Xpeng reached more than 24,000 units thanks to a significant increase, its market share remains below 0.3%. Zeekr, meanwhile, did not exceed 0.08%.
The reason is that Chinese brands appeal to a different customer base. Car dealer Burkhard Weller says: “Anyone who buys a Chinese car brand is a bargain hunter.”
In contrast, buyers of premium brands in Europe usually “are still investing in a certain image.”
Yet concern is also growing among premium manufacturers. As CEO Ola Kallenius has frequently emphasised, although Mercedes has not yet lost European market share to new rivals, he stated in a letter sent to employees this summer that Chinese competitors with “very lean cost structures and high innovation speed” are entering the European market.
Experts believe Xiaomi in particular has a strong future. The manufacturer plans to begin its international expansion in 2027.
Xiaomi founder Lei Jun said: “The first market will be Germany, the most difficult market in the world.” BYD also plans to expand the reach of its premium brand Denza in Germany.
Chinese automotive companies expected to grow further
UBS analysts forecast that Chinese manufacturers will increase their European market share to 20% by the end of the decade.
However, industry expert Schmidt estimates that their share of the all-electric vehicle market will not exceed 15%.
Schmidt argues that new Chinese manufacturers will compete with established rivals for the same customer base and will eventually begin to cannibalise each other’s market share.
Moreover, “established manufacturers are stepping up their efforts to protect their market share.”
Consequently, European brands are introducing more affordable electric cars to the market.
At Renault, the electric Twingo is already on sale for less than 20,000 euros.
Volkswagen plans to launch the ID.1 microcar at this price point in 2027.
Regulation is also affecting future developments. Since the EU began applying tariffs to electric cars in the autumn of 2024, Chinese carmakers have rapidly expanded their hybrid vehicle offerings.
Hybrid cars currently account for 53% of Chinese-origin vehicle registrations in Europe, compared with only 15% in 2021.
As a result, calls are growing among German politicians to impose tariffs on hybrid vehicles of Chinese origin.
This year, BYD overtook Volkswagen in plug-in hybrid vehicle registrations. For this reason, industry sources state: “If the German government cannot convince Europe that tariffs should be imposed on hybrid vehicles, then we have a problem.”

UK faces £258bn infrastructure gap as commission urges private funds

Milanovic declares global neoliberalism dead, warns of plutocracy

Saudi exportable crude stocks risk depletion within a week

Iran used Chinese satellite imagery in deadly US base attack: report

Wolfgang Streeck links German polycrisis to capitalism and AfD rise
-
 Europe7 days ago
Germany’s CDU drafts tougher citizenship rules to counter AfD
-
 Russia2 weeks ago
What to know about Russia’s upcoming State Duma elections?
-
 Europe2 weeks ago
Marine Le Pen leads all 2027 French presidential scenarios, poll shows
-
 Diplomacy1 week ago
Geoffrey Roberts sees Ukraine war concluding within coming months
-
 Middle East2 weeks ago
Iran expands deterrence as Gulf strikes expose US munitions limits, analysts say
-
 Europe2 weeks ago
German industrial bosses push for return to 40-hour working week
-
 Russia2 weeks ago
Russia warns NATO over Arctic militarisation and conflict risks
-
 Asia2 weeks ago
BOJ faces critical rate decision as US presses for faster hikes
