America
Beyond a handful of oil

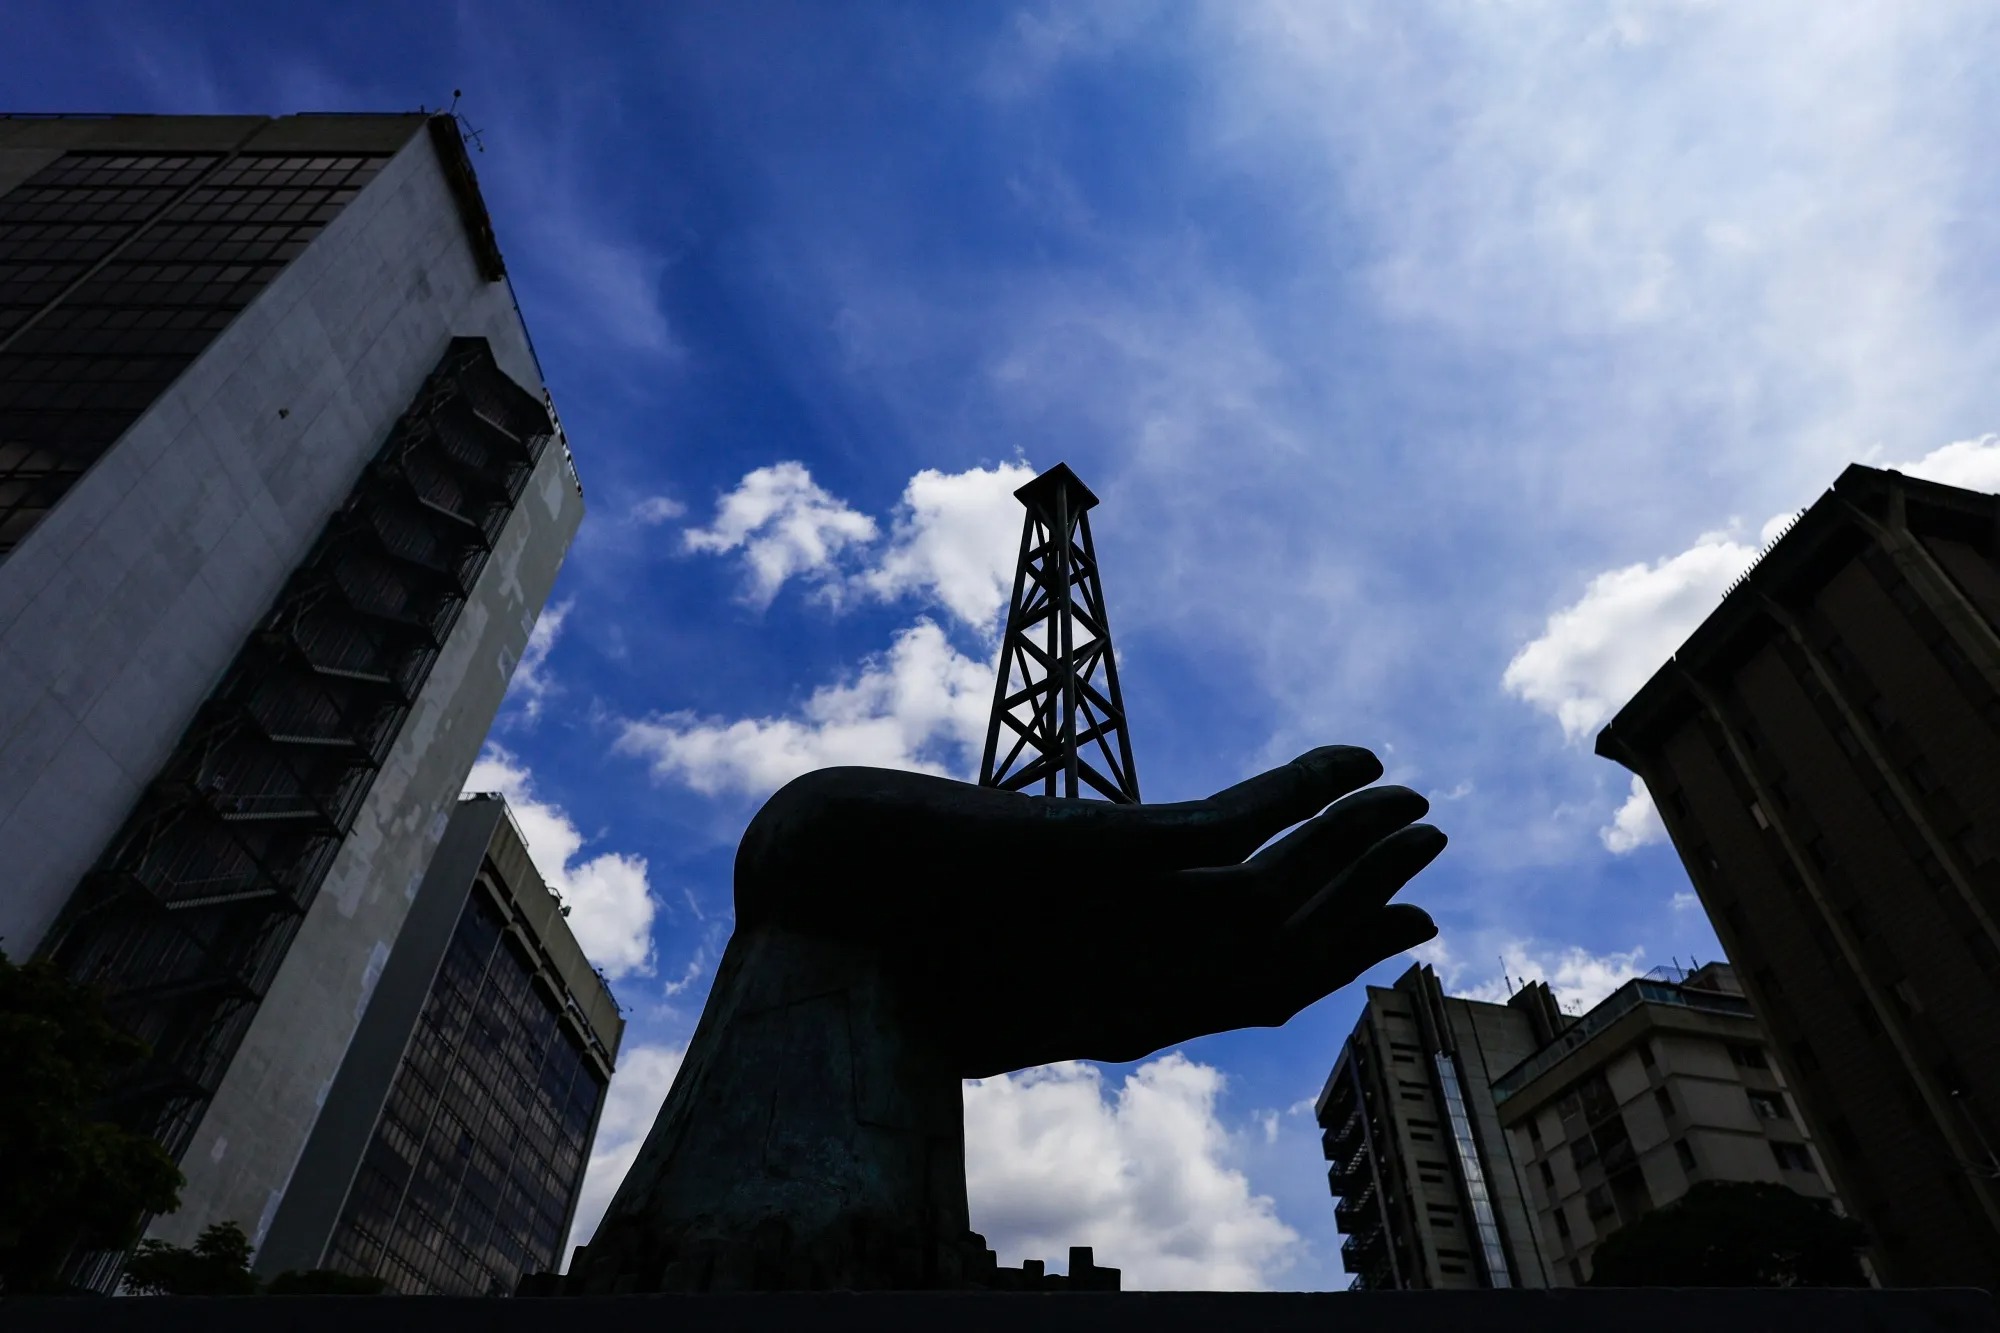
As the American occupation of Venezuela approaches quite openly, we are once again living and breathing stories of oil seizures.
When we say “story,” it is not exactly a fairy tale: The name at the head of the occupation operation, Donald Trump, states with great clarity that besides excuses like drugs, he wants to seize Venezuela’s oil. By “seizing,” he doesn’t just mean confiscating production; he also wants to prevent Venezuela from selling oil to “US adversaries.”(1)
According to OPEC, Venezuela possesses approximately 17% of global reserves, or 303 billion barrels; this means it ranks ahead of OPEC leader Saudi Arabia. According to the US Department of Energy, these reserves consist mostly of heavy oil in the Orinoco belt in central Venezuela, which makes crude oil production expensive.(2)
The US has the infrastructure suitable for this. Despite being the world’s largest oil producer, the US still imports large quantities of crude oil. Heavy oil is critically important for American refineries, especially those around the Gulf of Mexico. About 70 percent of American crude oil imports are heavy oil, and 60 percent of this comes from Canada, which has a similar “heaviness” to Venezuela.
On the other hand, a meaningful recovery in Venezuela requires time, large-scale infrastructure reconstruction, billions of dollars in capital, and the sustained participation of international oil companies. Since oil monopolies prioritize more competitive and lower-risk projects elsewhere, obtaining this level of commitment is currently quite difficult.(3)
Indeed, energy giants like Exxon and ConocoPhillips, including Chevron which currently holds a license waiver, are hesitant to re-enter Venezuela. For this reason alone, some argue that help should be sought from companies of “allied” countries, such as Eni, which is already operating in Venezuela.
Moreover, American oil monopolies already have drilling projects available in the Americas that can be extracted more cheaply. For instance, both Exxon and Chevron operate in Guyana, where Venezuela has a territorial dispute, and it is estimated that Exxon can produce there at a cost below $35 per barrel (Venezuela produces at $49 in the Orinoco region). Chevron is expected to produce oil in the Permian region for $37 to $44. ConocoPhillips’ investments in Canada project a cost of $42 per barrel. Therefore, reintroducing Venezuelan oil to international markets is not currently capable of causing the kind of price drop Trump claims.
Furthermore, even if progress could be made in “upstream” operations, Venezuela has been stagnating for some time in “midstream” and “downstream” sectors such as refining, transport, and distribution. In the country where refining capacity has remained constant for many years, capacity utilization has also been weak.
So how is it assumed that investment will flow into Venezuela and the oil industry will get back on its feet? Javier Blas from Bloomberg points out that the issue is not just Venezuelan oil, but American hegemony over oil reserves in the entire “Western Hemisphere” via the “Monroe Doctrine,” which was highlighted in the latest National Security Strategy (NSS). According to this calculation, when Canada, Mexico, and all of Latin America are included, the US captures 40 percent of the world’s entire oil production, gaining an invaluable asset against its rivals. It also gains the ability to set prices, a power once held by Arab countries and now by OPEC.
Energy prices are quite important for the predatory capital faction clustered around Trump. Access to new energy sources, including nuclear, is critical for Silicon Valley technology capital, which is investing heavily in data centers that will grow artificial intelligence. In this context, while companies like Microsoft invest in nuclear energy, American oil monopolies known as supermajors have taken action to provide energy to data centers; because natural gas, oil, and coal are still the three raw materials with the largest share in US primary energy production.
In December 2024, executives from Exxon and Chevron separately announced that their companies were preparing to enter the electricity sector. Oil companies, which usually generate electricity only for their own operations, will enter the broader electricity market at a time when demand is rising rapidly.
Rest assured, all of this will be accompanied by the plundering of nickel deposits in Venezuela, which have been found to be quite rich. Indeed, Axios counts AI companies among the winners of the so-called regime change in Venezuela. Venezuela is the richest source of critical minerals used in semiconductors that power AI data centers. According to Axios, if the US can use Venezuela instead of being dependent on China for these materials, it could get a step ahead in the AI race.
In fact, on Sunday aboard Air Force One, Commerce Secretary Howard Lutnick touched upon “mining opportunities” in Venezuela and said, “You have steel, you have minerals, you have all the critical minerals. They have a great history of mining, but that history has rusted.”
On the other hand, there is a not-so-small problem here: Even if the US frees itself from China in the supply of rare earth elements, the refining processes for these materials are done almost entirely in China. The US does not have such expertise, and acquiring it will likely take many years.
But beyond this, the financialization of both its oil and Venezuela’s debts seems much more appetizing, and this is where the main significance of Trump’s thuggery lies. Indeed, it appears that Wall Street had its eye on the “wealth” opportunities that regime change would create even before Maduro was abducted. According to Bloomberg, weeks before the invasion, Citigroup analysts predicted gains of up to 60% in the country’s bonds if Maduro were removed from office. At crowded conferences and seminars, other strategists voiced their opinions on the potential profit the new regime could offer holders of the country’s $60 billion in bonds. As pressure on Maduro mounted, traders flocked to bonds, sparking a rally:
“Investors, including American energy and shipping tycoon Harry Sargeant III, lobbied the Trump administration to create a more favorable business environment in Venezuela, highlighting the advantages for the US. Paul Singer’s Elliott Investment Management, along with a consortium of other investors, had been fighting for years for Venezuela’s most valuable foreign asset.”
In public markets, bondholders made gains of about $4 billion in a single day and saw hope for a restructuring that would yield further profits. According to the report, for private equity firms and energy investors, Donald Trump promised an even bigger prize by “pledging that the US would spend billions of dollars to fix Venezuela’s broken oil infrastructure.”
Among these promises, of course, are the receivables of companies nationalized during the Chavez era. ConocoPhillips has been trying to get approximately $12 billion in compensation for its seized assets for years. Hedge funds are looking for ways to invest in billions of dollars of financial claims linked to Venezuela. Venezuela is also considered indebted to many major companies after nationalizing assets in 2007. Following the 2017 default, the prospect of the country’s long-delayed debt restructuring is making the palms of private equity firms that buy and sell debt itch. Although Venezuela’s sovereign bond market is relatively popular, the opening of receivables and arbitration claims to financial markets is significant for American capital. This capital faction, however, sees the possibility of reviving Venezuela’s oil industry as an opportunity to pressure Venezuela to pay the debts of those who are creditors, particularly of the state oil company PDVSA.(4) After years of fruitless efforts to extract cash from the Maduro government, many companies have sold these international arbitration cases to specialized investors, including hedge funds.
Ben Cleary, partner and director at the $4 billion Tribeca Investment Partners, is sending a team of investors to Caracas to meet with potential partners and examine potential assets. US-based advisory firm Signum Global Advisors, which took investors to Ukraine last year as part of reconstruction efforts, is also planning a trip to Venezuela at the end of March. The group will consist of about 20 participants, comprised of multinational corporations and money managers.
Indeed, Bloomberg points out how Wall Street and private equity have become intertwined to reshape Venezuela through Trump’s aggressive move based on the claim of oil seizure. For example, a fund manager suggests that everything in Venezuela will depend on what kind of investments are made in the oil sector.
I would also like to remind you that asset managers invest heavily in oil monopolies. Just as the oil commodity itself is a financial product, oil monopolies are intertwined with financial markets. While asset managers like Brookfield and Blackstone are already investing in energy assets, sovereign wealth funds like the Saudi Public Investment Fund and the Abu Dhabi Investment Authority have been looking for ways to channel their billions of dollars of investments into South America for years.
The financialization of sovereign debt linked to oil seizure and the rush of private equity means the “Ukrainization” of Venezuela; that is, transforming it into a colony of transnational (but in this instance, American) capital. In any case, there really is an “oil excuse” at play. But it is not as it is assumed to be.
(1) Economists Asdrubal Oliveros and Juan Palacios, in their book Sanctions in Venezuela, found that from 2023 to 2024, exports to the US, Spain, and India increased at the expense of China and Malaysia. In 2023, the first group received 34% of Venezuelan crude oil exports, while the second group received 51.6%. In 2024, these ratios were nearly reversed, becoming 56.2% and 26.8%, respectively.
(2) According to Bloomberg’s analysis, most Venezuelan crude oil is high-sulfur and heavy, meaning it is costly and technically difficult to transport and refine compared to light and sweet quality oil. To facilitate the transport and processing of this type of crude oil, it usually needs to be mixed with a diluent (such as condensate or naphtha). Furthermore, special refining equipment is necessary to refine this type of crude oil. Consequently, such heavy and sour crude oil trades at a significant discount compared to international benchmark prices. Additionally, the production of naphtha used in transporting heavy oil is heavily dependent on Russia, and as long as sanctions persist, making progress in naphtha imports seems unlikely. Last December, a tanker carrying naphtha from Russia to Venezuela turned back due to the Trump blockade.
(3) According to POLITICO, Rystad Energy stated in a client note that “approximately $53 billion in oil and gas upstream and infrastructure investment is required over the next 15 years to keep Venezuela’s crude oil production steady at 1.1 million barrels per day”: “Going above the 1.4 million [barrels per day] level is possible, but this will require steady investment of $8-9 billion annually from 2026 to 2040, in addition to ‘maintenance’ capital requirements.”
(4) Defaulted bonds issued by Venezuela and the state oil company Petróleos de Venezuela continued their gains on Tuesday following an increase of up to 35% on Monday. According to data compiled by Bloomberg based on the latest investor filings, holders of these bonds include some of the world’s largest asset managers, such as Fidelity Investments, BlackRock, and T. Rowe Price Group.





Richard Blumenthal, the ranking Democrat on the US Senate Permanent Subcommittee on Investigations (PSI), has requested documents from cryptocurrency exchange Binance, Tether, and crypto projects linked to President Donald Trump as part of inquiries into potential financial irregularities and conflicts of interest.
The documents were requested to be submitted by 4 January 2027.
Senators warned that they would resort to compulsory measures if the request was refused.
Entities sent document requests include World Liberty Financial and Fight Fight Fight LLC, both linked to President Trump’s family.
Blumenthal began examining the activities of these entities in May 2025 following reports that they may have engaged in transactions with foreigners under federal criminal investigation, attracted investments from foreign governments, and violated public ethics rules.
Notably, in 2026, it emerged that individuals close to the Abu Dhabi royal family had signed an agreement with the Trump family to purchase 49% of the shares in World Liberty Financial for $500 million.
The company, founded in September 2024 by the US President and his sons, launched a token called WLFI.
According to official disclosures, Trump made $800 million from this token alone.
Conversely, crypto analytics firm Nansen calculated, by tracking 1.48 million crypto wallets, that approximately two-thirds of those who invested in the token after its launch in January 2025 incurred losses.
While many retail investors spent several thousand dollars on purchases, the largest investors poured in millions of dollars.
Trump also launched his own memecoin, TRUMP, on 17 January 2025, prior to his inauguration.
Rising 10.6-fold in value within three days, the cryptocurrency’s market capitalisation reached $15 billion at its peak.
However, after those three days, the price entered a downturn, plunging by 97%.
Trump reported in his financial disclosure that he earned $635 million in income from sales of these memecoins.
In July 2026, Blumenthal held public hearings on the family crypto projects from which the President made $1.4 billion.
The losses suffered by TRUMP memecoin investors were also addressed during these hearings.
Cryptocurrency exchange Binance and Tether, which issues the largest stablecoin, USDT, are under scrutiny over their dealings with the Trump administration.
Lawmakers suspected conflicts of interest stemming from the exchange’s collaboration with World Liberty Financial.
Previously, a group of senators had demanded an inquiry into the terms of the presidential pardon granted to Binance founder Changpeng Zhao.
Separately, The New York Times reported that the United Arab Emirates (UAE) gaining access to American artificial intelligence chips coincided with a $2 billion investment by a UAE entity into Binance using USD1, a stablecoin issued by World Liberty Financial.
While this deal rapidly expanded the volume of tokens in circulation, it enabled Trump’s company to generate revenue from interest on government bonds where USD1 reserves were held.
Trump, for his part, described the report as slander.
Americans’ credit card debt reached a record $1.29 trillion in the third quarter, according to a new report published by the New York Fed.
Falling behind on credit card payments can trap struggling households in a cycle of fees, credit score downgrades, and increasingly expensive borrowing.
Although delinquency rates across the country have shown improvement, the latest figures indicate that financial distress is concentrated in lower-income communities.
Consumer credit card balances rose by $22 billion in the third quarter, representing an increase of 1.7%. This figure is $52 billion higher than it was a year earlier.
The figures are not adjusted for inflation, which may mean that part of the increase reflects rising prices rather than more borrowing in real terms.
Total household debt, which includes mortgages, student loans, and auto loans, rose by $334 billion in the third quarter to reach a record $19.1 trillion.
This total represents an increase of $5 trillion compared to 2019, just before the pandemic.
The volume of credit card balances falling into serious delinquency is declining, indicating some improvement in Americans’ ability to make their payments on time.
The rate of credit card debt transitioning into serious delinquency fell to 6.9% in the third quarter. However, this rate remains distinctly higher than the 5.2% recorded prior to the pandemic.
Americans living in lower-income neighbourhoods are facing greater difficulty in keeping up with their credit card payments compared to more affluent groups, according to a separate report published by the New York Fed on Tuesday.
Delinquency rates across all neighbourhood income tiers remain above pre-pandemic levels, while the gap between the wealthiest and poorest areas has widened since 2022.
In the lowest-income neighbourhoods, 10.3% of credit card balances transitioned into serious delinquency over the past year.
This is more than double the 4.4% rate observed in the wealthiest neighbourhoods.
The average credit card balance per borrower now stands at $6,678, according to TransUnion’s third-quarter analysis report.
Among borrowers under the age of 30, the rate of credit card debt falling at least 90 days delinquent reached the highest level, according to the Fed’s report.
Democrats won the midterm elections promising to bring down prices, but delivering relief that voters can genuinely feel in their household budgets will be a difficult target to achieve.
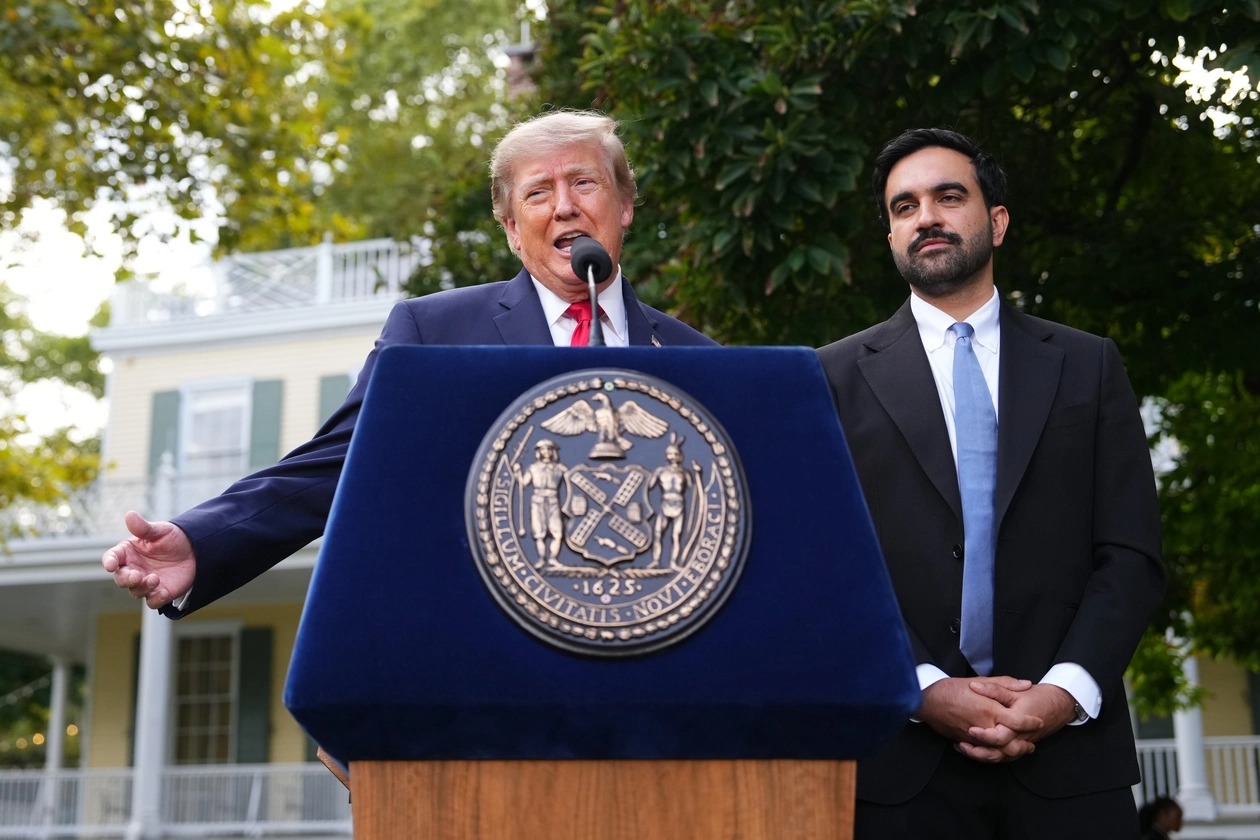
New York City Mayor Zohran Mamdani is using his rapport with US President Donald Trump to secure the release of selected detained immigrants.
According to reporting by Politico, Mamdani persuaded Trump during their second White House meeting in February to free a university student who had been detained that day by ICE.
The outcome served as validation for Mamdani, who pointed to the release of the Columbia University senior as proof that his surprisingly cordial relationship with Trump could produce tangible results for New Yorkers.
Mamdani subsequently continued to seek similar immigration-related interventions from the Republican president.
Since that February meeting, Mamdani and his aides have quietly forwarded the names of approximately two dozen immigrant New Yorkers held in ICE custody to Trump’s team, asking the president to order their release.
Two sources familiar with the matter said Mamdani most recently shared names of detained immigrants during a September meeting with Trump at Gracie Mansion.
The sources said the individuals in question had no serious criminal records, though they declined to disclose their identities, citing safety concerns.
According to Politico, these ongoing efforts regarding detained immigrants indicate Mamdani’s belief that he can leverage his rapport with Trump to advance causes the mercurial president might not ordinarily support.
Mamdani’s decision not to disclose these continued appeals publicly suggests an inclination to keep his interventions private to improve their chances of success.
Yet it remains unclear whether any immigrant besides Columbia University student Elmina Aghayeva has actually been released as a result of these efforts, and concern is mounting within City Hall that the window for securing such releases may be closing.
Mamdani’s aides working on the releases, including his Chief of Staff Elle Bisgaard-Church, communicated primarily with Trump’s White House Chief of Staff Susie Wiles, according to people familiar with the matter.
Last week, Trump replaced Wiles with Stephen Miller, the architect of the administration’s most hardline immigration proposals and one of the loudest internal voices urging the president to pursue a mass deportation agenda in his second term.
A person familiar with the Mamdani administration’s thinking said the mayor’s team views it as unlikely that Miller will continue cooperating in the manner Wiles did, given his stance on immigration.
Mamdani spokesperson Dora Pekec declined to comment on internal concerns regarding Miller and did not provide details about the immigrants whose release the mayor had requested.
Pekec noted, however, that Mamdani has “consistently advocated directly on behalf of New Yorkers in his calls and meetings with the president.”
Murad Awawdeh, a close Mamdani ally and president and CEO of the New York Immigration Coalition, said the mayor’s team should not halt engagement with the Trump administration on immigration matters because of Miller’s promotion:
“Stephen Miller is a cruel individual who has spent his career attacking immigrants, but he is not the president; Donald Trump is, and this is his deportation agenda. New York expects the president to work with the mayor to serve this city and end the terror in our communities. Miller’s promotion changes none of that.”
Mamdani’s warm dynamic with Trump has confounded both allies and critics.
During last year’s New York mayoral election, Trump referred to Mamdani as a “communist lunatic” and threatened to have him arrested.
In turn, the 35-year-old democratic socialist branded the president a “fascist” and pledged to fight him relentlessly if elected mayor.
Yet that animosity fell away late last year during their first White House meeting, where an amicable tone prevailed.
The thaw culminated in September at Gracie Mansion, where Trump said Mamdani had “great potential” to be a “terrific mayor.”
Mamdani returned the compliment by noting that the president had “built quite a bit of housing in our city.”
Despite the polite exchange, questions remain over how much substantive progress Mamdani can genuinely secure through Trump, including on immigration.
To date, Aghayeva’s release stands as one of the few concrete concessions Mamdani has obtained from Trump.
Aides on both sides are also discussing a multi-billion-dollar federally backed housing initiative in Queens, and last month Mamdani used his channel to Trump to help secure a temporary visa for a Ghanaian woman whose son was shot and killed in the Bronx.
Beyond those instances, few tangible results have emerged, though Trump’s decision not to enact punitive measures against New York is viewed by Mamdani’s allies as a win for the city.
Trump’s political standing is widely seen as weakened following the Republican Party’s loss of both houses of Congress in elections last Tuesday.
How this political shift will affect Trump’s willingness to engage with ideological adversaries such as Mamdani remains uncertain.
Miller’s appointment as chief of staff appears to signal little presidential interest in moderation, particularly on immigration policy.
Even so, the mayor said last week that he does not intend to stop seeking Trump’s assistance, despite “fierce” policy disagreements.
“We have found an area of common interest in the well-being of New York City, and as long as that can deliver for our city, I’m going to keep that door open,” Mamdani told Politico on Friday in Puerto Rico.
Mamdani and other elected officials from New York had gathered in Puerto Rico for the annual Somos political conference.
Two days later, in an interview on Fox News, a network Trump is known to watch regularly, Mamdani described a “productive relationship” with the president, saying the two text and speak by phone frequently:
“Through those conversations, we were able to get a New Yorker out of ICE detention. We were able to secure a visa for a grieving mother who would have otherwise had to watch her son’s funeral from thousands of miles away. What that tells me is: My job is to deliver for New Yorkers, and I have to work with whoever has the power to do that, wherever they may be.”

IRAM expert Oral Toğa assesses Middle East shifts after US vote

Netanyahu Arab party attack triggers crisis over coalition

Fico accuses Merz of blackmail over threat to veto EU budget

US Senate panel seeks records in Trump-linked crypto investigation

Europe ready for arms and missile control talks with Russia, FT says
-
 Diplomacy1 week ago
Secular dress code dispute exposes deeper Türkiye-Azerbaijan strains
-
 Russia2 weeks ago
US and Russia weigh energy deals and corporate return in peace talks
-
 Middle East2 weeks ago
US warns Gulf allies of possible Iran strikes after midterms
-
 Opinion2 weeks ago
Gaza exposes the myth of the “most moral army in the world”
-
 Europe5 days ago
EU urges citizens to prepare 72-hour survival kits for crises
-
 America2 weeks ago
Bolsonaro reportedly leaves Brazil on jet linked to scandal-hit firm
-
 Asia1 week ago
China expands Africa arms sales, displacing France and Western rivals
-
 Diplomacy2 weeks ago
Steinmeier seeks to de-escalate German-Chinese tensions on visit
