Europe
Chinese carmakers expand European share as Stellantis loses ground


Chinese brands are rapidly gaining market share in Europe. Exclusive data reveals which manufacturers are suffering the most from this new competition.
According to research by Handelsblatt, Chinese brands accounted for 8.7% of new vehicle registrations from January to July, compared with only 0.6% in 2021.
Based on an analysis of figures from the data service Dataforce, this share has nearly tripled compared with 2024 alone.
Concerns are growing in industry circles that this offensive by Chinese manufacturers will continue to accelerate and that price competition in Europe will intensify.
In the first seven months, approximately 780,000 new cars belonging to Chinese brands hit European roads, a figure almost equal to sales for the whole of 2025.
According to Handelsblatt’s analysis, the manufacturers initially expanded their presence in Southern and Eastern Europe, as well as in the United Kingdom.
Equipped with the experience gained there, they are now targeting the largest, but also the most challenging, passenger car market: Germany.
With sales of nearly three million new cars a year, the German market remains in the hands of German manufacturers.
In addition, Stellantis, the multi-brand group that includes Opel and Peugeot, alongside Toyota and Korean manufacturers Hyundai and Kia, hold significant market shares. These shares are now at risk.
Albert Waas, a partner at the consultancy firm BCG, says: “As a first step, Chinese carmakers are targeting the core business of high-volume manufacturers.”
In this segment, it is easier to increase visibility on the roads more quickly. Far Eastern brands are offering affordable compact and family cars, as well as an increasing number of SUV models.
Chinese manufacturers are benefiting from the growing electric vehicle segment in Europe, but they are also taking advantage of declining customer loyalty to established brands.
Opel parent company hit hardest
The biggest loser is Stellantis. The group’s market share in Europe currently stands at 15.5%. In 2021, this rate was still close to 21%. This represents a drop of just under 155,000 units.
According to the major bank UBS, the reason for this is that Stellantis experiences “significant overlap in terms of countries and segments” with Chinese brands. “Company-specific problems” also played a role in this situation.
Stellantis’s ambitious electric vehicle plans did not yield the expected results, and numerous product recalls were carried out due to quality defects stemming from cost-cutting measures.
Ford is also struggling with new competitors, and its market share fell from 4.6% to 3%. Among German manufacturers, the core Volkswagen brand was particularly affected. Its market share has fallen from 10.7% to 9.9% since 2021.
To a lesser extent, Japanese carmakers such as Nissan and Mazda, as well as Korean manufacturers such as Hyundai and Kia, also lost market share to Chinese brands.
On the other hand, Renault’s market share remained stable at around 6%. UBS attributes this to a “strong product cycle”. The French carmaker is launching numerous new electric models, such as the Renault 5 compact car, and these models are being well received.
Because Chinese cars are cheaper and in some cases technically superior, Europeans are becoming increasingly willing to purchase car brands from the Far East.
At the same time, Chinese manufacturers are being forced to expand more aggressively abroad. In the domestic market, a destructive price war continues among more than 100 competitors, in which almost no manufacturer can make a profit.
In addition, the automotive industry has lost its importance in China’s five-year plan.
Because the US is effectively closing its doors to Chinese manufacturers, these producers are focusing primarily on Europe.
According to experts, they can charge twice as much for their vehicles in this market as they do in China.
This explains why passenger car exports from the People’s Republic of China rose by 78% in August compared with the same month last year, reaching 894,000 vehicles.
In contrast, domestic sales contracted for the eleventh consecutive month, falling by almost a quarter to 1.55 million.
A few Chinese brands dominate the market
Even when Toyota entered the European market in the 1970s and Hyundai in the 1990s, there were warnings that established manufacturers could lose market share to Asian rivals.
What is new now is that Chinese manufacturers are making progress in the electric vehicle segment and in software, areas where they are considered leaders.
They are benefiting from the rapid surge in demand for electric cars in Europe, driven by government subsidies and high fuel prices caused by the war in Iran.
According to the analysis, China’s market share in electric cars in Europe has already reached 12.6%. In 2021, this rate was only 2.1%.
Volkswagen is feeling the impact of this situation: in 2021, the Wolfsburg-based company held an approximately 14% share in the electric vehicle segment, which was significantly smaller at the time. That figure is now below 8%.
Stellantis’s market share in electric cars, meanwhile, fell from over 14% to around 10%.
Dataforce counts 19 Chinese manufacturers in Europe. However, five brands account for 83% of sales.
BYD, the world’s largest electric car manufacturer, also leads in Europe. As of the end of July, the brand’s new registrations reached 217,000, and its market share stood at 2.4%.
BYD has thus already surpassed brands such as Volvo (202,000 units), Nissan (183,000), and Tesla (178,000).
New registration figures for the Fiat (262,000), Ford (272,000), and Opel (284,000) brands are also within BYD’s reach.
MG ranks just behind BYD with 211,000 registered vehicles. Formerly British, this brand is part of the Chinese holding company SAIC.
The manufacturer Chery holds a 1.7% market share in Europe through its Jaecoo and Omoda brands.
Leapmotor is experiencing particularly strong growth. The 65,000 registrations recorded by the end of July by Stellantis’s joint venture partner represent more than double the total figure for the whole of 2025.
The reason for this is a one-off factor: nearly 40% of Leapmotor’s registrations this year came from Italy.
There, the retail price of the T03 microcar dropped from its regular price of 18,900 euros to below 5,000 euros, thanks to a manufacturer discount and a government electric vehicle incentive.
Regional differences exist across Europe
Significant regional differences exist: in Spain, Portugal, Italy, and Greece, Chinese carmakers account for 11.4% of sales.
BCG expert Waas says: “In Southern Europe, people traditionally buy more small cars, and this is a segment where Chinese manufacturers are strong.”
In the south, Stellantis suffered particularly severe losses. In 2021, this multi-brand group accounted for almost a third of new registrations in the region; that figure is now only 22.3%.
Ford fell from 4.8% to 2.7%. Other high-volume brands such as Volkswagen and Renault, as well as Japanese and Korean manufacturers, are also experiencing slight declines.
In Eastern and Northern Europe, the situation among the losers is similar. However, the extent of the Chinese manufacturers’ presence varies between these regions: while their market share in Eastern Europe is 9.5%, it stands at 7.3% in Denmark, Sweden, Norway, and Finland.
In Central Europe, the share of Chinese manufacturers is 5.1%, a figure similar to that in France, an important automotive market. In Germany, this share is currently only 4.1%.
However, compared with the 2.3% rate recorded in 2025, this represents a dynamic increase.
This situation is also likely linked to the German government’s new electric vehicle support programme, from which Chinese brands have particularly benefited.
Matthias Schmidt of his eponymous consultancy says: “Loyalty to domestic brands in Germany and France remains a structural obstacle for Chinese carmakers.”
In Germany, the market shares of domestic brands have barely changed. In France, too, buyers continue to feel a strong attachment to Renault, Peugeot, and Citroen.
Chinese manufacturers have a particularly strong presence in the United Kingdom. A quarter of all vehicle registrations by Chinese brands in Europe took place in the United Kingdom. Their market share in this country hovers just below 16%.
Chinese manufacturers are increasingly shipping their electric vehicles to the United Kingdom because, unlike the European Union, no special tariffs are applied there.
In addition, their task is easier in the United Kingdom due to the absence of large-scale domestic manufacturers.
Premium segment remains largely unaffected
In the premium segment, however, attempts by Chinese manufacturers to gain a foothold in Europe have so far ended in failure.
The European market shares of Audi, BMW, and Mercedes-Benz have remained largely stable for years.
The carmaker Nio, which has a unique selling point with its battery-swapping technology, sold fewer than 500 vehicles in Europe this year.
Although Xpeng reached more than 24,000 units thanks to a significant increase, its market share remains below 0.3%. Zeekr, meanwhile, did not exceed 0.08%.
The reason is that Chinese brands appeal to a different customer base. Car dealer Burkhard Weller says: “Anyone who buys a Chinese car brand is a bargain hunter.”
In contrast, buyers of premium brands in Europe usually “are still investing in a certain image.”
Yet concern is also growing among premium manufacturers. As CEO Ola Kallenius has frequently emphasised, although Mercedes has not yet lost European market share to new rivals, he stated in a letter sent to employees this summer that Chinese competitors with “very lean cost structures and high innovation speed” are entering the European market.
Experts believe Xiaomi in particular has a strong future. The manufacturer plans to begin its international expansion in 2027.
Xiaomi founder Lei Jun said: “The first market will be Germany, the most difficult market in the world.” BYD also plans to expand the reach of its premium brand Denza in Germany.
Chinese automotive companies expected to grow further
UBS analysts forecast that Chinese manufacturers will increase their European market share to 20% by the end of the decade.
However, industry expert Schmidt estimates that their share of the all-electric vehicle market will not exceed 15%.
Schmidt argues that new Chinese manufacturers will compete with established rivals for the same customer base and will eventually begin to cannibalise each other’s market share.
Moreover, “established manufacturers are stepping up their efforts to protect their market share.”
Consequently, European brands are introducing more affordable electric cars to the market.
At Renault, the electric Twingo is already on sale for less than 20,000 euros.
Volkswagen plans to launch the ID.1 microcar at this price point in 2027.
Regulation is also affecting future developments. Since the EU began applying tariffs to electric cars in the autumn of 2024, Chinese carmakers have rapidly expanded their hybrid vehicle offerings.
Hybrid cars currently account for 53% of Chinese-origin vehicle registrations in Europe, compared with only 15% in 2021.
As a result, calls are growing among German politicians to impose tariffs on hybrid vehicles of Chinese origin.
This year, BYD overtook Volkswagen in plug-in hybrid vehicle registrations. For this reason, industry sources state: “If the German government cannot convince Europe that tariffs should be imposed on hybrid vehicles, then we have a problem.”






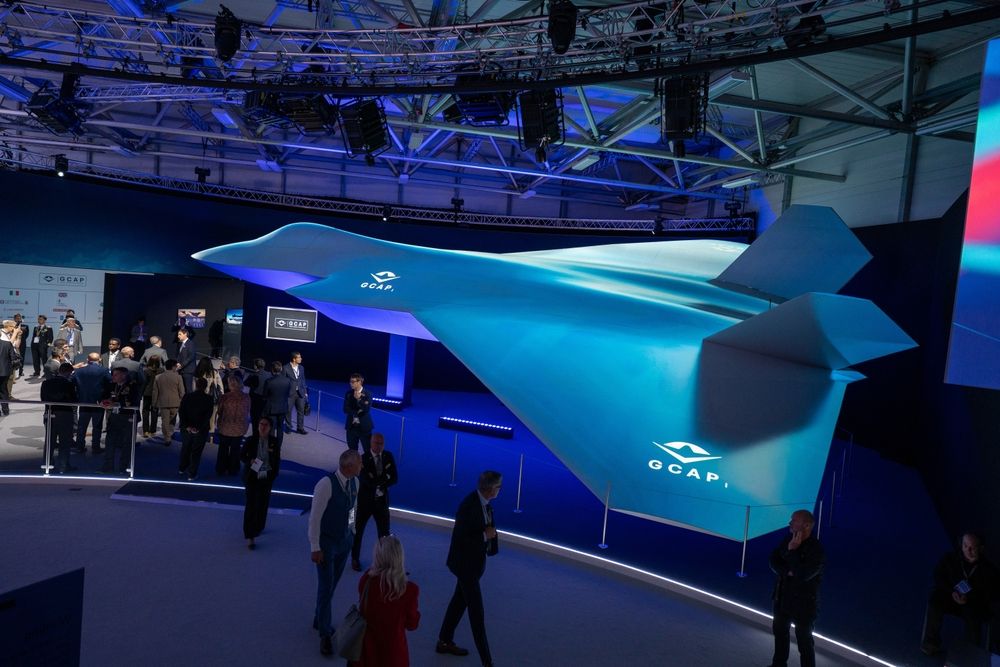
German Defence Ministry officials have advised Berlin to form a new fighter jet partnership with Sweden and Spain rather than join an existing UK-led consortium.
Internal ministry assessment notes obtained by Politico state that a trilateral arrangement among Germany, Sweden, and Spain represents a “more advantageous and promising” approach than joining the Global Combat Air Programme (GCAP) run by the UK, Italy, and Japan.
The proposal outlined in the document does not yet represent a final government decision, nor does it contain any indication that German Defence Minister Boris Pistorius has approved the recommendation.
The advice was drafted after Germany’s flagship project with France to build a next-generation fighter jet collapsed in June following years of industrial infighting.
Initiated in 2017 and later joined by Spain, the Future Combat Air System (FCAS) was conceived as a showcase initiative for European defence cooperation. The partnership aimed to develop an aircraft to replace Germany’s Eurofighter fleet starting in 2040.
However, the initiative foundered on disputes over operational control and workshare between France-based Dassault and Germany-based Airbus Defence and Space. Following unsuccessful rescue attempts at the political level, Berlin withdrew from the joint fighter project this year.
UK Prime Minister Andy Burnham raised the prospect of Germany joining GCAP during an 8 October meeting in Berlin with Friedrich Merz. The two leaders agreed that officials should continue discussions.
For Berlin, the choice carries implications that reach far beyond which model its air force will fly. The decision will determine who controls future military technology, which countries secure production contracts, and whether a new European partnership can avoid the frictions that dismantled FCAS.
Ministry assessment keeps distance from UK-partnered GCAP project
The ministry assessment listed several reservations regarding the GCAP project. The report argued that the existing programme focuses on operations beyond Germany’s capability requirements, whereas Berlin needs an aircraft better suited for missions over continental Europe.
The document also noted that German manufacturers would struggle to secure a significant share of development and production work within an already established partnership.
Invoking past experiences with the Eurofighter programme, which was developed in the 1990s and entered service in the early 2000s, the document took direct aim at British defence contractor BAE Systems.
The German Defence Ministry assessment accused BAE Systems of prioritizing exports over the development interests of Germany and Italy, warning that British dominance would prove incompatible with an equal partnership.
By contrast, the document stated that the military requirements of Germany, Sweden, and Spain align closely and that their starting positions are well balanced.
The assessment proposed an industrial partnership between aerospace giant Airbus and Sweden’s Saab, while recommending that the Saab-manufactured Gripen E fighter jet serve as a technological stepping stone until the new aircraft is developed.
The German Defence Ministry declined to comment on the matter. A separate ministry note, however, recorded British efforts to integrate Germany into GCAP as an observer or participant, asking German officials to examine potential industrial roles and military requirements.
An Airbus spokesperson said the company was “generally open to cooperation”, provided that German and Spanish industry secured a “substantial and equal role” across development, production, and operational phases.
“Purely political decisions without an industrial foundation remain insufficient,” the spokesperson said, urging authorities in Berlin and Madrid to clarify the path forward swiftly.
In an interview published in Handelsblatt on Monday, Airbus defence chief Michael Schollhorn pointed to ties with Saab, noting that the two companies have always worked well together.
A Saab spokesperson also indicated that the company is receptive to broad defence cooperation, including in fighter aircraft.
Emphasizing that large-scale collaborative projects are handled at the political level and that participation decisions rest with the respective governments, the spokesperson said: “All questions regarding potential Swedish participation should be directed to the Swedish government. Saab stands ready, as always, to support Sweden’s future fighter aircraft requirements.”
The European Union has returned to the idea of appointing an envoy to hold talks on Ukraine with Russian President Vladimir Putin.
According to sources familiar with the matter who spoke to Politico, this search gained fresh momentum following a visit to Russia by Steve Witkoff, the US special envoy.
During his trip, Witkoff proposed to Putin that Russia, the US, and Ukraine hold trilateral talks.
European countries, meanwhile, fear that Washington could accept terms unfavourable to Kyiv in negotiations that exclude them.
Sources speaking to Politico said the names being discussed for the envoy role include European Commission President Ursula von der Leyen, European Council President António Costa, and EU High Representative for Foreign Affairs and Security Policy Kaja Kallas.
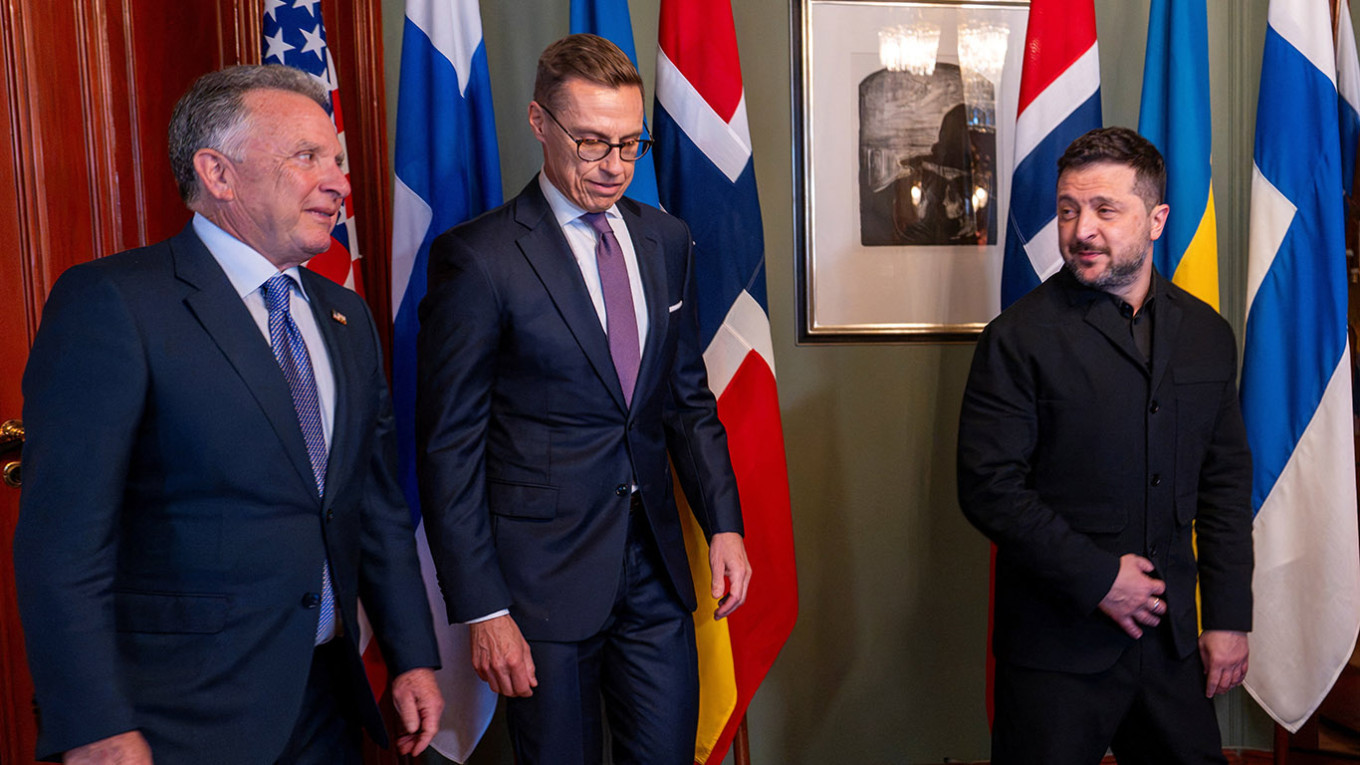
Some European diplomats believe Finnish President Alexander Stubb may be the most suitable candidate for the post.
Stubb’s good relations with Trump and Finland’s experience in dealing with Russia are cited among the factors setting him apart.
An unnamed EU diplomat described Stubb as the only European politician so far to have demonstrated senior-level leadership.
Another group of diplomats argues that Costa should lead the talks. European leaders asked Costa during last week’s EU summit in Brussels whether the time had come to speak with Putin.
Politico’s source recounted that exchange: “Costa said no, saying he would not speak to Putin right now. But if we want to play a role in the negotiations, Costa still needs to initiate dialogue with Putin.”
According to an assessment by another source, the European Council president could serve as a more neutral mediator than von der Leyen or Kallas, who are seen as overly focused on supporting Ukraine.
“Three or four people cannot go there with each of us speaking on behalf of the European Union,” one of the sources told the publication. “Ultimately, the choice of who represents the EU must be based on maximum efficiency, not on a personal power struggle or someone’s narcissistic ambitions.”
Politico previously reported in January that the EU was considering appointing a special representative for Ukraine negotiations. At the time, the initiative drew support from several European leaders, including French President Emmanuel Macron and Italian Prime Minister Giorgia Meloni.
Putin said he was ready to negotiate with European countries, but asserted that Europe had “no peace agenda” and stood “on the side of war”.
The Russian leader also named former German chancellor Gerhard Schröder as Moscow’s preferred negotiator from Europe.
Kallas ruled out such an appointment, noting that Schröder was “a lobbyist for Russian state companies” and would sit “on both sides of the negotiating table”.
Stubb details obstacles to talks and Oslo diplomatic drive
Finnish President Alexander Stubb said the principal obstacle to ending the war between Russia and Ukraine was the territorial issue.
Stubb took part in talks in Oslo with US envoy Steve Witkoff, who subsequently travelled to Saint Petersburg to meet Vladimir Putin.
As reported by the newspaper Helsingin Sanomat, Stubb stated that advancing the peace process required either bilateral talks between Russia and Ukraine or trilateral negotiations involving the US.
The Finnish president listed the other major items to be addressed within a settlement as US security guarantees for Ukraine and the construction of a new European security architecture after the war ends.
Without stating it outright, Stubb implied that the core issue within this framework was Ukraine’s NATO membership. The Finnish leader pointed to monitoring the ceasefire, establishing the line of contact, ensuring energy and food security, and exchanging prisoners as practical tasks.
Stubb also detailed the talks held in Oslo on 20 October, which included Witkoff, Ukrainian President Volodymyr Zelenskyy, and Norwegian Prime Minister Jonas Gahr Støre.
The discussions, which spanned approximately eight hours across various formats, had three objectives: to lower tensions in public discourse, to convey European and Ukrainian proposals to the US envoy before his visit to Russia, and to determine the next steps toward a peaceful settlement. Stubb announced that these goals had been achieved.
Moscow ready to resume trilateral talks in November
Witkoff met Putin in Saint Petersburg on Wednesday.
Following the meeting, Russian presidential aide Yuriy Ushakov announced that Moscow was prepared to resume trilateral negotiations with the US and Ukraine during the first half of November.
Ushakov also said that the EU and NATO had begun to “take a more serious approach” to Kremlin proposals on Ukraine, adding that “matters” were moving toward an end to the conflict.
Witkoff described the meeting as “constructive”.
Sources told Bloomberg in September that Putin continued to insist the Donetsk region must come fully under Russian control, expressing confidence that the territory would be captured within the next six months.
Putin previously set conditions for ending the war, demanding that Ukraine abandon plans to join NATO, maintain a neutral and non-nuclear status, and that anti-Russian sanctions be lifted.
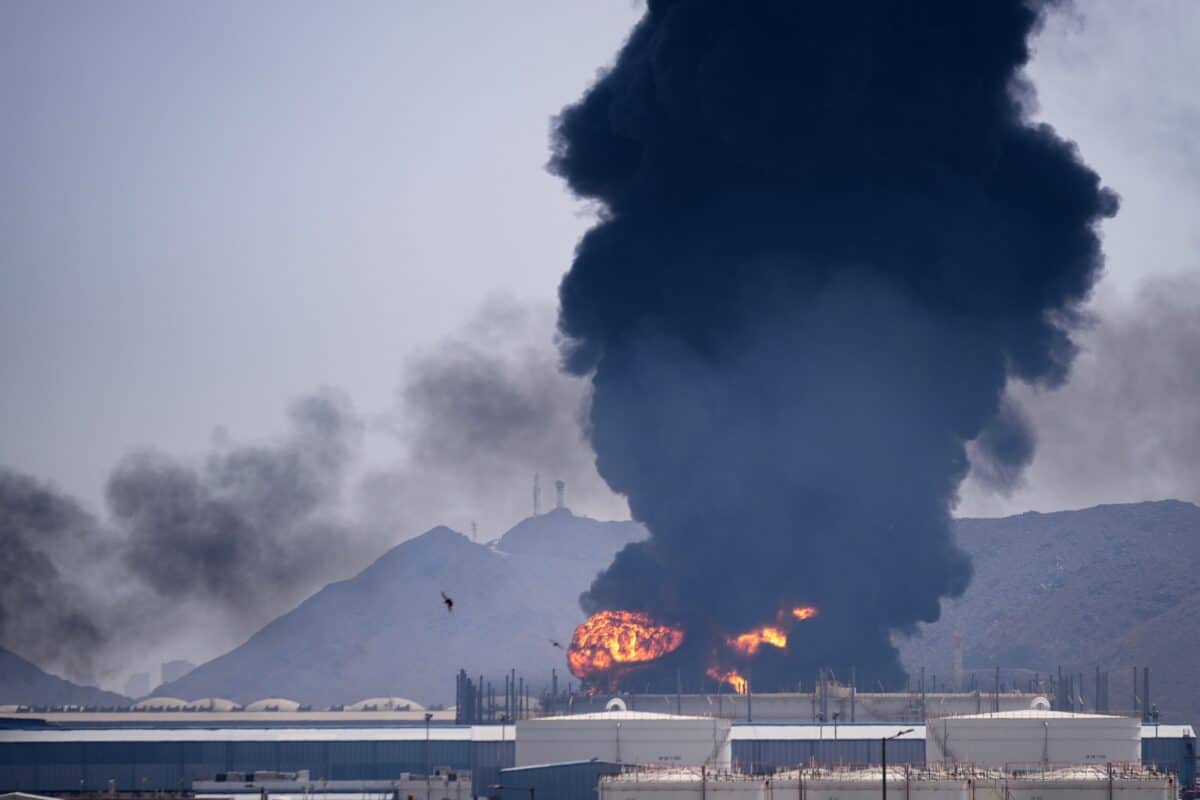
A comprehensive military operation planned by the Israeli military for 10 October did not take place because US President Donald Trump chose to avoid a broad conflict before the 3 November congressional midterm elections.
Preparations had been made on the orders of Prime Minister Benjamin Netanyahu for an aerial bombardment meant to last several days, according to a report by the Financial Times citing sources familiar with the matter.
The list of targets included nuclear facilities and locations associated with the Iranian leadership, along with power stations and other civilian infrastructure sites.
The planned strikes were projected to exceed the joint operation launched by the US and Israel in February in terms of intensity.
White House Deputy Press Secretary Anna Kelly told the newspaper: “The United States is not going to strike Iran at any point before the midterms.”
Kelly argued that the administration in Tehran was in distress both economically and militarily, adding that the blockade imposed on Iranian ports and US efforts to secure oil shipments through the Strait of Hormuz were producing results.
Speaking to the newspaper, one source addressed the possibility of strikes resuming in the coming weeks, saying: “There’s either going to be a deal or a strike.”
The same source reported that Washington aims for a comprehensive settlement that resolves the conflict over both the Strait of Hormuz and the nuclear programme, although it remained unclear whether the US would have participated directly in the cancelled operation.
Another source said the preparations for the operation might have served as leverage to pressure Tehran in negotiations, adding that the final decision on any new military step rests with the US president.
Hegseth reviews updated target list in Israel
An Israeli official said US Secretary of War Pete Hegseth visited Israel on 19 October to meet with Netanyahu and senior representatives.
Another source stated that the Israeli side presented an updated target list to its American counterparts, compiled with fresh intelligence and incorporating civilian infrastructure sites that had not been struck earlier this year.
The Pentagon did not respond to questions regarding the meetings, while Netanyahu’s office and the Israeli military declined to comment.
Despite the postponement of the operation, Trump and Netanyahu continued to issue military warnings to Iran in public.
In a video released on 19 October, Netanyahu addressed Trump, saying: “Donald, you said we need to finish this, and we will finish it together.” Speaking on speakerphone, Trump responded: “You’re a great warrior, and we’re going to prove it very soon.”
These engagements between the leaders coincide with critical election cycles in both countries.
Parliamentary elections in Israel are scheduled for 27 October, one week before the vote in the US.
Most public opinion polls in the country show the opposition bloc holding a narrow lead over Netanyahu’s coalition, though neither side commands a clear majority.
Axios, a US-based news outlet, previously reported that the Pentagon instructed military planners to finalize strike plans against Iran, though the directive specified no date and Trump had not reached a final decision.
On 15 October, CNN reported on plans to use the GBU-43/B munition, known as the “mother of all bombs”, against Iranian nuclear facilities, with US officials who spoke to the broadcaster expressing scepticism about the weapon’s ability to destroy deep bunkers.
While Tehran announced that it remains open to a diplomatic solution, it declared that any potential operation would draw a fierce response.
Iranian Foreign Minister Abbas Araghchi stressed that if its adversaries chose military conflict, the response would be “much harsher than before”.
Following the joint operation launched by the US and Israel on 28 February, Iran retaliated by striking targets across the region and restricting maritime passage through the Strait of Hormuz.
Although the parties reached an agreement in June covering a ceasefire and negotiations to lift the blockade in the strait, reciprocal strikes between the US and Iran have not ceased.

German officials urge fighter jet alliance with Sweden and Spain

US wealthy demolish multimillion-dollar mansions for land

US and Israel weigh Iran strikes after midterm vote, reports say

Pentagon plans covert spy ring for economic war on China, report says

EU reopens debate on naming envoy for Ukraine talks with Putin
-
 America2 weeks ago
How will Brazil’s presidential runoff work?
-
 Europe2 weeks ago
Berlin Left Party backs Israel’s right to exist for coalition pact
-
 Diplomacy2 weeks ago
The West is preparing for war not with Russia, but with its own people, French analyst Georges Kuzmanovic insists
-
 Russia2 weeks ago
71 EU lawmakers demand closure of Russian Houses in 15 member states
-
 Europe2 weeks ago
MI6 investigates potential leaks after former BND chief is detained
-
 Russia2 weeks ago
US and Russian figures discuss American stake in Nord Stream lines
-
 Russia2 weeks ago
Drone strike shuts down Yandex data centre in Russia’s Ryazan region
-
 America1 week ago
Trump weighs presidential memorandum to cut surging US diesel prices
