Opinion
Obligation for a structural change in Russia: How to exit from the oil-gas economy?


By analyzing the past, present, and future of Russia’s two major export commodities, I will discuss the impacts of the current developments on the budget and the inevitable need for changes in its economic strategy in this article.
First of all, one of the key notions below, “distant nations,” needs some background. Whether or not they are members of the Commonwealth of Independent States (CIS), all former Soviet countries are still regarded as close foreign countries. The rest of the world is likewise distant foreign countries. Here, we only do calculations and charts for distant foreign countries. After leaving China out, European countries constituted its overwhelming majority. Therefore, the conclusion will reflect the impacts of Western sanctions on Russia’s two primary exports and sources of budgetary income (oil and natural gas).
Let me state something upfront for the sake of the reader who is not a fan of lengthy writings. Using 2021 as a baseline, Russia will lose 35% – 40% of its oil and petroleum product exports and 50% of its natural gas exports this year. However, this is only part of Russia’s financial setback. Before the onset of the deep crisis in the first half of 2022, rising energy prices had significantly boosted the country’s income. However, the situation has now reversed, with oil and petroleum products discounted by nearly half their market price.
Natural gas
We’ll begin by explaining how the graph below was drawn, which data was utilized how and why, and how estimations were made.

In order to avoid “misjudgments, speculations, and inconsistencies,” the Federal Customs Administration (FCA) has not released information since April. Hence there is currently no official data for 2022. Gas exports to Europe (in transit via Ukraine) are projected to reach 30 bcm in 2023. At 80% capacity, gas is plummeted through Blue Stream, which equals a maximum of 16 bcm through this line. The largest volume that can be plummeted to China is between 23 and 24 bcm.
It was not disclosed how much natural gas Turkey purchased from Russia last year. However, on July 18, Yuri Ushakov, an advisor to Putin, reported that 12.8 bcm of gas (7.1 Blue Stream, 5.7 Turk Stream) had plummeted in the year’s first half. In addition, the export amounts to China and Europe (excluding “close countries” like the Baltic) are known. Based on these statistics, I estimated the gas export to Turkey at 21.70 bcm. This figure matches what Kommersant reported to the Turkish Customs Administration: 21.50 bcm.
Data from Gazprom and the FTS do not quite match. Gazprom’s export figures are always greater than FTA’s. This also held true in the year 2021. Novak reported on December 28 that Gazprom had exported 185.1 bcm to distant countries. However, according to FTS, total exports to distant countries were 170 bcm. I derived figures on the graph from Gazprom statistics. Additionally, I referred to the Central Bank’s yearly average natural gas prices. Like the FTA, the Central Bank did not integrate the averages of 2022 and afterward into its statistics. Therefore, I utilized the calculations provided by the RIA based on the ICE data as the average natural gas price in 2022: $1260.8 per mcm.
I picked two sets of prices for 2023. First, the price on December 31, 2022, is $844.3, assuming it remains relatively stable throughout the year. If scenario two plays out, temperatures in Europe will remain above seasonal norms this winter and spring, the wind will continue its record-setting speed, Brussels will strike a long-term oil deal with Qatar, relations with Algeria will improve, and the United States will replace the monopoly profit with reasonable prices. Although not all of them are realistic, I would predict that costs can be cut in half if all take place.
For 2023, I have assumed a decline in exports of 30% and a total decrease to 70-75 bcm. If this occurs, European countries will import more than twice as much natural gas from the United States as they did from Russia this year.
Novak said on December 28 that gas exports totaled 100.9 bcm last year. It is a record low. In 1990, it was 110 bcm. On January 16, Miller reported that 15.5 bcm of gas was sold to China. However, Neftegaz announced on January 2 that this figure might be appraised as 18.2 bcm due to an increase in contractual obligations. The graph relies on this second figure.
Miller also said annual gas shipments to China will reach 48 bcm by 2025. But the graph shows that even in this case, the demand from the East cannot make up for the European market loss (at least for now).
I have omitted liquefied natural gas (LNG) from the charts. This export may increase partially. Nearly 16 million tons of LNG were sent to Asia in 2022, and Europe received 15.7 million tons in total. This amount is approximately equal to 44 bcm of gas. Although this figure is not inconsequential, it is not anticipated to increase beyond this level in 2023 owing to the challenges of insurance-reinsurance in transport and tankers other than dependency on Western technology. Furthermore, it is unlikely that the rise in LNG exports would come close to replacing the 180-200 bcm of the potential capacity of the Russia-Europe pipelines before NATO destroyed Nord Stream 1 and 2.
Even by an optimistic prediction, the total demand of China, Belarus, and Turkey in 2023 would only amount to 60 bcm, less than a quarter of Gazprom’s entire supply capacity. So, this is the picture based on the most optimistic estimates: In 2021, Russia globally sold almost 240 bcm of natural gas. By 2023, however, it will only be able to ship a maximum of 45 bcm LNG and export 30 bcm via pipeline to “unfriendly” countries and 60 bcm to neutral countries.
Oil
Let’s look at oil.
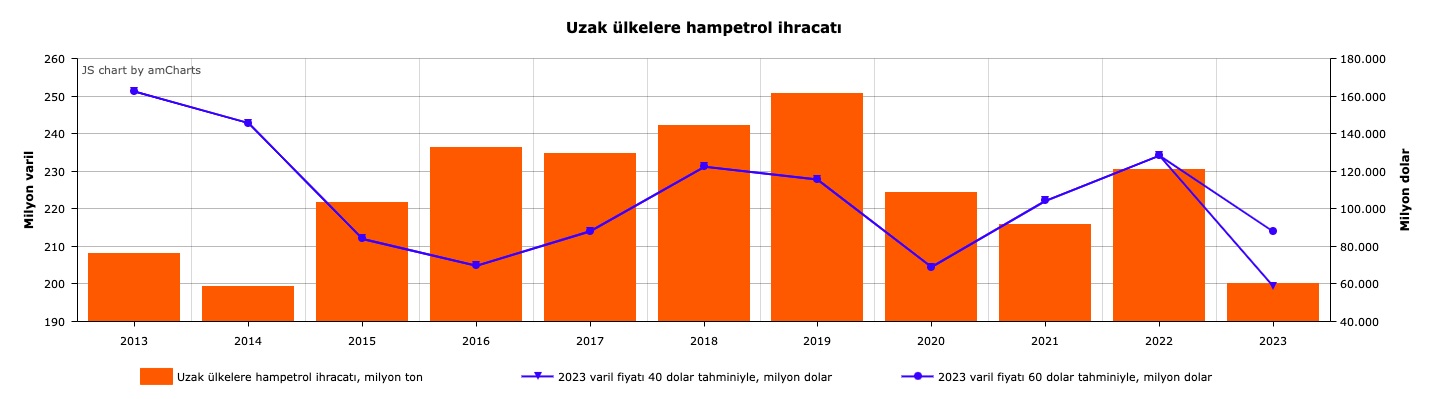
I will prepare the chart for the same time frame (2013-2023); however, I will be excluding the data from China, Turkey, and India. For these three reasons:
1) There are gaps in the dataset. On the bright side, it is at least evident that China had been a reliable purchaser (between 70-72 million tons) until 2022.
2) At least as of 2020, Turkish and Russian sources contradict in terms of figures for Turkey’s purchases.
3) Prior to 2022, India was not a huge market for Russian exports, but after that year, it became one of the most important hubs for Russian oil. The share of Russian oil export to India rocketed from 1% on February 24 to 18% in May. India, Turkey, Singapore, and even the United Arab Emirates (UAE) dilute Russian oil before being sold to obfuscate its origin. It is unclear, however, how they would act after Russia’s counter-sanctions go into effect on February 1. Thus, qualifying the data of these three countries will not provide useful insights.
Nevertheless, we may get insights from the figures of crude oil exports and the total income of the annual average oil price.
Like natural gas, I have completed the chart relying on the data of “distant countries” and my own estimates. Similar to natural gas, I predicted a range of $40 to $60 for the barrel price of Ural oil in 2023. These predictions align with the scenarios the Central Bank announced in May. Considering the $60 maximum price, the likely range for the price of Ural oil is between these two extremes. To “distant countries,” I projected 200 million tons of oil exports in 2023. As a result, Russia will lose 90% of its crude oil exports to Europe due to the sanctions, which may cost the country $40 to $70 billion.
I will not go into technical details of the implementation of the sanctions and embargo. Still, it’s important to know that in its broadest sense (including both land and sea traffic), it will be implemented over the course of 6-8 months. This is why the European market has not been totally lost: Bruegel, a European think tank, has shown that 75% of Russia’s oil and petroleum product exports to Europe are sent offshore, while just 25% are transported via pipeline. Germany and Poland, two main consumers, have reduced their purchases, while the Hungarian government has blocked a full ban. Orbán has ensured that the oil pipelines of Slovakia and the Czech Republic from Russia, in addition to those of Hungary, will remain open.
However, the insurance and reinsurance restrictions directly impact exports to India and China. Unless a stable solution to this issue is found (a partial solution is already available; the Russian National Reinsurance Company carries out the reinsurance), overall exports may fall further. Similar to natural gas, compensating the European market with Asia cannot happen in one day.
My estimations for potential losses are in line with these predictions as well. AlfaBank reported an expected loss of $50 billion; for Reuters, it is $40 billion to $54 billion, and for Energy Aspects, $60 billion. Increasing the amount of oil exported may improve the situation, which is feasible if the methods to circumvent the sanctions are broadened. A significant increase in the $40-$60 range for the sale of Ural oil appears unlikely.
These two charts depict a very critical scenario for 2023: Excluding petroleum products and LNG, we may expect Russia’s oil and natural gas income to be between $89.3 and $149.4 billion. This means a revenue drop of between $106 and $166 billion compared to the previous year.
Budget
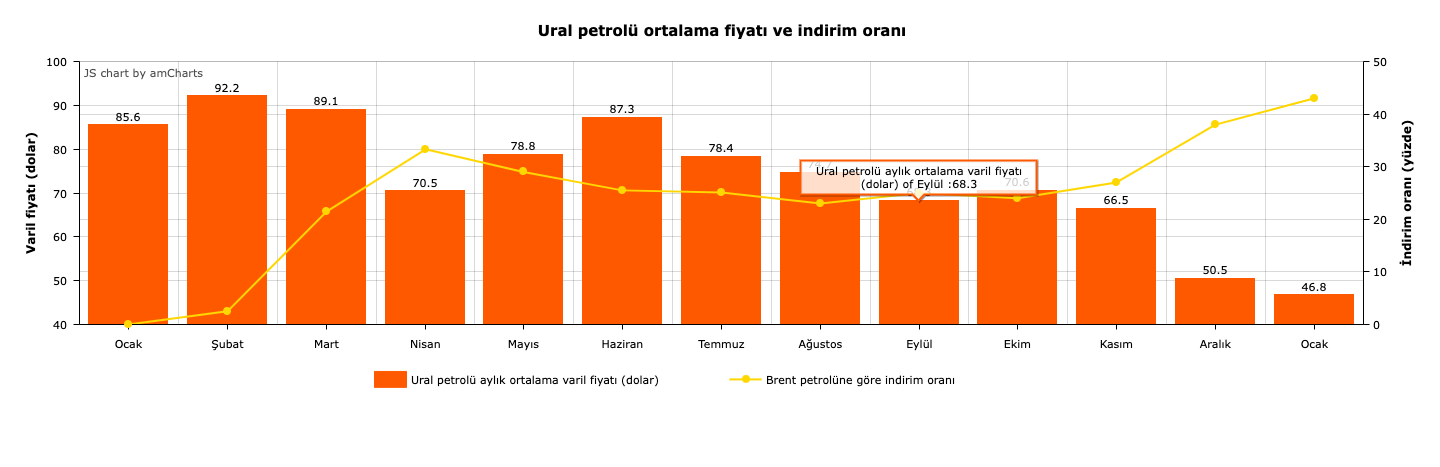
Budget revenues determined by the 2022 budget law were 25 trillion rubles, but roughly extra 2.5 trillion rubles actually went into the treasury last year. Yet budget expenditures were above this increase; during the year-end press conference, Finance Minister Siluanov said that “around 30 trillion rubles” had been spent. Despite a significant discount in Ural oil (shown in the third chart), oil prices were much higher than in the previous year, and natural gas revenues were at a record level until December 5. And these are the reasons for the increase in income. The greater rise in expense was owing to, in addition to the direct (military expenditures) effect of the Ukrainian operation, the increase in government subsidies to belligerent individuals and their families, and most usually low-income people. The budget, traditionally having a surplus, ran a deficit for the first time in April and was covered for the rest of the year by Gazprom and Rosneft.

The Ministry of Finance had predicted that the price of Ural oil per barrel would be $70.1 in 2023, $67.5 in 2024, and $65.25 in 2025. However, at least for this year, it is quite unlikely that the forecast will come true. In any case, Ural oil was nearly always sold at a discount, but the price difference was generally little more than a few dollars. However, huge price differences appeared after February 24, and the average discount is roughly 30 percent from that date to the end of the year. The discount rate was relatively stable between July and October at about 20-25 percent, but it spiked sharply once the maximum price was published on December 5. Since December 30, it has fluctuated daily between 45-55% as of January 20. In addition, it is still cheaper than $60, the price cap. In contrast, the last year’s price average of Ural oil was $76.09.
The situation with natural gas is similar. According to the explanatory note in the draft budget for 2023–2025 and the official forecast for the 2024–2025 planning period, natural gas exports (total of distant and close countries) fell by 31% in 2023 compared to the previous year, landing at 142 bcm, and will average 125 bcm annually for the next two years. However, these figures should be considered too optimistic because total exports via pipelines may decrease to 90–93 bcm this year if natural gas exports to distant countries reach 70–75 bcm as expected.
According to the most reasonable estimates of the Ministry of Finance, in 2023, if the price of Ural oil per barrel stays at $50 and daily output does not surpass 10 million barrels, the government would get at least $2.1 trillion less in oil and gas revenue in 2023, and the deficit will rise to $5 trillion, instead of the anticipated $2.9 trillion (2 percent of GDP). (In addition to crude oil, other petroleum products, natural gas, coal, etc., will impact this deficit.)
Suppose Ural oil prices remain at about $62-$63 per barrel. In that case, the Ministry of Finance intends to sell yuan from the National Wealth Fund and issue bonds to cover the deficit without raising the tax burden on the bourgeoisie. Alternatively, the government decides to seize “excessive profit” on carbon and fertilizer (this is the Kremlin’s optimal solution; I looked into it further when analyzing Putin’s September 7 speech at the Eastern Economic Forum), to increase the share of the budget in the dividends of state companies (this is the “financial bloc’s” optimal solution), and to issue a new tax regulation, if it fails, or the discounted oil price drops further. The Kremlin sees raising the tax burden on the great bourgeoisie as the best way to ensure that the welfare of the people remains stable or, if feasible, is elevated by state aid. In contrast, the “fiscal bloc” would rather burden the public by increasing indirect taxes. In other words, the bourgeoisie or the people must contribute to cover the budget deficit. As a result, the “conflicting alliance” between “the potent and the impotent” continues.
Conclusion
These are, of course, just estimates anyway. But one thing is clear enough: The traditional economic paradigm (oil and gas economies) is rapidly becoming obsolete. A structural shift in the economy is inevitable. This can be done in two ways: Medium and large private capital shifts from unproductive trade or the production of raw materials for export to industrial output for the domestic market, or the state expands its role as an economic regulator.
While the first way may help in the consolidation of capitalism but given the comprador nature of private capital in Russia, it is unrealistic to assume that it will serve as the primary means. It will continue to be an alternative for the bourgeoisie is eager to fill in the lacuna created by the foreign money leaving Russia. The local bourgeoisie is flexing its muscles to seize closed and closing foreign financial and industrial institutions, so one of the reasons why the ruble has depreciated in the past month is the demand for foreign currencies for purchases. Yet, the comprador nature of capital still prevails. In the first three quarters of last year, the financial-bloc-backed bourgeoisie managed to invest abroad 2.5 trillion rubles, or 10 percent of the budget’s income. On the other hand, taking the first way for structural shift results in the bourgeoisie’s political power being consolidated and empowered, posing a challenge to Bonapartism. Finally, the greatest exporter of raw materials, the state sees no gain in income through the first way, exacerbating the structural problem. Thus, the state must serve as the driving force of structural change.







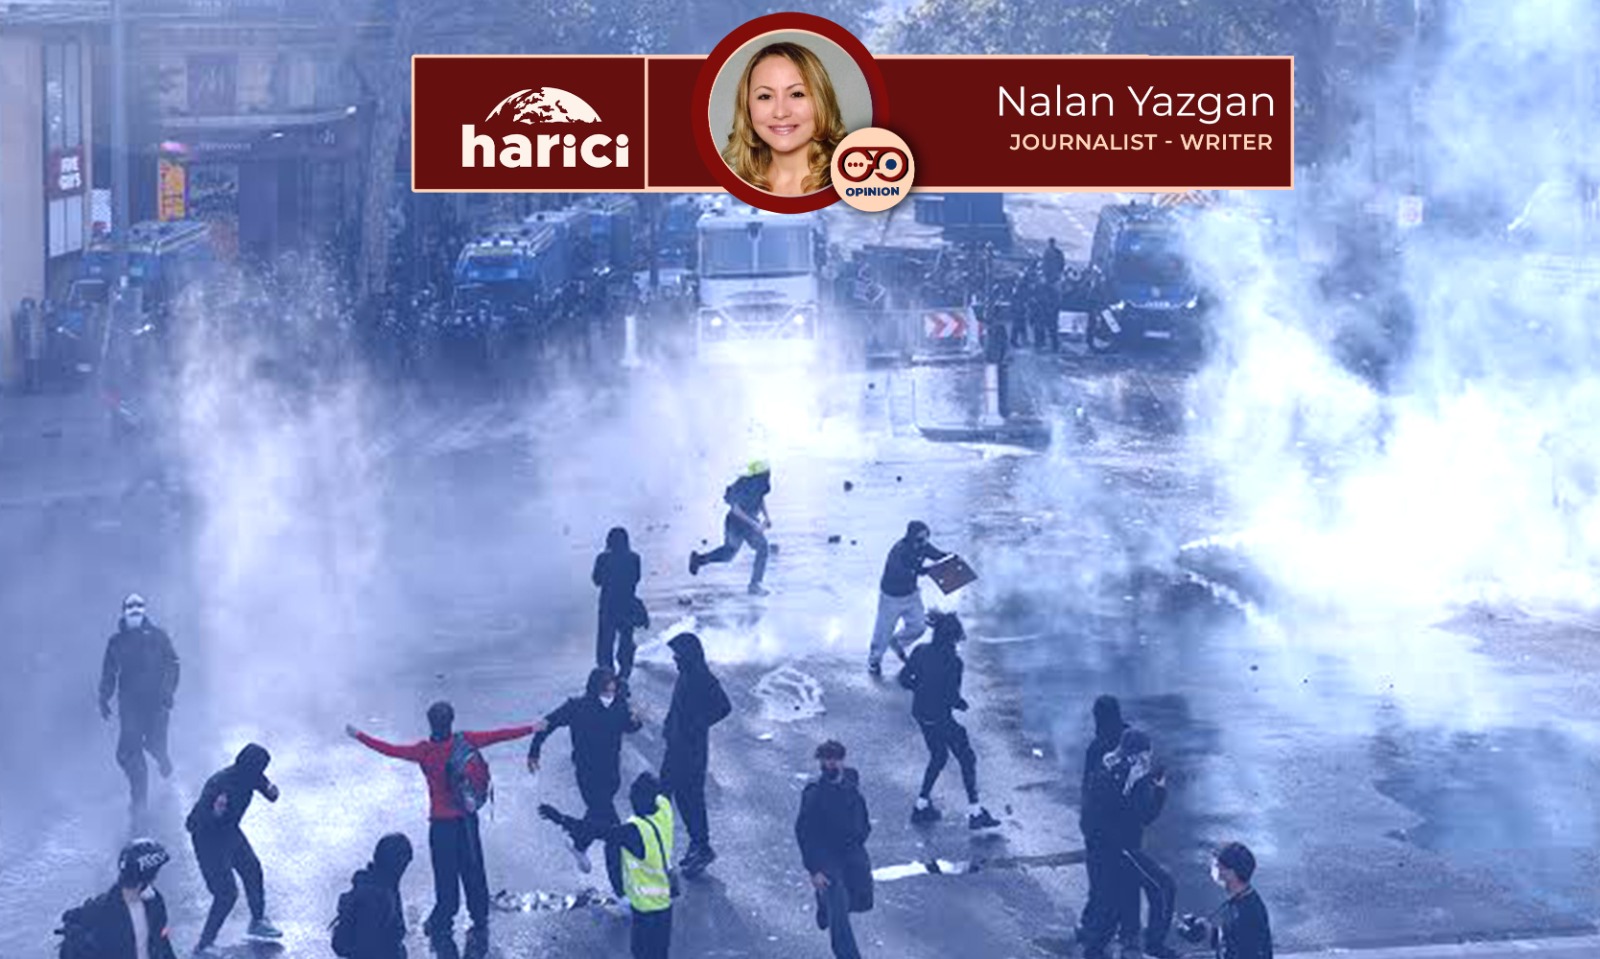
The streets of France have turned into a stage not merely for anger against the government, but for a deep-seated mistrust of the state’s approach to security. The blurring of the line between peaceful demonstrators and looters, lingering questions over police conduct, and the media’s refocusing on the immigration debate are bringing the country to the brink of a political reckoning far deeper than a routine public-order crisis.
In France, a government does not have to wait for an electoral defeat to lose its legitimacy. Sometimes, slogans chanted in a public square, tear gas fired down a boulevard, crowds penned in at the exit of a cordoned-off street, and testimonies of unhindered looting in shops only hundreds of metres away suffice to expose just how fragile the bond of trust between state and society has become.
Events in Paris on Saturday, 17 October point to precisely such a political fracture. Planned demonstrations with the participation of student unions, trade unions, and the Yellow Vests were marked throughout the day by police crackdowns, disputes over march routes, looting in the city centre, and widespread criticism of the government’s perceived inadequacy. The scene that emerged by evening suggested that France was grappling not merely with an issue of public order, but with a burgeoning crisis of confidence regarding the state’s impartiality and political motives.
Whom does the state permit to take to the streets, whom does it obstruct, and which forms of violence does it intervene against, and to what degree? The answer to this question may prove decisive in understanding France’s current political impasse.
The shadow of 17 October 1961
It is impossible to view the date of these demonstrations as a mere coincidence on the calendar. On 17 October 1961, a peaceful demonstration in Paris supporting Algerian independence was brutally crushed by the French police. Scores of people were killed, with some demonstrators drowned after being thrown into the River Seine. The event remains etched in memory as one of the darkest chapters in France’s colonial history and state-sponsored violence.
Sixty-five years later, as police interventions, youth rage, and the state’s stance on the right to protest are debated once again on the streets of Paris on 17 October, the resurgence of this historical memory was inevitable.
This memory may hold a distinct meaning, especially for French citizens of North African descent. Yet it would also be a mistake to reduce all the young people taking part in the demonstrations to a single identity, immigrant origin, or political motivation.
To what extent has the French Republic truly reckoned with the legacy of its colonial past and the relationship its security apparatus maintains with diverse segments of society?
Looters on the streets, where are the police?
Individuals dressed in black and associated in the public eye with the Black Bloc broke into shops at various locations, damaged businesses, and engaged in looting.
While peaceful demonstrators marched under a heavy police presence, fierce criticism arose that looting in certain areas had been allowed to unfold unchecked.
It is striking that while 14,000 police officers were deployed across the capital during the Pope’s visit to Paris, only 10,000 officers in total were assigned across the whole of France for the demonstrations of 17 October.
To which areas were police resources allocated? Had intelligence services assessed the risk of looting beforehand? While a robust security presence flanked the routes of peaceful marches, why was the same effectiveness not demonstrated in safeguarding commercial districts?
The deployment of elite units trained to quell urban unrest, such as CRS 8, does not resolve these questions. On the contrary, the failure to contain the incidents despite the presence of specialized units calls the quality of planning and coordination into question.
A political reckoning extending from Marseille to Limoges
The debate in Paris soon reverberated across the country’s other cities. In a televised address, the socialist mayor of Marseille stated that he had requested police reinforcements from the government, yet the units dispatched fell short given the scale and requirements of the city.
The mayor’s most striking allegation was that while looters stormed Marseille City Hall, the Hôtel de Ville, police officers stood roughly 200 metres away and failed to intervene. Stating that he possessed security camera footage, the mayor affirmed that he would await the scrutiny of a Parliamentary Commission of Inquiry and demand an explanation from the government.
The mayor of Limoges likewise issued what amounted to an ultimatum to the government, demanding the reconstruction of the torched town hall and the full reimbursement of costs. According to the mayor, the government had failed to protect a public building and neglected to provide the police with the necessary resources and backing.
These statements emerging from two distinct cities demonstrate that a new confrontation over security policy has arisen between local authorities and the central government. How security resources are allocated, which risks are prioritized, and whether the warnings of local administrations are heeded must all be brought to light.
The deepening scrutiny over the administration’s stance was compounded by President Emmanuel Macron’s refusal to accept the resignation tendered by Interior Minister Laurent Nuñez. The rejection of the resignation raises the question of whether the executive aims to preserve the chain of accountability, or fears that a political reshuffle would only exacerbate the crisis.
In either case, the government faces a crisis of trust.
An eight-minute speech and unanswered demands
Macron’s roughly eight-minute televised address failed to meet expectations regarding the political dimensions of the crisis. The president announced that he would meet with student unions and that the prime minister would engage with political parties, yet he presented neither tangible decisions nor a comprehensive political roadmap.
Education spending, police violence, the Palestinian cause, anti-fascism, and backlash against the Macron administration appear to have ceased being disparate issues in the eyes of the youth.
To be sure, the true strength of a state lies not in silencing its people and streets, but in addressing legitimate demands. It must not be forgotten that institutions unable to adapt and change are destined to break.

By its very nature, foreign policy feeds into and draws nourishment from numerous, disparate, and varied fields. It is a domain with manifold and diverse inputs. For foreign policy is examined alongside a broad array of subjects, ranging from geography to history, economics to intelligence, and military might to public diplomacy, commonly termed soft power elements.
The capacity of the state, that is, the scale of the state, or in other words the aggregate of its elements of power (namely political, economic, military, and soft power components), is decisive in foreign policy. Geography is decisive in foreign policy. Commercial relations are decisive in foreign policy. Energy dependence on another country or countries, if present, is decisive in foreign policy. Foreign policy cannot be conducted in spite of these four factors.
There is more. A country’s capacity, its scale, does not increase overnight, from one day to the next. It requires planning. It requires national consensus. It requires time. It requires preparation. Nor are these enough. The regional and global environment, the conjuncture, and the international plane must also allow for it. The stance of allies and adversaries is, of course, also important.
For the international environment is, by its nature, complex. It is an environment rife with contradiction, turmoil, conflict, and tension. To draw an analogy, the person in the driver’s seat of foreign policy is not a motorist speeding along the road as they please. There are things they must not forget, rules they must obey, red lights, vehicles speeding up from behind, a truck moving ahead, and a heavy vehicle hurtling toward them from the opposite direction.
Success in foreign policy does not arrive simply because a politician we like has become foreign minister. For a foreign minister is only as effective as the power, capacity, and weight of their country. One must accept this plain truth.
Moreover, there are simple, straightforward questions that reveal whether foreign policy, which some find deeply complex and inscrutable, is successful or not.
There are undoubtedly ways to measure the effectiveness, prestige, influence, and success of foreign policy.
For instance, the number of countries that respect a passport, how many countries can be visited visa-free, and how many countries impose visa requirements and grant those visas only with great difficulty are important indicators of a country’s standing.
Let us take ourselves as an example. Which countries require a visa for the Turkish passport? Which ones do not? Is it easy for our citizens to obtain visas for the countries they primarily wish to visit?
Let us give another example from the Turkic world.
On the Cyprus issue, which we regard as a national cause across government and opposition, right and left, Kemalist and Milli Görüş adherents alike, how many countries have we succeeded in having recognize the TRNC? Why do the Turkic states (Azerbaijan, Kazakhstan, Kyrgyzstan, Turkmenistan, Uzbekistan) not recognize the TRNC? Far from recognizing the TRNC, how do the Turkic states in Central Asia (Turkistan) explain to Ankara their developing relations with the Greek Cypriot Administration of Southern Cyprus, which Türkiye does not recognize, their appointment of ambassadors, and their recognition of Southern Cyprus as the island’s sole legitimate government?
We must also ask this question, of course: What is the state of Türkiye’s bilateral trade with the Turkic states?
Let us give an example of the relationship between foreign policy and big capital.
In which countries are big capital circles, among the greatest supporters of the ruling bloc, winning major tenders?
In our country, across both ruling and opposition ranks, there is a political party order that supports Türkiye’s EU membership. Yet how much progress has been made on EU membership?
Why is US President Trump not keeping the promises he made to Türkiye at the NATO summit held in Ankara a few months ago?
How many contracts has the new regime in Syria, the al-Sharaa administration, awarded to Turkish companies for the reconstruction of its country?
Has the government in Libya that Türkiye supports paid the money owed to Turkish construction firms, outstanding for years?
How does Qatar, with whom our relations are very good, explain its developing ties, energy agreements, and joint military drills with Greece and the Greek Cypriot Administration, disregarding our sensitivities?
Who is the addressee of the harsh statements used in recent weeks by Azerbaijan, which we view as “two states, one nation”? To what extent does Azerbaijan share Türkiye’s policy on Israel? What does Türkiye think about the scale, depth, and intimacy of Azerbaijan-Israel relations?
These questions can certainly be multiplied.
Yet without taking into account the scale of the state and observing the criteria for measuring foreign policy, no sound assessment can be made.
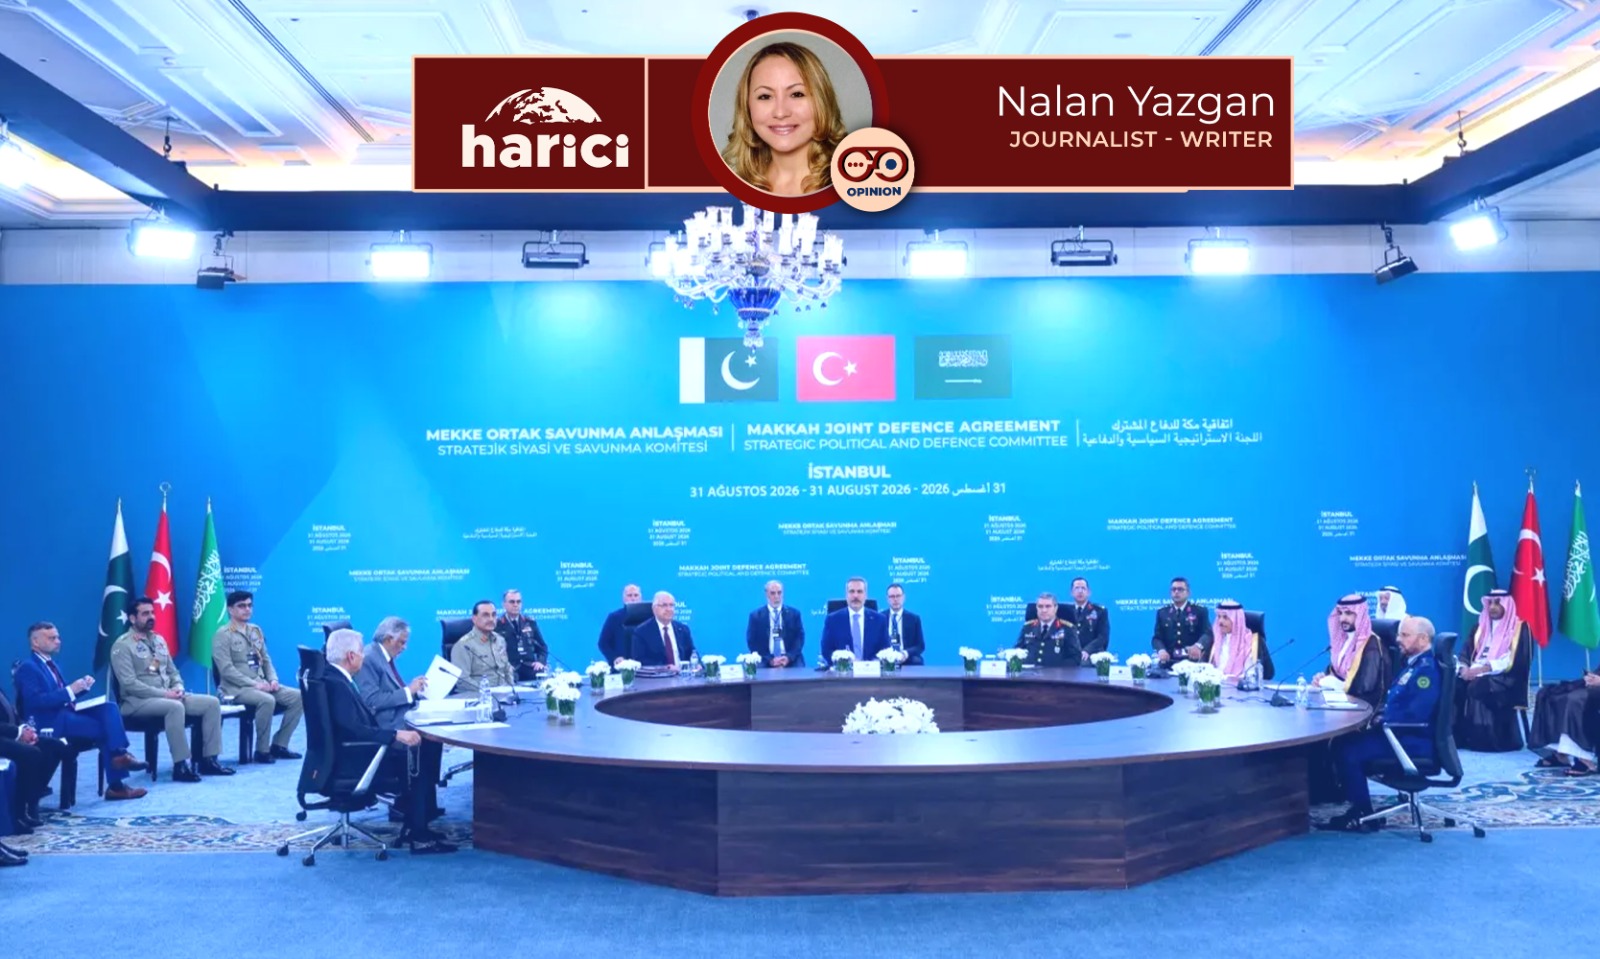
In the Middle East, war is no longer waged merely to seize territory. The true contest turns on who will control the energy pipelines, trade routes, ports, and railways of tomorrow. Missiles may strike cities today, but the maps of the future are being drawn through transport and energy corridors.
In this context, interpreting Türkiye’s presence in the Mecca Alliance solely as military support for Saudi Arabian security remains incomplete; it fails to explain why two states that viewed each other with mutual suspicion until recently would take steps toward a cooperation close enough to constitute a shared destiny.
Alongside Saudi Arabia’s existential motives, Ankara’s participation in this alliance is anchored in a profound geopolitical foundation: to position itself within, and if possible at the very centre of, the Middle East’s reconfigured energy and transport corridors.
Today, it cannot be said that Riyadh and Ankara see eye to eye on every regional issue. The threat perceptions and priorities of the two countries do not, quite naturally, entirely coincide. On the geopolitical chessboard, partnerships do not always arise from identical agendas. When reasons are sufficiently compelling, particularly existential ones, they can override political differences and enable common ground along the same strategic path.
A new war of corridors unfolds in the Middle East
On one side lies IMEC (India-Middle East-Europe Economic Corridor), planned to extend from India through the United Arab Emirates, Saudi Arabia, Jordan, and Israel to Europe. On the other stands the Development Road, which aims to link the Persian Gulf across Iraq to Türkiye, and onward to Europe.
These two undertakings are, of course, far more than mere transport projects. They represent two divergent geopolitical answers to where the future flow of trade and energy between Asia and Europe will traverse; for Türkiye, this issue is of vital importance.
If a corridor system taking shape to Türkiye’s south, beyond Ankara’s orbit, becomes permanent, Türkiye could forfeit not only an economic opportunity but also a substantial portion of its strategic centrality in the Middle East. It is through this prism that the Mecca Alliance must be evaluated.
Türkiye’s seat at the same table with Saudi Arabia signifies more than military solidarity. Riyadh and Ankara must sit together to avoid exclusion from the region’s emergent security and economic architecture, for the security of a corridor and the corridor itself are no longer separate matters.
The Strait of Hormuz, the Red Sea, the Bab al-Mandab, and the Suez Canal are links in the very same chain. A security crisis in one directly impacts the others. While the vulnerability of Hormuz makes alternative export routes for Gulf oil indispensable, instability across the Red Sea heightens the strategic cost of Suez.
Saudi Arabia’s alternative pipelines connecting its eastern oil fields to Red Sea terminals are therefore not merely energy infrastructure; they are strategic bypasses mitigating dependence on Hormuz.
For Türkiye, the Development Road fulfills the same function across a broader geography. Stretching from the Persian Gulf through Iraq to Türkiye, and from Türkiye into Europe, this artery possesses the potential to forge a new overland backbone connecting the Gulf to the Mediterranean and Europe. As security concerns in the Red Sea mount and the vulnerability of Suez deepens, the value of this route rises accordingly.
The Hejaz Railway: Revived once again
The return of the Hejaz Railway to the regional agenda signifies far more than mere nostalgia. Once linking Istanbul to Damascus, Amman, and the Hejaz, the railway served as one of the primary transport and logistical arteries of the Ottoman geography.
Reviving the idea of the Hejaz Railway could become the emblem of Türkiye’s drive to reimagine its historical transport connections between the Gulf, the Hejaz, and the Levant through modern rail, energy, and logistics networks.
The objective here is not to restore the past, but to transpose the strategic logic of that historical geographical linkage into the twenty-first century. For this reason, Türkiye’s role in the Mecca Alliance and the resurgence of the Hejaz Railway project must be viewed as components of the same overarching picture.
Corridors do not consist solely of energy pipelines. Railways, ports, highways, electrical interconnectors, logistical hubs, and security architectures are all facets of the same geopolitical grid, and safeguarding these networks requires political alliances.
Herein lies the strategic significance of Saudi Arabia and Türkiye sitting at the same table in Mecca, even at a juncture when their views on Syria diverge.
Ankara and Riyadh do not need to agree on every subject. Yet neither wishes to see the new map of the Middle East drawn to its detriment. Türkiye’s aim is not to build an anti-bloc against any specific country alongside Saudi Arabia; rather, the goal is to avoid exclusion from the future energy and trade systems of the Middle East, while securing a decisive voice in establishing their security architecture.
Hence, for Türkiye, the Mecca Alliance is far more than a simple defence pact. Securing the Development Road, shielding Gulf energy corridors, stabilising the Red Sea, rethinking connections across the Hejaz and the Levant, and bolstering trade corridors reaching Europe all intersect within this single strategic equation.
In this equation, Türkiye’s foremost advantage remains its geography. Ankara sits at the northern terminus of the overland routes linking the Gulf to Europe; within NATO; and at the crossroads connecting the Black Sea, the Caucasus, the Eastern Mediterranean, and the Middle East.
Will Türkiye become one of the powers shaping the Middle East’s energy and trade architecture over the coming decades, or will it be reduced to a mere transit state traversed by routes designed by others? That question defines the true strategic significance of the Mecca Alliance for Ankara.
In the Middle East of tomorrow, it will be impossible to separate the corridor carrying energy, the security framework protecting that corridor, and the alliance constructing that security framework.
Whoever controls the corridor shapes commerce. Whoever guarantees the routes through which trade flows holds sway over the regional balance of power. This is the true dimension of the contest currently underway in the Middle East.
A succession of distinct and largely mutually exclusive ambitions are competing for dominance in the current climate: India’s linkage to Europe, the Gulf’s new economic horizons, Saudi Arabia’s alternative energy routes, the security crisis in the Red Sea, the strategic weight of Hormuz, and Türkiye’s aspiration to open outward to Europe via the Development Road. Ironically, perhaps, the conflict that will decide which corridor underpins global stability has already begun, and it will likely continue spreading to new fronts. Regrettably, the fires in our region appear poised to intensify long before they abate.

“The AfD is not a fascist party, but a party for fascists”

Nokia and ICEYE sign deal to build sovereign Ukraine satellite network

Mélenchon’s “new France” vision triggers fierce cross-party debate

US envoy says Syria interim leader Sharaa seeks Israel normalization

Unauthorised AI agents access customer accounts at major US banks
-
 Europe2 weeks ago
Berlin Left Party backs Israel’s right to exist for coalition pact
-
 America2 weeks ago
Trump weighs presidential memorandum to cut surging US diesel prices
-
 Diplomacy2 weeks ago
SWP urges backing for Gulf trade routes bypassing Strait of Hormuz
-
 Diplomacy2 weeks ago
EU and China reach preliminary deal to curb hybrid car imports
-
 America2 weeks ago
Thiel targets Pope and Obama over AI in new ‘Antichrist’ lectures
-
 Europe2 weeks ago
LSE study finds post-bailout Greece turned into a cafe economy
-
 Russia2 weeks ago
Russia relaxes diesel export curbs after talks with Trump
-
 America2 weeks ago
Energy firms enlist ex-US officials to tap Venezuelan oil
