Europe
Rheinmetall charts a course to become the world’s second-largest defense company

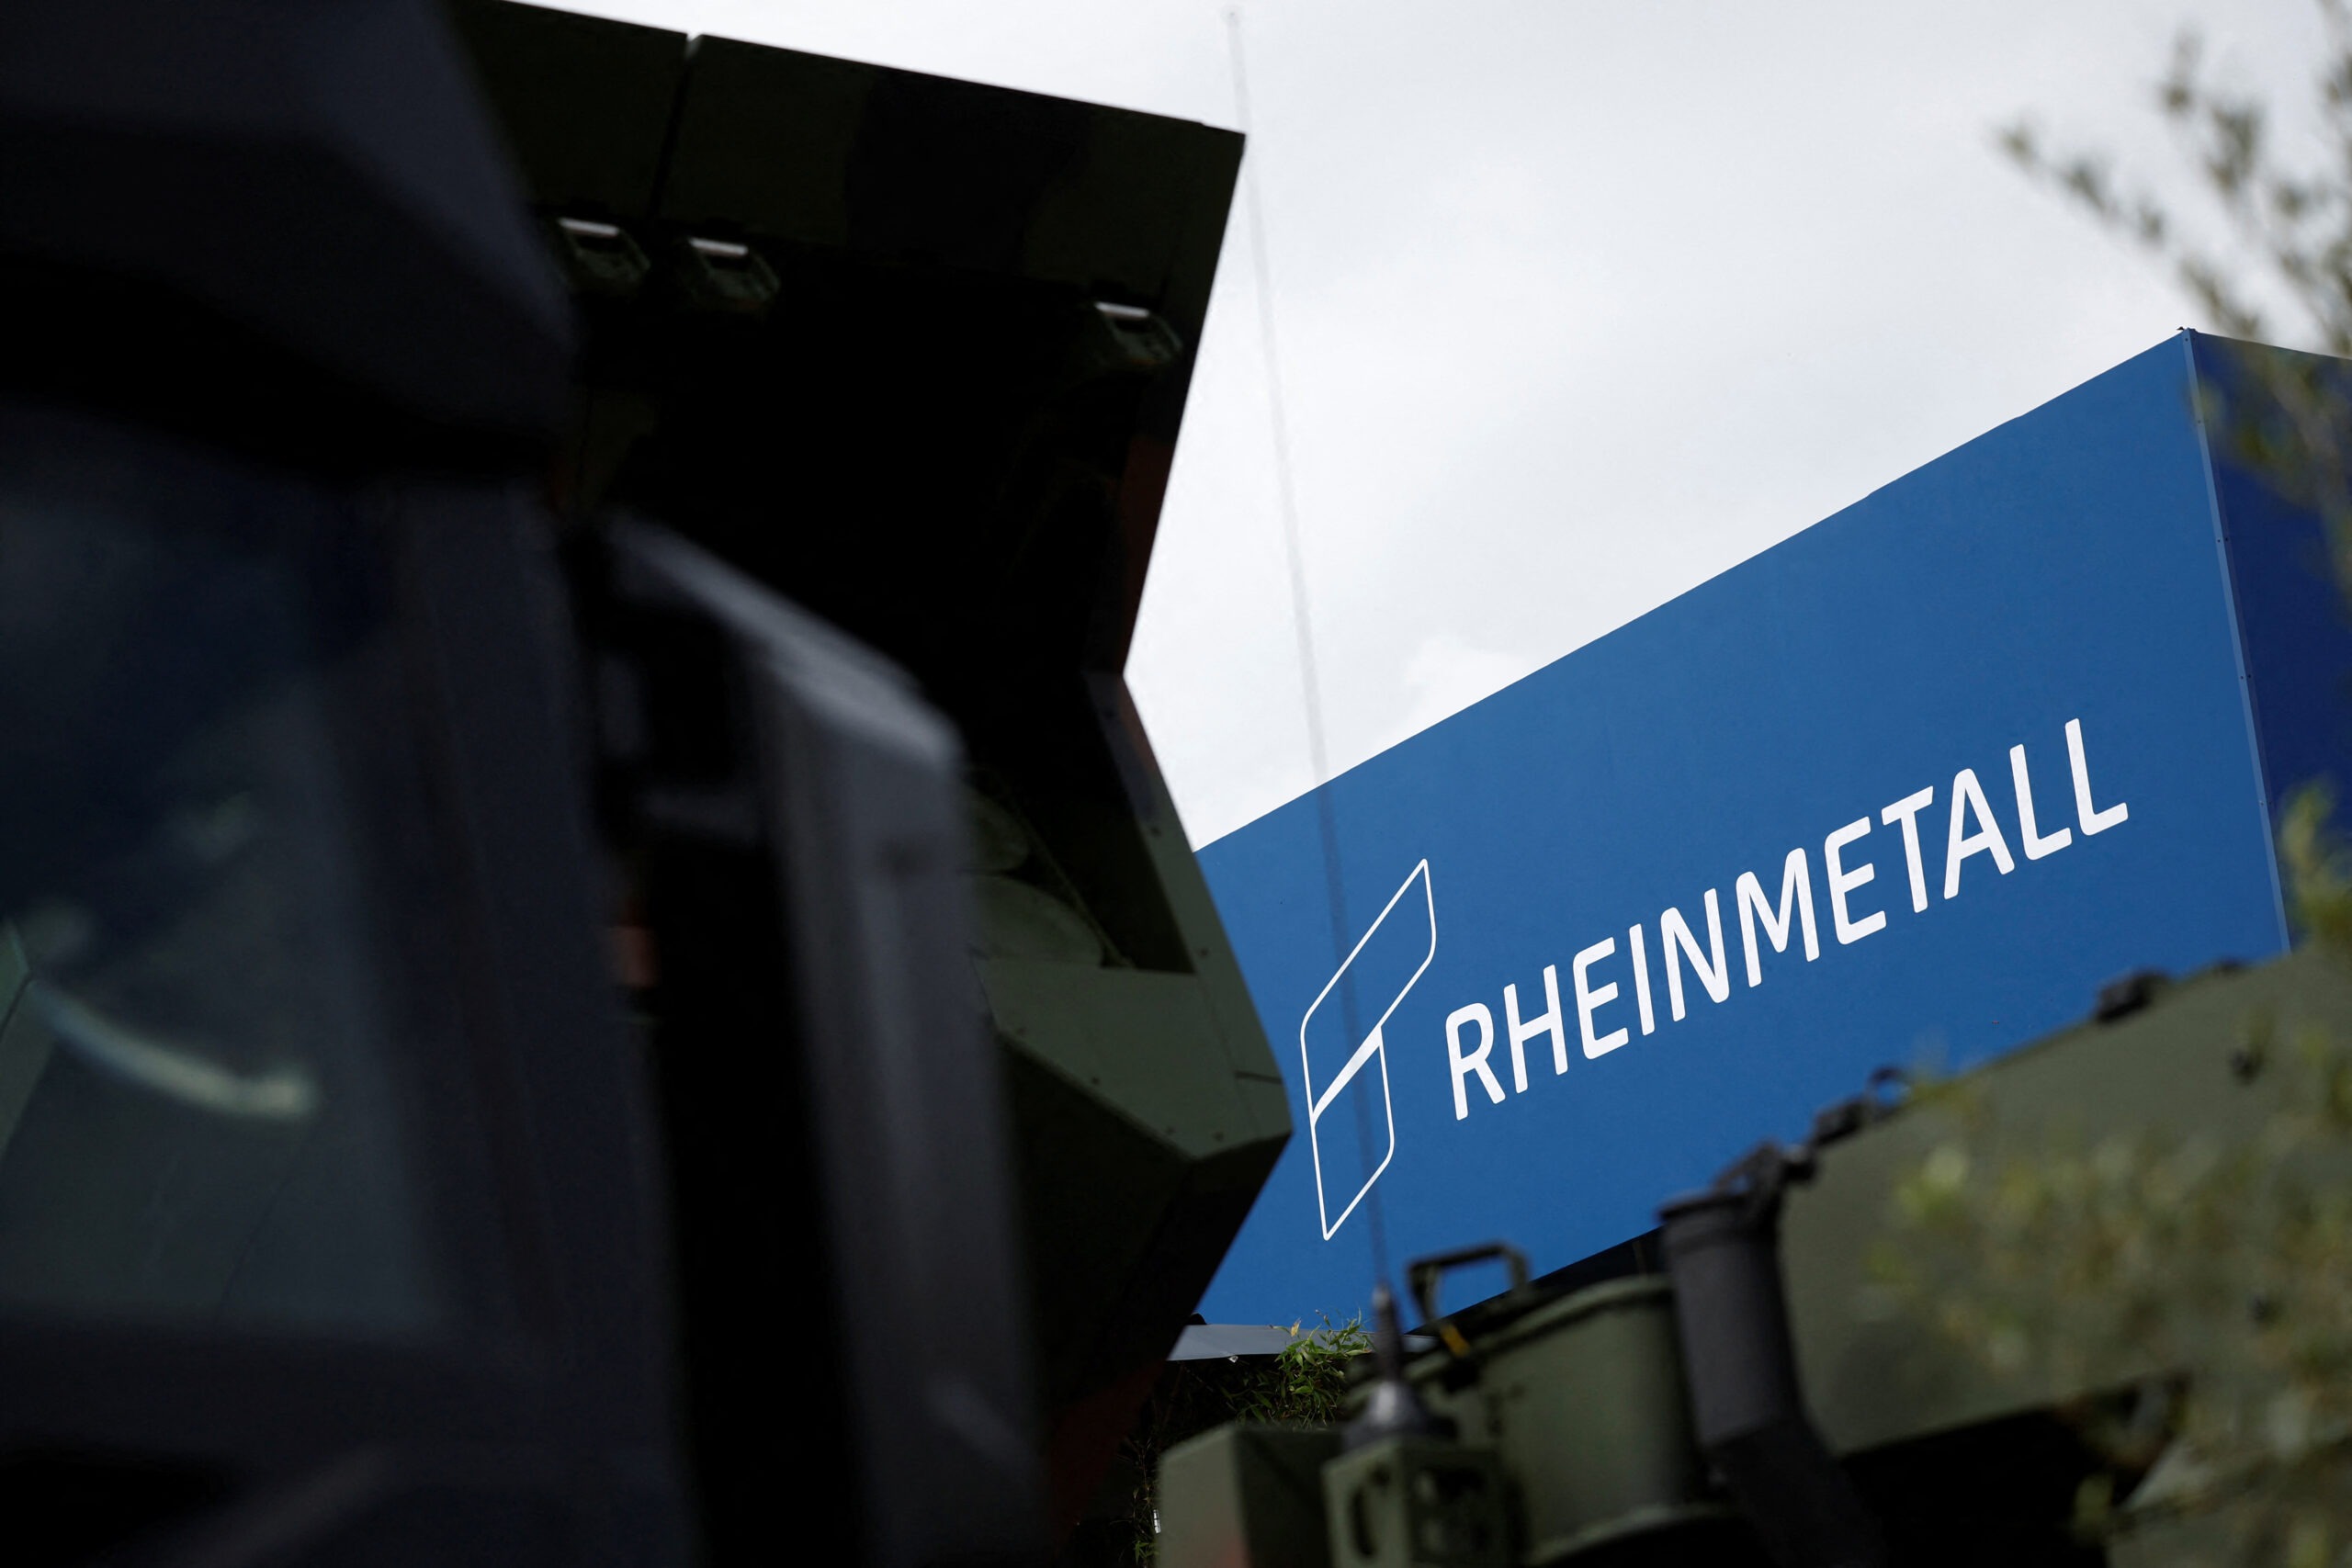
The German arms conglomerate Rheinmetall is systematically expanding into numerous new areas of the defense industry and plans to become one of the top three defense companies in the world.
The company, which traditionally produces tanks, artillery, and ammunition, is now entering the drone and satellite production markets.
According to an analysis in German Foreign Policy, Rheinmetall is thus transforming into a company that not only produces weapons and ammunition for future battlefields but also manufactures the unmanned aerial vehicles flying above them and the satellites that survey the conflict and its surroundings.
While Rheinmetall’s arms sales were only €3.7 billion in 2020, total sales are expected to reach €50 billion by 2030 following the divestment of its civilian automotive division.
Based on current figures, this would place the company second among global defense corporations, behind the US giant Lockheed Martin, which recorded defense sales of €55.5 billion in 2024. In Europe, Rheinmetall will be the largest ammunition manufacturer.
Europe’s largest ammunition manufacturer
Rheinmetall expects ammunition production to constitute the largest share of its sales, reaching €14 to €16 billion by 2030.
The Düsseldorf-based arms manufacturer is already Europe’s largest ammunition producer, thanks in part to the acquisition of its Spanish competitor Expal, which was completed in the summer of 2023.
While Rheinmetall produced approximately 60,000 units of 120mm tank ammunition in 2022, it plans to produce 240,000 units by 2027. For 155mm caliber artillery ammunition, the group aims to increase production from 70,000 rounds in 2022 to 1.1 million rounds in 2027, and 1.5 million rounds by 2030.
The production of medium-caliber ammunition for air defense will be quadrupled by 2030 compared to 2022, reaching 4 million rounds. To achieve this, Rheinmetall is expanding its plant in Unterlüß to become the largest ammunition factory in Europe, and possibly the world, according to a statement by CEO Armin Papperger at the new factory’s opening in late August.
A key customer for the company is the German Armed Forces, which increased its framework agreement for the supply of tank ammunition alone to approximately €4 billion in 2023. Rheinmetall is also building a series of new ammunition and gunpowder factories in countries such as Lithuania, Latvia, Bulgaria, and Romania.
Diversification in tank production
Rheinmetall aims to achieve its second-highest partial sales figure in the combat vehicle business, with a target of €13 to €15 billion in 2030.
The group is involved in the construction of numerous long-standing tanks, including the Leopard main battle tank, for which Rheinmetall primarily produces the smoothbore cannon, and the GTK Boxer wheeled armored vehicle.
In the future, Rheinmetall is focusing particularly on the Lynx infantry fighting vehicle and the Panther main battle tank. The KF41 Lynx was introduced in 2018; Hungary and Italy have placed firm orders for the vehicle so far. CEO Papperger hopes to sell more than 6,000 Lynx infantry fighting vehicles, at least if it emerges victorious in the ongoing selection process by the US armed forces.
Rheinmetall is also focusing on the KF51 Panther main battle tank, which is being touted as a potential successor to the Leopard. This tank is a competitor to the German-French MGCS (Main Ground Combat System) battle tank project, which has made no progress.
Rheinmetall has already received firm purchase commitments for the KF51 Panther: one from Hungary and another from Italy. Here, Rheinmetall is partnering with Leonardo.
In Italy, Rheinmetall operates as a supplier in a joint venture with the Italian defense group Leonardo.
SPOCK satellites: The digitalization offensive
Rheinmetall expects additional sales of €8 to €10 billion in its digitalization business segment, which includes the satellite business. The Düsseldorf-based tank manufacturer is entering this market from scratch.
The background for this is the digital networking of weapon systems traditionally produced by Rheinmetall on the battlefield. This includes network connectivity with reconnaissance satellites.
To produce these, Rheinmetall has established a joint venture with the Finnish startup Iceye, which is considered an international leader in the production of satellites with SAR (Synthetic Aperture Radar) technology.
When using SAR satellites, microwaves are emitted, and their echoes are measured to create high-resolution images of events on the ground, even at night or in poor weather conditions.
Rheinmetall holds a 60% stake in the joint venture, which will operate its production at the Neuss facility, while Iceye holds a 40% stake. The initial plan is to produce satellites for the German Armed Forces’ “Panzer Brigade 45” unit in Lithuania for approximately €1.76 billion.
The reconnaissance system will be named SPOCK (Space-based System for Persistent Operational C2 and Kill-chain). Competing firms were displeased that the contract was awarded without a tender process, which was a clear advantage for Rheinmetall.
Kamikaze drones
Rheinmetall aims for additional sales of €3 to €4 billion in the air defense segment by 2030. This is also a relatively new area for the company.
In July, Rheinmetall, in collaboration with the US defense giant Lockheed Martin, opened a factory in Weeze, North Rhine-Westphalia, that produces fuselage parts for the US F-35 fighter jet. This was the first step into the aviation industry.
The group is also working with various external companies to gain expertise in drone production. For example, it collaborates with the Israeli company UVision, founded in 2011 and specializing in drone manufacturing, with which it primarily produces Hero kamikaze drones.
Recently, this joint venture received an order to supply millions of euros worth of Hero drones to a NATO country.
The Düsseldorf-based group signed a collaboration agreement for drone defense with the US startup Anduril in 2024 and expanded it this year to include drone production. Anduril is considered the world’s largest military startup.
Rheinmetall also works with Auterion, a drone specialist founded in Switzerland and now based in the US. According to reports, Rheinmetall is currently planning to build a drone factory in the Baltic states.
New goals in the maritime sector
The new maritime division is also expected to generate a turnover of approximately €5 billion by 2030.
This division will be created through the acquisition of Naval Vessels Lürssen (NVL), the naval division of the Lürssen shipyard in Bremen, with the acquisition expected to be completed by early 2026.
Rheinmetall hopes this will create certain synergies with its tank-building operations but, above all, allow it to enter the extremely costly warship construction market. “In the future, we will be a significant player on land, at sea, in the air, and in space. Rheinmetall is thus transforming into a cross-domain systems house,” said CEO Papperger.
NVL has primarily built corvettes; the company currently owns four shipyards in Hamburg (Blohm + Voss, Norderwerft), Wolgast (Peene-Werft), and Wilhelmshaven (Neue Jadewerft).
According to reports, the corvettes, which will soon be produced by Rheinmetall’s maritime division rather than NVL, could be equipped with new weapons that Rheinmetall is currently developing in collaboration with the US company Lockheed Martin.
“The current conflict situation shows that military application capabilities are becoming increasingly important in the maritime sector as well,” says Rheinmetall.
Transatlantic orientation is critical for Rheinmetall
Rheinmetall is one of the companies in the German defense industry with a clear transatlantic orientation. Its shareholders include well-known financial firms from the US, though none of them approach the 10% ownership threshold.
According to Rheinmetall’s current information, the largest single investor is BlackRock, with a 7.0% stake. It is followed by Bank of America (4.64%), Morgan Stanley (4.37%), Goldman Sachs (4.06%), and the Swiss UBS Group (3.83%).
More importantly, Rheinmetall is actively seeking orders from the US armed forces, the world’s largest arms buyer, and is collaborating very closely with US companies, including Lockheed Martin.
On the other hand, Rheinmetall also produces weapon systems labeled as “ITAR-free.” These are systems manufactured without US components and are therefore not subject to the US International Traffic in Arms Regulations.
The SAR satellites produced by Iceye—and in the future, in collaboration with Rheinmetall—are “ITAR-free” and thus independent of US influence.





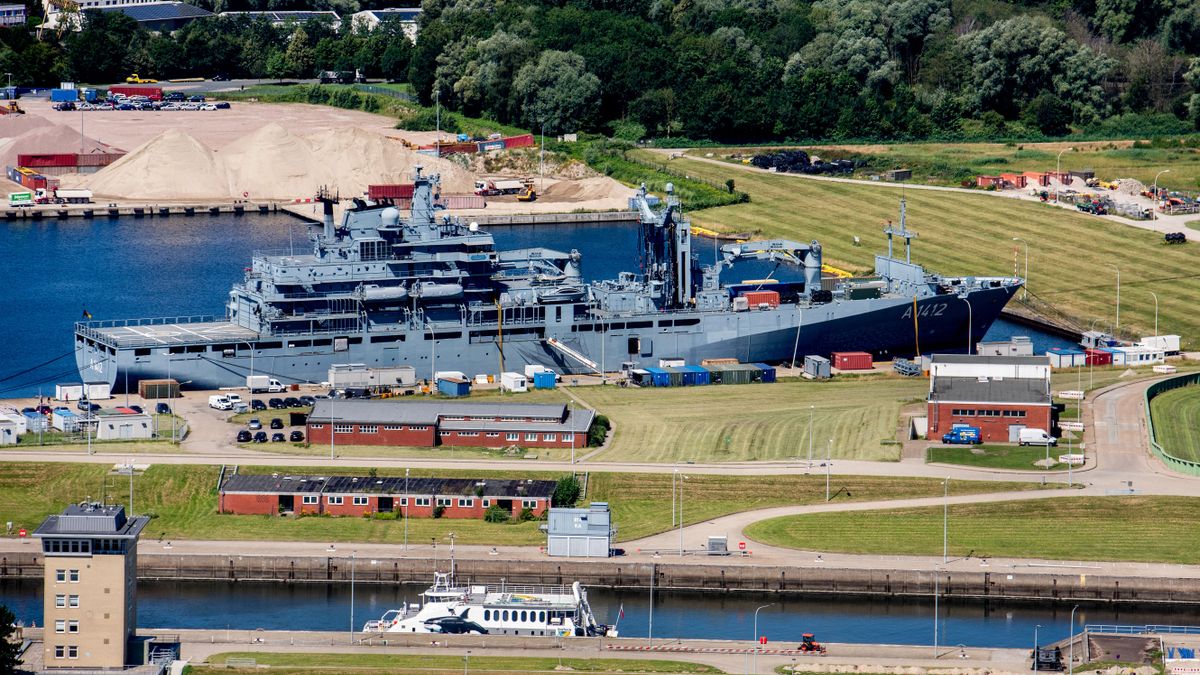
With the transformation of the port of Bremerhaven into a high-capacity military hub and the prospective establishment of a fifth German naval base in Emden, the federal government is accelerating the militarisation of the German coastline.
According to German Foreign Policy, the logistics infrastructure in Bremerhaven will be modernised and expanded to unload massive volumes of weapons and ammunition as quickly as possible and transport them onward to potential battlefields in Eastern Europe.
This is set out in a memorandum of understanding signed this week between the Ministry of Defence and municipal authorities in Bremen.
The federal government is providing up to 1.35 billion euros for this purpose, while the federal state of Bremen is contributing more than 212 million euros.
Bremen has the highest poverty risk and the highest child poverty rate of any federal state in the country.
The allocation of hundreds of millions of euros to expand military logistics rather than tackle poverty is also supported by senators from the Left Party (Die Linke) who sit in the state government.
Modernisation intensifies in Bremerhaven
Bremerhaven, Germany’s second-largest port in maritime freight handling behind Hamburg and ahead of Wilhelmshaven, is regarded as ideal for handling military cargo.
The port possesses significant capacity for offloading not only containers but also vehicles, alongside heavy-lift areas capable of handling even heavy military hardware such as main battle tanks. Moreover, because it can be accessed without passing through locks, access is substantially easier and faster.
Finally, it has good links to roads and particularly to railways, which is vital for the rapid transport of weapons and ammunition in the event of a crisis or war.
The port’s particular suitability as a military transshipment hub also stems from its history: it has been used by US forces since the end of the Second World War.
During the Cold War, it served as the central transshipment port in the Federal Republic of Germany and was expanded accordingly.
After 1990, it lost its significance for the US; however, with the escalation of the conflict in Ukraine, the US presence increased once more.
US activity escalated initially under exercises such as Defender Europe 2020 and subsequently from 2022 onwards in the context of the war in Ukraine.
As early as 2023, experts noted that Bremerhaven was operating as “an arms hub just like in the old days”.
Ports optimised for military logistics
The federal government is currently working to further increase the port’s military logistics capacity.
For instance, harbor basins will reportedly be dredged, and road and rail connections will be expanded.
Container facilities will be modernised and adapted to carry heavier loads.
This applies to both cranes and storage areas, with plans also in place to expand these storage areas into new zones.
A spokesperson for the port operating company Bremenports was quoted as saying: “The efficient transport of military hardware is no longer limited to tanks alone.”
Today, weapons and ammunition are also delivered in containers, which would need to be rapidly unloaded and forwarded in the event of war.
To ensure this, plans are also being made to build a new railway swing bridge at the Kaiserhafen. According to reports, the existing bridge is described as a “bottleneck” that slows down the movement of military equipment unnecessarily.
In addition, the heavy focus on military logistics demands costly security measures.
For example, not only will new fencing and privacy screens be erected, but drone defence systems will also be installed and cybersecurity measures implemented.
Left Party senators back armaments
The federal government is allocating approximately 1.35 billion euros through 2031 to optimise military logistics in Bremerhaven and, in conjunction with this, adapt Bremen Airport more effectively to the needs of the Bundeswehr.
According to the Mayor of Bremen, Andreas Bovenschulte, this represents the largest grant the German government has ever provided for a project in the federal state of Bremen.
The state of Bremen is contributing an additional 212 million euros to the “Bremerhaven 2031 Deployment Hub” project.
While large sums are being funnelled from Bremen’s state budget into war preparations in this manner, approximately 25.9% of the state’s population was classified as at risk of poverty in 2024, with 28.6% of all children living in poverty.
This makes Bremen the federal state with the highest poverty risk and the highest rate of child poverty.
Approval for funding military logistics in Bremerhaven with hundreds of millions of euros from the state budget also came from two Bremen senators belonging to the Left Party.
The Left Party’s Senator for Economic Affairs and Ports, Kristina Vogt, praised the “pragmatism” of “improving our infrastructure, which is already used for civilian purposes, for military ends” rather than constructing new facilities.
North Sea joins Baltic Sea militarisation
With the expansion of the Bremerhaven military hub, the militarisation of Germany’s coasts is progressing.
Until now, the focal point of Germany’s naval infrastructure has been the Baltic Sea coast. This was partly because during the Cold War, the naval activities of the Federal Republic of Germany were directed against the Soviet Union and Warsaw Pact states.
Alongside several training facilities, the German Navy primarily operates three major naval bases here, situated in Eckernfoerde, Kiel, and Rostock-Warnemuende, as well as the Naval Command based in Rostock.
In the North Sea, these are complemented by the naval base in Wilhelmshaven and the Naval Air Command at Nordholz near Cuxhaven.
The Naval Air Command is the third major unit of the German Navy, alongside Flotilla 1 based in Kiel and Flotilla 2 based in Wilhelmshaven.
At present, approximately 16,000 soldiers and 1,800 civilian staff from the Bundeswehr are stationed at the Navy’s main bases and various smaller installations.
As in other branches of the armed forces, the German Navy aims to expand its personnel numbers.
Germany’s fifth naval base to be built
In addition to the four existing naval bases and the Bremerhaven military hub, the federal government plans shortly to announce the construction of a fifth naval base, also located on the North Sea.
According to reports, Emden has been selected as the site for the base. Defence Minister Boris Pistorius and Lower Saxony’s State Minister Olaf Lies are scheduled to outline the next steps regarding a potential new naval base there on Monday.
Emden previously hosted a naval base during the Cold War, but the facility was closed in 1997.
According to reports, one argument in Emden’s favour is that it holds the largest unused area among Lower Saxony’s North Sea ports.
Discussions have been ongoing for some time over how to utilise this disused land reasonably, although these debates previously centred on civilian use.
According to the German Navy’s plans, the new naval base will accommodate seven frigates, ten minesweepers, and ten tugs, alongside a four-digit number of Bundeswehr soldiers and civilian personnel.
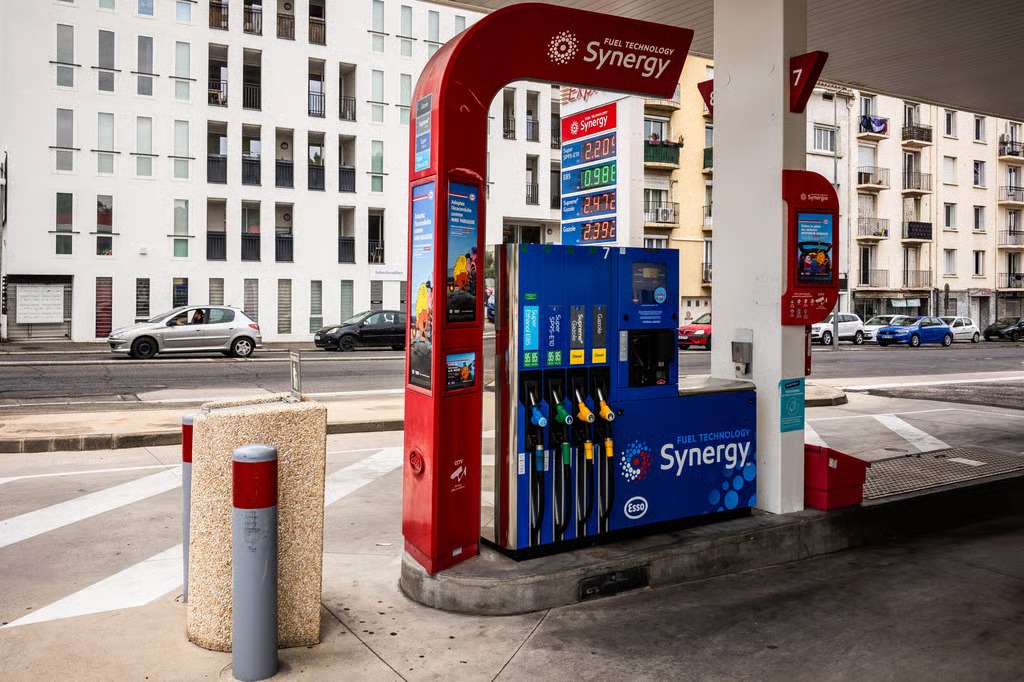
Five European countries have agreed to respond with “one voice” to mounting pressure from the US government to release their oil reserves.
Three European officials told Politico that France, Germany, Britain, Italy, Ireland, and the European Commission participated in talks to determine how to respond to pressure from Washington to draw down their oil reserves or face a ban on US diesel exports.
Two of these sources stated that all of these countries were placed under covert pressure by the US to run down their oil reserves or face a ban on diesel exports from the US.
According to the sources, these countries, together with the EU executive, agreed on three points: responding to the pressure with a “coordinated voice”, ensuring that “any decision on releasing stocks is brought to the IEA [International Energy Agency] level”, and seeking to “de-escalate tension in talks with the US”.
The Paris-based IEA coordinates energy policy among wealthy countries and oversaw the release of oil reserves earlier this year following the closure of the Strait of Hormuz.
One of the sources said the objective was to “de-escalate”:
“Being somewhat firm yet positive in communication… When you are facing a hungry lion, you do not necessarily have to play dirty with it.”
The source added that a wider group of countries, some of which have faced pressure from the Trump administration, would discuss how to react at a meeting scheduled for Friday.
Politico previously reported that US Energy Secretary Chris Wright had demanded the release of oil reserves into the market as an alternative to an export ban on which the EU heavily relies.
As a consequence of the wars in Ukraine and Iran, diesel prices in the US are soaring, placing significant pressure on US President Donald Trump to lower prices ahead of critical midterm elections.
The president is not ruling out an export ban, despite fierce opposition from the US oil industry.
Regarding the export ban, Trump said at an Oval Office event: “I am considering it. I speak to [Energy Secretary] Chris [Wright] and [Interior Secretary] Doug [Burgum] about this often. They think it would help diesel prices, but it could also raise the prices of other products.”
The EU wants to leverage its immense public spending power to bolster European industry through a “Made in Europe” initiative.
Deep divisions remain, however, over what should genuinely count as European-made.
According to a report by Politico, the European Parliament and member state governments are trying to establish their positions on the Industrial Accelerator Act (IAA), which forms part of Brussels’ effort to turn the “Made in Europe” slogan into an industrial strategy.
The initiative aims to use tenders and subsidies to create a guaranteed market for products of European origin.
Yet doing so requires answering politically contentious questions, such as how “European” a product must be to qualify, and how much more governments and consumers should be prepared to pay to buy domestic goods.
Disagreements are playing out not only between Parliament and the Council, but also among national governments and even between political allies from different countries.
Unveiled by the European Commission in March, the IAA seeks to channel public expenditure on green technology, energy-intensive industries, and motor vehicles towards European firms, helping them compete with dominant Chinese exporters.
Six months on, it is becoming increasingly clear how difficult it is to turn that objective into workable legislation.
Opposing sides broadly agree on the need to strengthen Europe’s industrial base, accelerate permitting procedures, and reduce strategic dependencies.
However, sharp divisions persist over how extensively the EU should support European manufacturing and how much flexibility national governments should retain.
Politico has identified five issues that will dominate negotiations through 2027.
The first issue is the debate over what qualifies as “Made in Europe”.
Defining EU origin is the most politically sensitive topic in the talks. With public procurement accounting for 15% of the bloc’s GDP—equivalent to roughly 3 trillion euros a year—the sums at stake are enormous.
If the threshold defining how European a product must be is drawn too narrowly, Brussels risks alienating close trading partners and disrupting supply chains.
Conversely, if drawn too broadly, the “Made in Europe” preference risks becoming meaningless.
Parliament is pressing for stricter anti-circumvention rules and demanding that at least 50% of a product’s value be created within the EU.
This condition would also make it harder for goods or components from third countries to be treated as equivalent to EU-origin items.
Lawmakers also aim to impose tighter conditions, including reciprocity, economic security measures, climate commitments, labour standards, and human rights safeguards.
The Council is more open to treating content from countries covered by the WTO Agreement on Government Procurement or relevant free trade agreements as equivalent to EU-origin content under specified conditions, including certain reciprocity principles.
Yet EU member states are still debating their positions and putting forward various conflicting proposals.
Ireland, which holds the Council presidency, plans to submit a fresh compromise proposal featuring the “Made in Europe” designation by mid-October.
Another issue is Foreign Direct Investment (FDI) screening.
Parliament wants a more comprehensive and stringent system to screen foreign investment in strategic sectors.
Underpinning this demand is the concern that, despite the EU spending billions to develop strategic industries, subsidized or otherwise state-backed foreign investors could acquire the very companies and assets the EU helped build.
Lawmakers want to lower the review threshold from the proposed 100 million euro investment figure to 50 million euros, bring affiliates of foreign investors under the rules, and lower the control threshold that triggers mandatory notification.
They also want to give the Commission a stronger role, granting it the power to block investments in critical raw materials when EU funds are involved.
The Council’s position is narrower: it broadly retains the 100 million euro FDI threshold and the 30% control threshold set out in the Commission’s original proposal, while granting national authorities greater flexibility in managing the approval process.
The two institutions are at odds not only over the scope of screening, but also over the institutional balance of power between Brussels and national capitals.
The third issue centres on the scope of tenders and subsidies.
Both sides want public tenders and state support to drive demand for European-made, low-carbon goods.
However, opinions diverge on how broadly the rules should apply.
This is where political goals collide directly with public purse strings. Requiring governments to purchase European-made goods could spur demand for domestic manufacturers, but it could also force taxpayers to pay more when cheaper imported alternatives are available.
Parliament wants various requirements—such as green, social, or “Made in EU” criteria—to cover up to 90% of state aid or subsidy programmes, compared with 45% in the Council text.
It also proposes tighter social and labour conditions, relocation curbs, and stricter verification and enforcement mechanisms.
The Council favours broader exemptions where suitable products are unavailable, excessively costly, or technically unviable.
This posture reflects governmental concerns over higher public spending or project delays linked to reliance on imported components.
The fourth issue is the divergence over sectoral targets.
Parliament generally seeks higher and more granular European-origin content requirements for batteries, solar panels, wind turbines, electrolysers, nuclear technologies, and electric vehicles.
Electric cars illustrate how complex the “Made in Europe” concept can become in practice.
A vehicle assembled within the EU may contain a battery and raw materials sourced through supply chains spanning the globe.
Parliament plans to raise the required EU-origin share for non-battery vehicle components from the 70% proposed by the Commission to 75%.
Requirements governing battery materials, binders, and strategic raw materials would also be introduced.
The Council’s stance, by contrast, is less prescriptive and allows for a more phased implementation.
The dispute is not over whether strategic sectors should receive support, but whether the IAA should impose binding content targets that could push up costs for manufacturers and consumers.
The fifth and final debate concerns the sectors covered by the Industrial Accelerator Act.
The argument centres on whether the IAA should remain a targeted response to strategic dependencies or become a broader vehicle for EU industrial policy.
Parliament wants to expand the legislation to cover areas such as maritime manufacturing, materials recovery, and certain plastic products used in construction.
It also wants sectors such as fertilizers, rolling stock, robotics, and aerospace considered in future reviews.
The Council text focuses more tightly on sectors already identified, including energy-intensive industries, automotive, net-zero technologies, and critical raw materials.
The debate reflects wider friction over how far the EU should extend “Made in Europe” preferences.
When public procurement and subsidies are deployed in certain strategic sectors to shield domestic manufacturing, other industries gain a strong incentive to argue that they too should benefit.
According to a separate report by Politico, Brussels is prepared to grant candidate countries access to its single market, provided they agree to align with the bloc against “hostile states” and industrial competitors.
Under the draft plan, candidate countries would receive unprecedented “gradual integration” into the single market while their accession bids are assessed, including frictionless trade and access to research programmes.
An assessment of “pre-enlargement” benefits to be offered to candidate nations states: “The single market is the primary driver of economic convergence.”
The draft states:
“Earlier integration will create opportunities for businesses across the Union, strengthen European value chains, and reduce strategic dependencies. The Commission will identify sectors where verified regulatory alignment and enforcement capacity allow for deeper participation in research, innovation, and industrial cooperation, as well as broader market access. Priority should be given to opportunities that advance accession preparations and address shared economic and strategic needs.”
Overseen by Alexandre Adam, top adviser to Ursula von der Leyen and former aide to French President Emmanuel Macron, the review would fundamentally transform the EU’s approach to neighbouring countries.
At present, almost all the economic advantages of closer cooperation remain reserved for member states.
No new country has joined the EU since Croatia’s accession in 2013.
As part of Adam’s package of measures, Ukraine, Moldova, Albania, and Montenegro are set to receive “roadmaps” designed to accelerate their accession process in the coming years.
For other nations, including North Macedonia, Kosovo, Bosnia and Herzegovina, Serbia, and Türkiye, the process continues to drag on amid mounting fears that they could drift away from the EU or draw closer to Russia or China.
Under the Commission’s blueprint, economic benefits extended to candidate countries would depend on their backing of EU foreign policy goals.
Single market access would hinge on candidate states not sharing key technologies with hostile governments and commercial rivals.
The review document notes:
“As industrial and market integration deepens, participation in sensitive sectors must go hand in hand with cooperation on investment screening, export controls, sanctions enforcement, and the protection of sensitive technologies. Access assessments must consider strategic alignment, critical dependencies, and the capacity to manage risks to infrastructure and supply chains. Where these conditions are not met, the scope of participation should be recalibrated under the relevant regulatory framework.”
Areas being considered for closer cooperation include semiconductors, quantum technologies, biotechnology, artificial intelligence, and space.
According to the review, full EU membership must remain the ultimate goal for candidate countries.
“Yet accession takes time: candidate countries must complete a rigorous, merit-based process and deliver comprehensive, enduring reforms,” the report notes. “This period must be fully exploited strategically, both to prepare the Union for a wider membership and to deepen gradual integration in areas of mutual interest.”
The benefits gained, however, will be contingent on countries fulfilling their obligations:
“Where these commitments are not honoured, integration must be reversible. The accession process should be suspended or rolled back where deemed necessary.”

Germany expands North Sea military ports and plans new naval base

Musk appointed co-director of Pentagon future warfare initiative

US waives human rights terms on $320m military aid to Egypt

Putin says Russia did not start war and warns of nuclear risks

European nations unite against US pressure over strategic oil stocks
-
 Europe5 days ago
European unions urge governments to scrap all Palantir deals
-
 Diplomacy5 days ago
East-West Forum in Istanbul highlights irreversible shift to multipolarity
-
 Europe1 week ago
Emmanuel Todd says West faces collapse amid Ukraine and Iran crises
-
 Europe1 week ago
European intelligence chiefs divide over risk of Russian attack
-
 Diplomacy1 week ago
East-West Forum in Istanbul to debate multipolarity and global order
-
 Middle East1 week ago
Sharaa says 7 October must not shape Israel policy on Syria
-
 America1 week ago
Republican support for Trump’s war with Iran drops sharply in polls
-
 Middle East1 week ago
Palestinian factions confront legitimacy crisis at Istanbul talks
